The average monthly payment for a new-vehicle lease was around $619 in the first quarter of 2026, while the average payment on a new vehicle loan reached $770, according to Experian data reported by LendingTree. More recent Experian figures cited by NerdWallet put the average new-car loan payment at $765 in the second quarter of 2026. That creates a roughly $146 monthly gap between the typical new-car loan and lease.
That difference does not necessarily mean leasing is the better financial choice. Leasing typically means returning the vehicle at the end of the term rather than owning it, while mileage limits may apply and advertised payments often require money upfront.
Even so, several 2026 models currently offer lease programs well below the $617 benchmark. These cars and SUVs show where leasing may be worth considering for drivers who want to keep monthly payments low while driving a new vehicle.
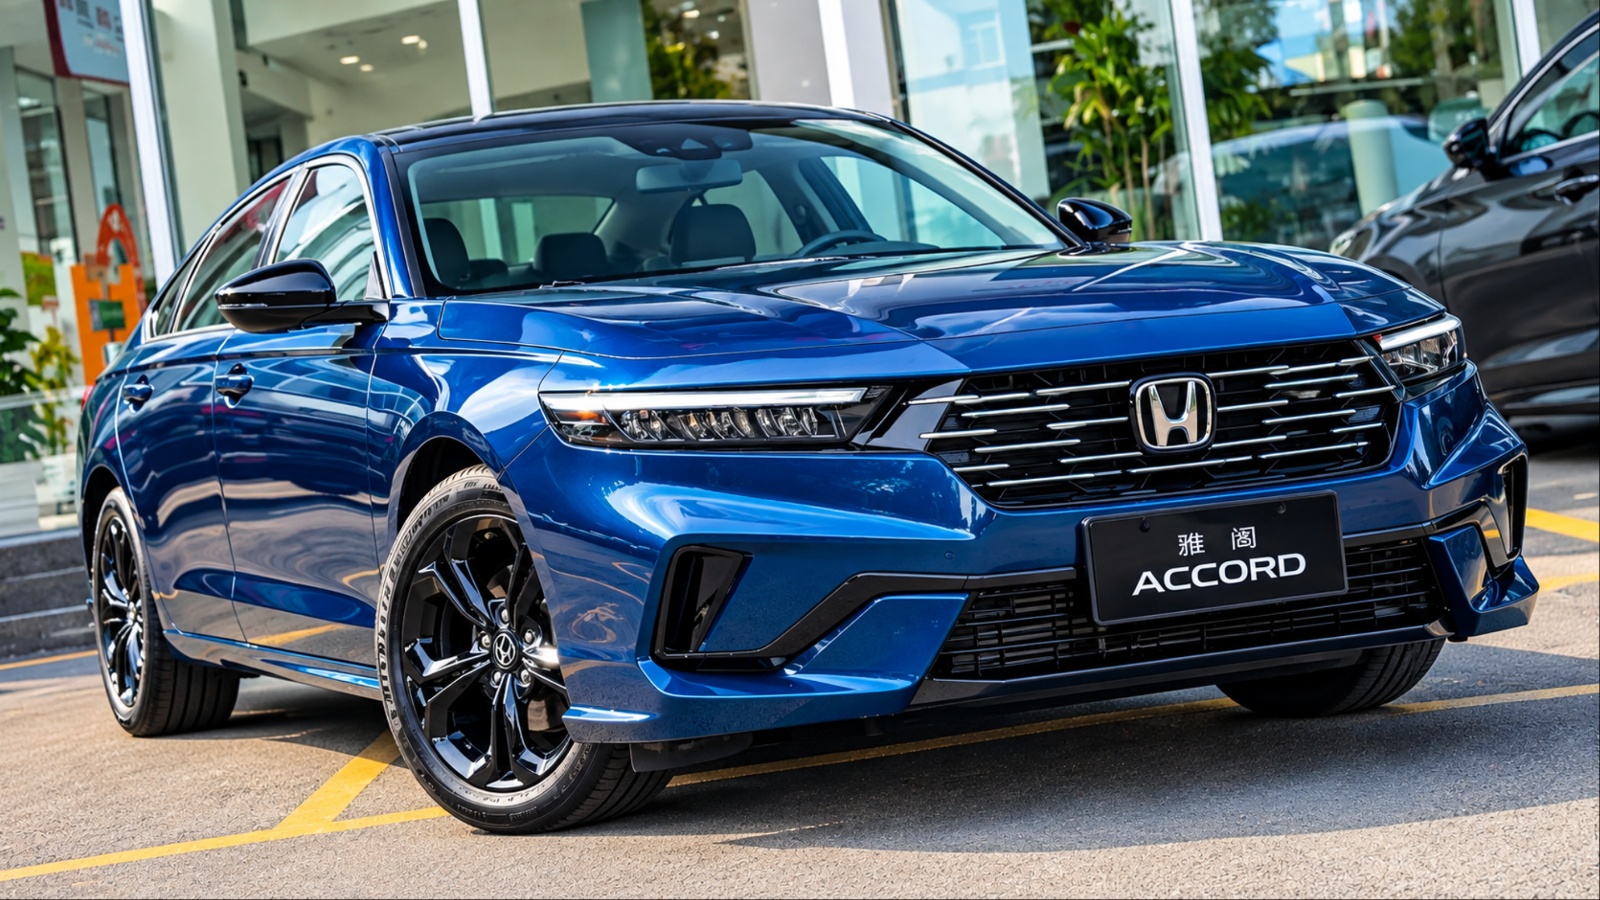
1. 2026 Honda Accord
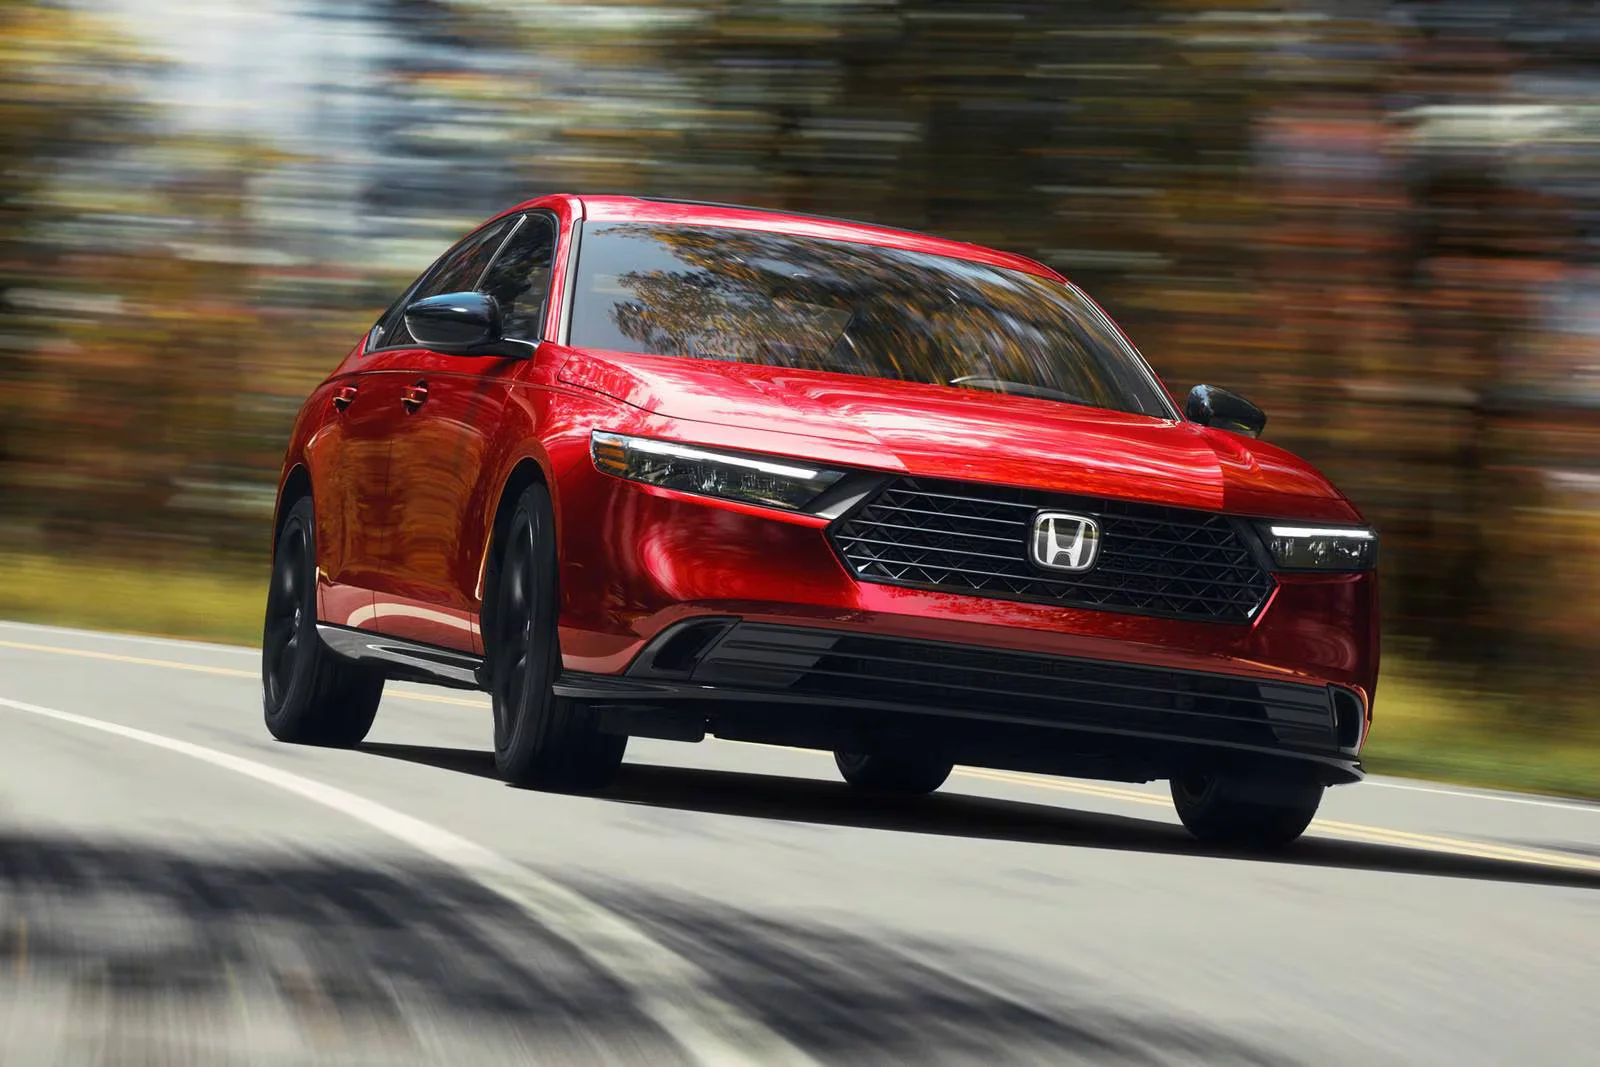
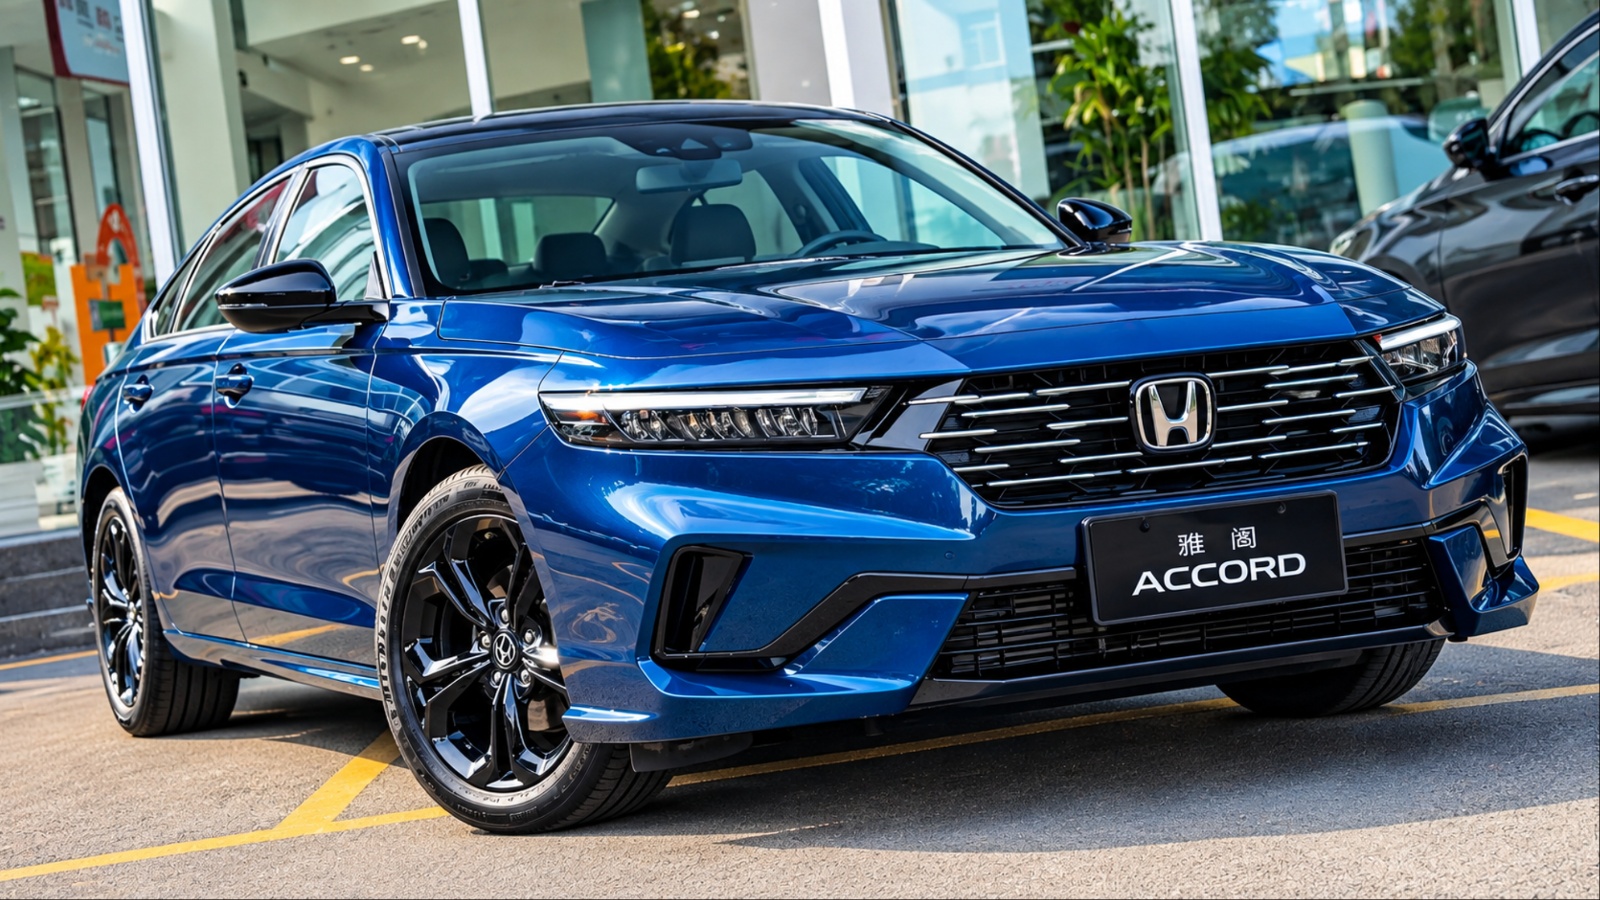
The 2026 Honda Accord is a particularly interesting example of how a lease can bring a relatively expensive new vehicle well below the $617 monthly-payment benchmark. Kelley Blue Book lists a September 2026 offer of $229 per month for 36 months with $3,999 due at signing on the Accord, based on an MSRP of $29,590.
The advertised offer is scheduled to run through November 2, 2026, although regional availability and eligibility can affect the actual transaction.
The Accord also makes sense as a lease candidate because its appeal isn’t limited to a low entry price. It is a midsize sedan with a spacious cabin, useful rear-seat room, and a broad range of standard equipment. Kelley Blue Book notes that the gas-powered versions can achieve 32 mpg combined, depending on configuration.
The important consideration is the upfront payment. A $229 advertised payment doesn’t mean the effective monthly cost is only $229 when the $3,999 due at signing is included. Spread across 36 months, that upfront amount adds roughly $111 per month before taxes and other charges. Even so, the resulting effective cost remains substantially below the $617 national lease benchmark.
For someone who changes vehicles every few years and doesn’t need ownership equity, the Accord demonstrates why a manufacturer-supported lease can be attractive.
2. 2026 Toyota RAV4
The 2026 Toyota RAV4 is another model where leasing can create a large difference compared with financing a new vehicle. Kelley Blue Book lists a September offer of $279 per month for 36 months with $3,999 due at signing for the RAV4 LE, with an MSRP of $33,495. The offer is listed through September 30, 2026.
Toyota’s latest RAV4 is particularly significant because the 2026 model is offered as a hybrid-only vehicle in the United States. KBB cites an EPA rating as high as 44 mpg combined for certain configurations, giving the SUV an efficiency advantage over many conventional gasoline-powered competitors.
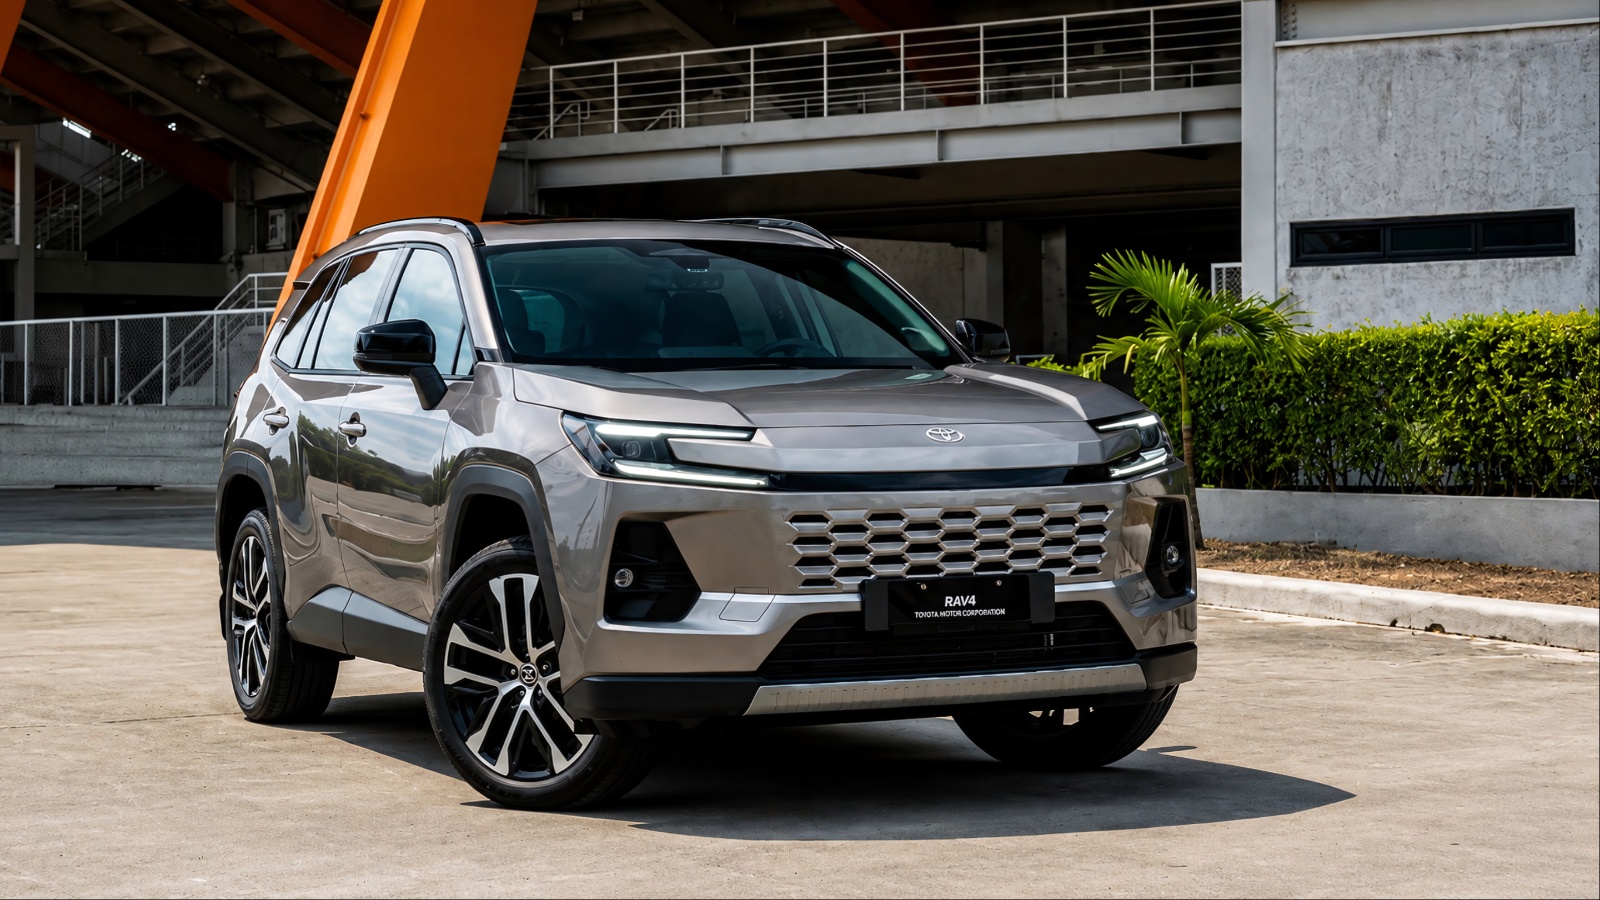
The advertised payment is less than half the $617 average lease figure. Even after accounting for the $3,999 due at signing, the effective payment remains considerably lower than the average new-car loan payment of $765 cited by NerdWallet from Experian’s second-quarter 2026 data.
There is still a reason to examine the numbers carefully. Leasing limits how many miles can be driven without additional charges, and the vehicle must generally be returned in acceptable condition. A buyer who intends to keep a RAV4 for eight or ten years may have a completely different financial calculation. But for someone planning a three-year ownership cycle, the current RAV4 lease demonstrates how manufacturer incentives can make leasing unusually competitive.
3. 2026 Kia Sportage
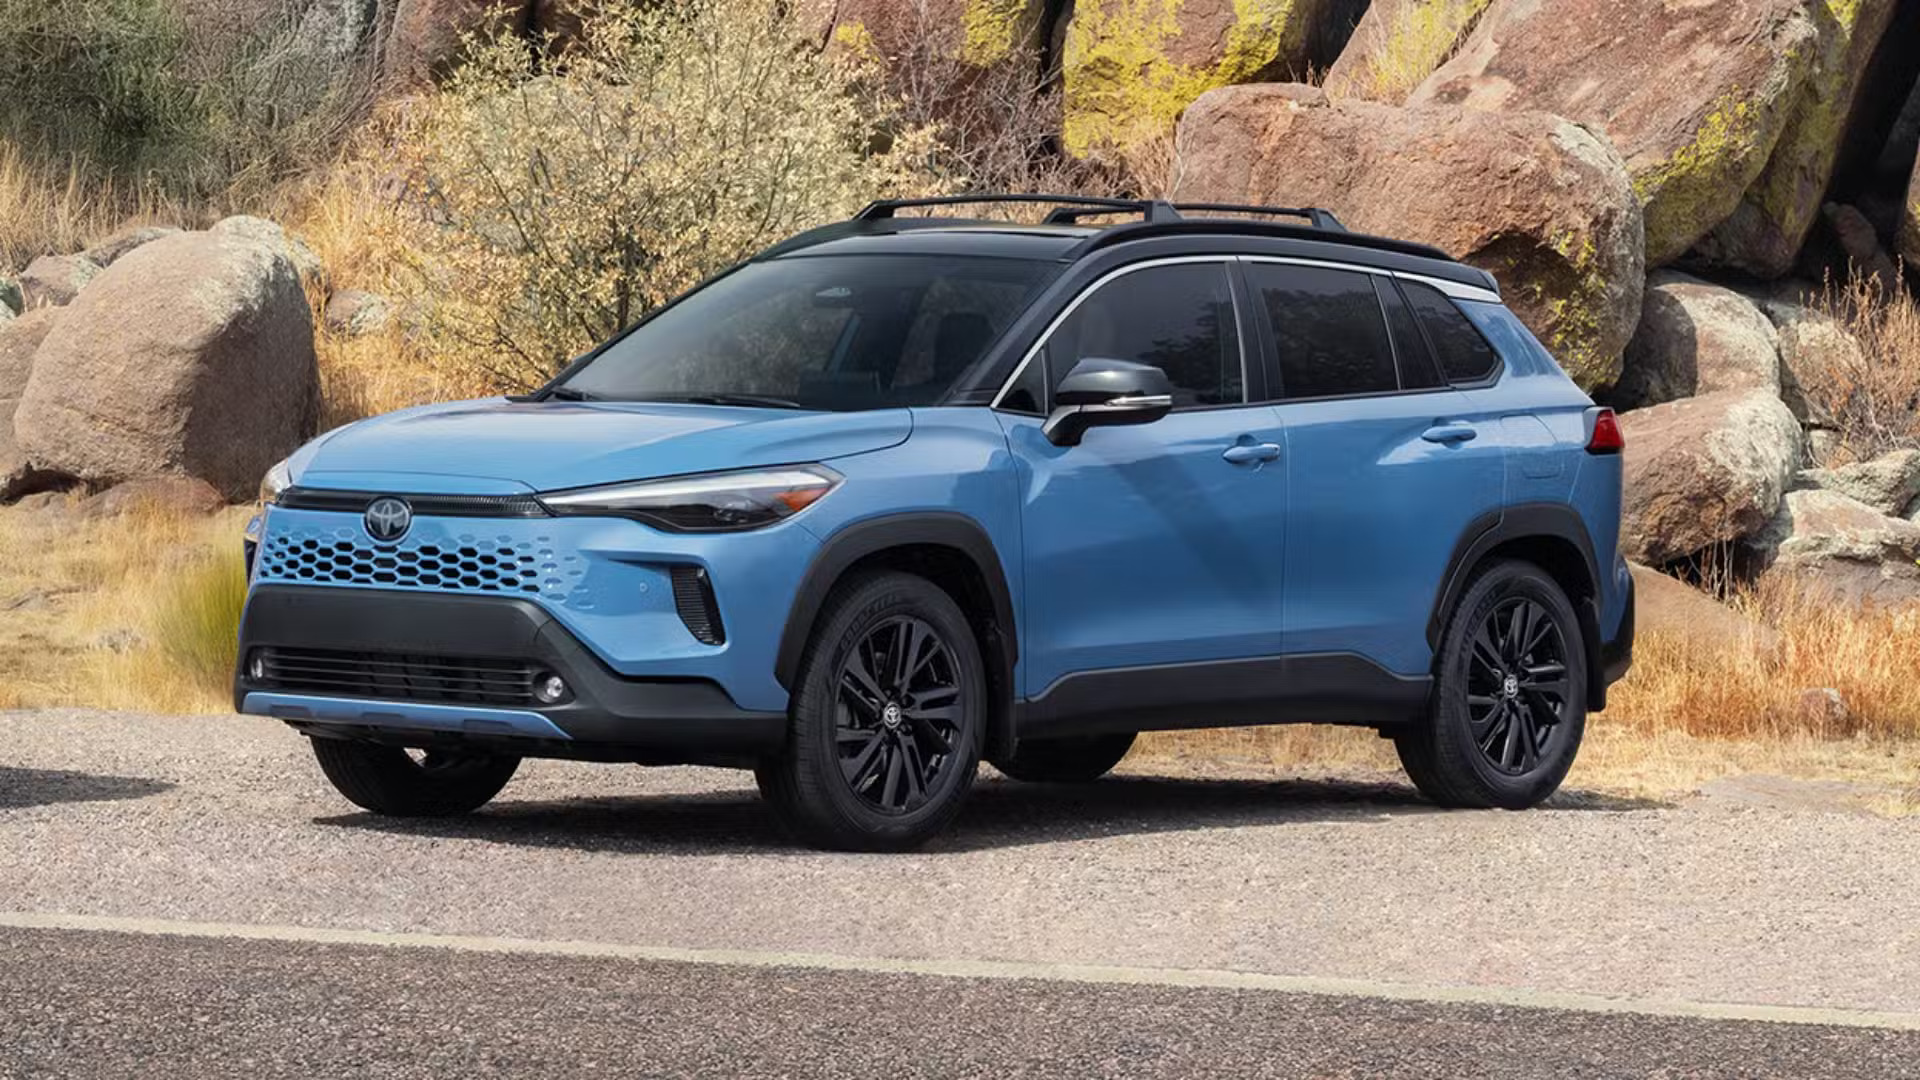
The 2026 Kia Sportage provides another example of an SUV whose lease payment can sit far below the national average. Kelley Blue Book’s September 2026 lease information lists the gas-powered Sportage LX at $239 per month for 36 months with $3,999 due at signing. The listed MSRP is $30,285, and the offer is scheduled to expire September 30, 2026.
That payment is only a fraction of the $765 average new-car loan payment reported for the second quarter of 2026. Even after incorporating the upfront amount into the monthly cost, the effective payment remains well below the $617 lease benchmark.
The Sportage is also useful for shoppers who need more practicality than a compact sedan provides. It offers generous rear-seat space and a useful cargo area, while Kia offers gasoline, hybrid, and plug-in-hybrid versions of the model. The particular lease promotion, however, applies to the front-wheel-drive gas-powered LX. KBB says the comparable AWD promotion raises the payment to $259 per month.
The case for leasing becomes stronger for drivers who prefer replacing their vehicle every few years and want predictable monthly expenses. The case for buying becomes stronger for high-mileage drivers or people who intend to keep the vehicle after the loan is paid off.
In other words, the Sportage’s low advertised lease payment doesn’t eliminate the normal disadvantages of leasing, but it creates a sizable payment advantage.
4. 2026 Toyota Corolla
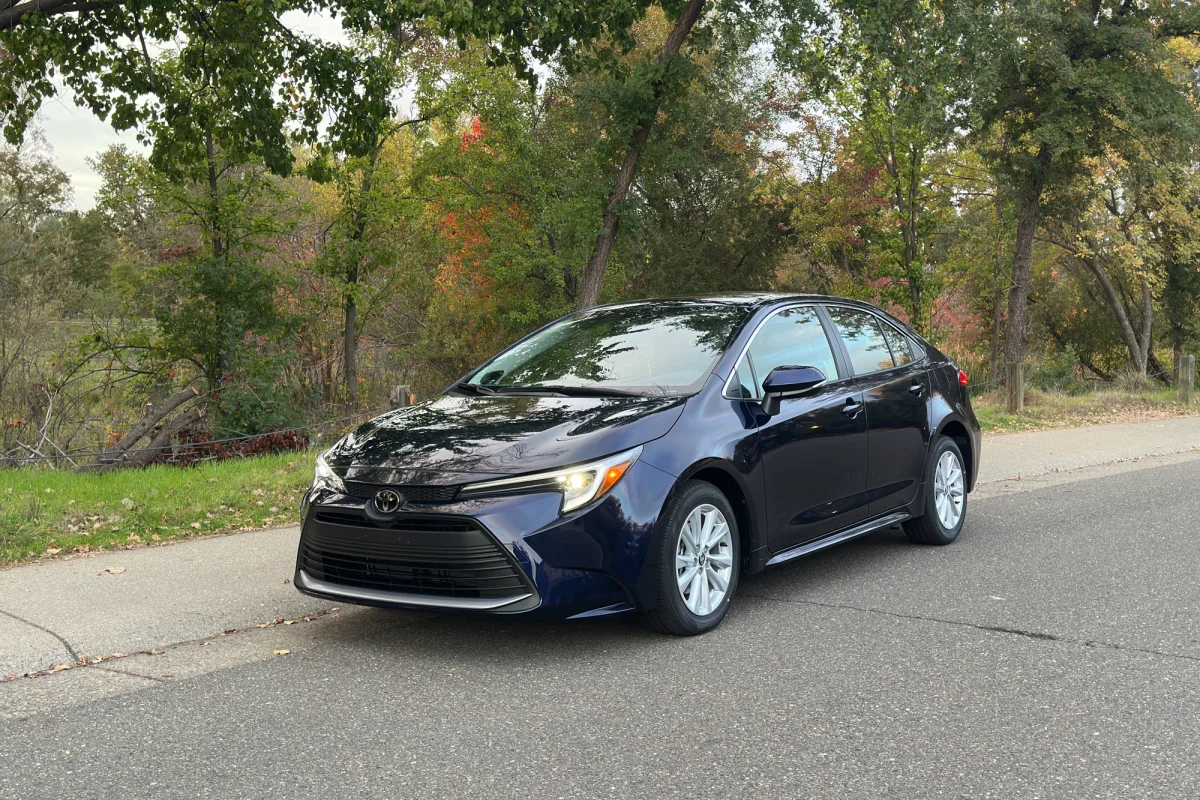
The 2026 Toyota Corolla is one of the clearest examples of a vehicle where current lease incentives can make the monthly payment dramatically lower than the $617 benchmark. Toyota’s September 2026 offers include a $199-per-month lease for 36 months, with $4,198 due at signing for a Corolla LE.
Kelley Blue Book also lists a $219-per-month September lease promotion with $2,999 due at signing, illustrating how advertised pricing can vary by program and market.
The Corolla’s appeal goes beyond the payment. The compact sedan has a long-established reputation for fuel efficiency and durability, and the 2026 model includes Toyota’s Safety Sense 3.0 driver-assistance package along with smartphone integration through an 8-inch touchscreen.
At $199 per month, the advertised payment is less than one-third of the $765 average new-car loan payment. Even after spreading the upfront amount across the 36-month term, the effective monthly cost remains substantially lower than the national loan average.
However, buyers should remember that a low lease payment doesn’t produce ownership equity. At the end of the lease, the driver normally returns the Corolla unless purchasing it under the lease’s buyout provisions. For someone who wants a simple three-year transportation cycle, that may be perfectly acceptable. For someone who plans to drive the same Corolla for a decade, purchasing could have advantages after the financing ends.
5. 2026 Toyota Corolla Hybrid
The 2026 Toyota Corolla Hybrid takes the same low-payment leasing strategy and adds a hybrid powertrain. Toyota lists a September 2026 lease offer of $209 per month for 36 months with $4,208 due at signing for the Corolla Hybrid LE.
That advertised payment is dramatically below both the $617 average lease payment and the $765 average new-vehicle loan payment cited from Experian’s second-quarter 2026 data.
For commuters, the hybrid powertrain can make the Corolla Hybrid particularly appealing. Instead of paying a premium for a larger hybrid SUV, shoppers can combine a relatively inexpensive compact sedan with hybrid technology and a manufacturer-supported lease.
The financial calculation still requires more than looking at the monthly figure. The $4,208 due at signing needs to be considered when determining the true monthly cost. Taxes, registration, insurance, and other fees can also change the amount actually paid.
Mileage is another important consideration. Lease contracts commonly establish annual mileage limits, so drivers who regularly travel long distances need to check the contract before signing.
Nevertheless, the Corolla Hybrid illustrates why leasing can outperform financing from a monthly-budget perspective. Someone who wants a new hybrid every three years can potentially spend considerably less each month than the average new-car borrower.
For buyers intending to keep the car for many years, however, the calculation changes because ownership eventually eliminates the monthly loan payment.
6. 2026 Toyota Prius Plug-In Hybrid
The 2026 Toyota Prius Plug-In Hybrid provides an unusual combination of electrification and a relatively low lease payment. Toyota’s September offers list the Prius Plug-in Hybrid SE at $319 per month for 36 months with $4,318 due at signing.
The Prius name has long been associated with fuel efficiency, while the plug-in version adds the ability to drive on electricity for shorter trips before switching to hybrid operation. That makes it potentially appealing to commuters who can regularly charge at home but still want the flexibility of a gasoline engine for longer journeys.
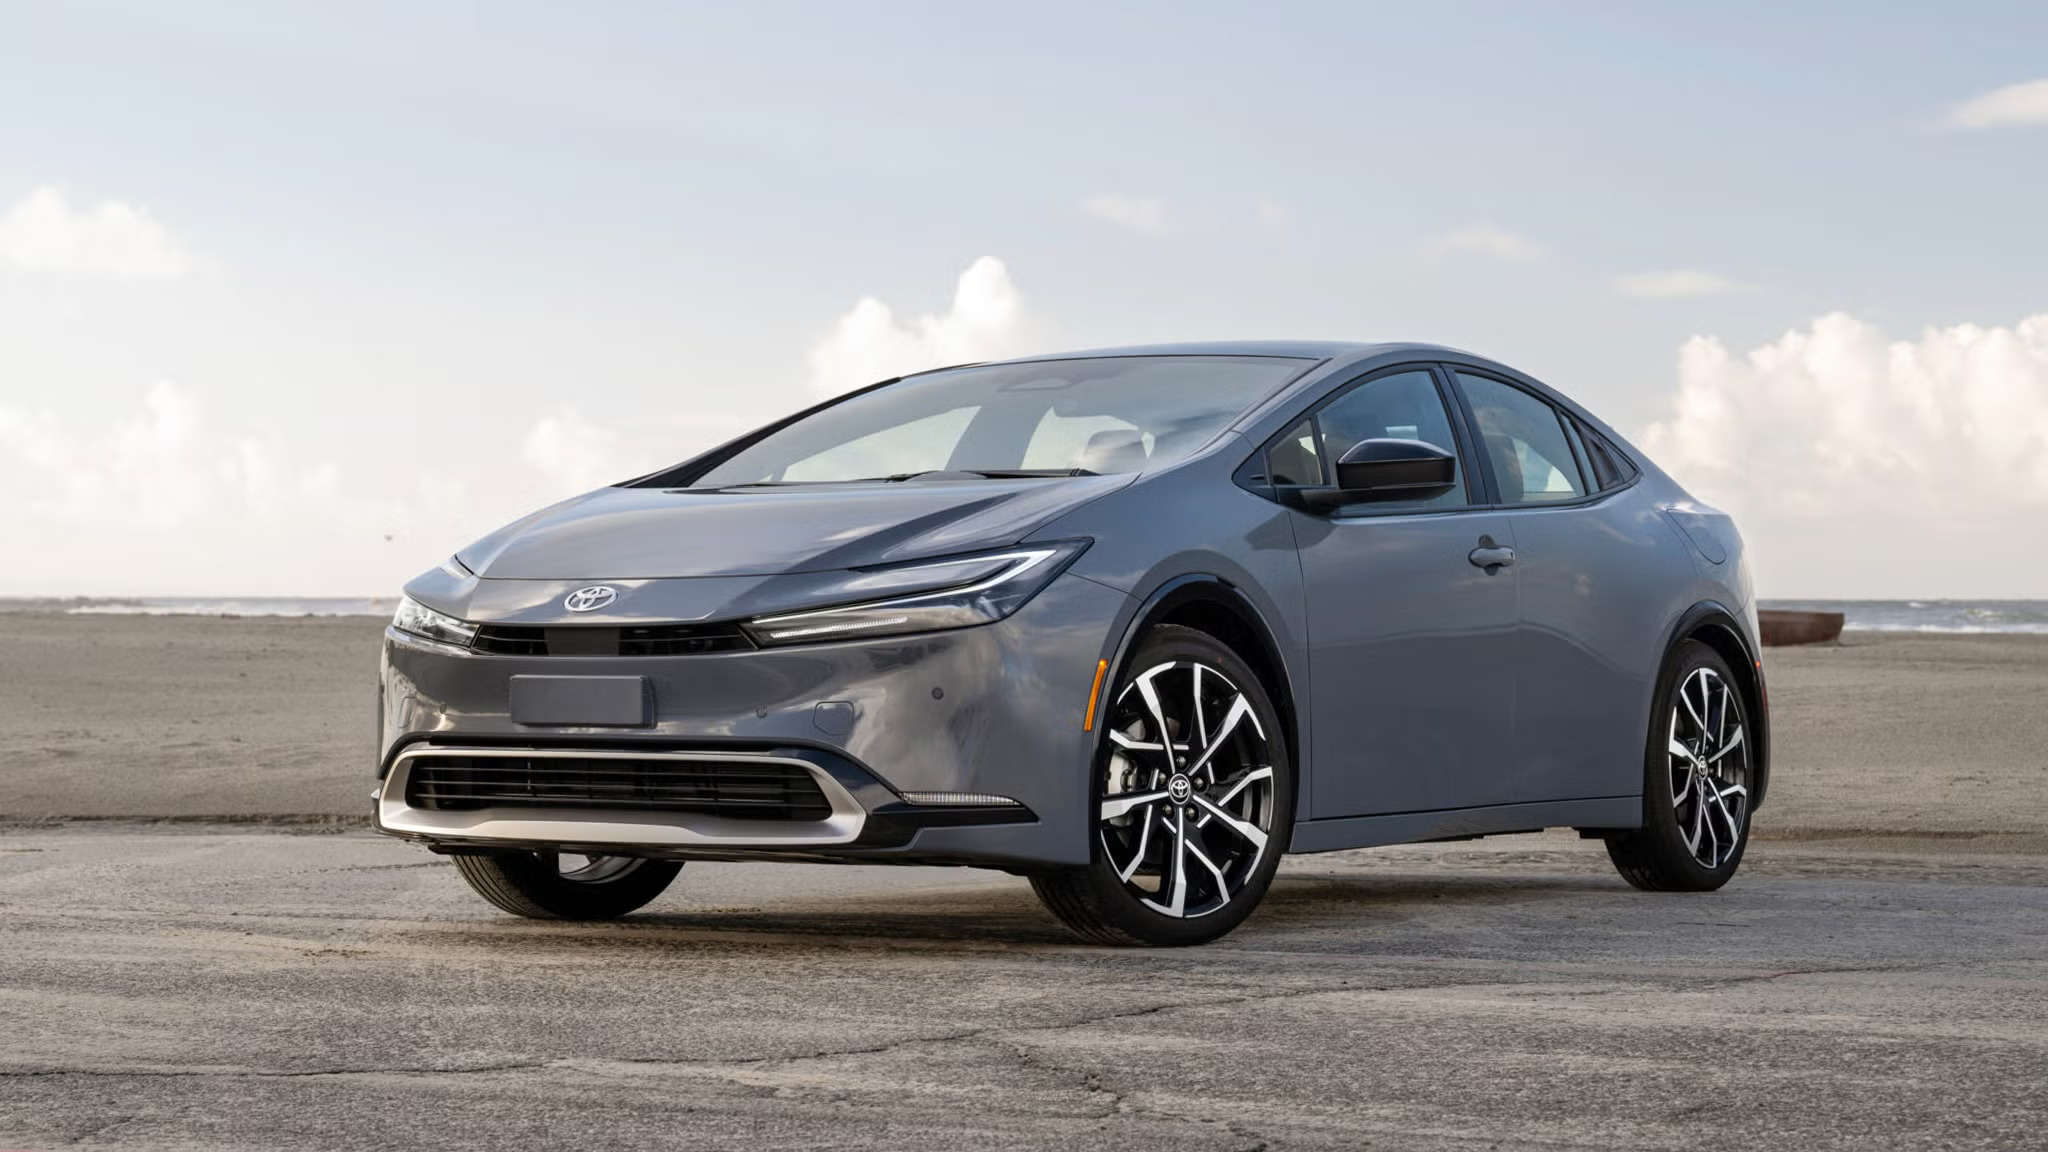
At $319 per month, the advertised lease payment is nearly $300 below the $617 benchmark. Even after accounting for the upfront payment, the effective monthly cost remains below the national average lease payment reported for 2026.
The main question is whether the lease structure matches the driver’s usage. A plug-in hybrid can provide the most benefit when it is charged regularly. A driver without convenient charging access may not receive the same fuel-cost advantage.
There is also the ownership question. A three-year lease provides a relatively straightforward way to use the latest electrified technology without committing to long-term ownership. Conversely, someone who intends to keep a vehicle for many years may prefer purchasing and eventually driving it without a monthly payment.
The Prius Plug-in Hybrid therefore represents a case where leasing can keep the initial monthly obligation far below the current new-car financing average.
7. 2026 Toyota RAV4 Plug-In Hybrid
The 2026 Toyota RAV4 Plug-In Hybrid pushes the lease price higher than the conventional RAV4 but still remains well below the $617 benchmark. Toyota’s September 2026 offer lists the RAV4 Plug-in Hybrid SE at $399 per month for 36 months with $4,398 due at signing.
That gives shoppers access to a larger electrified SUV without approaching the average $765 new-car loan payment reported for the second quarter of 2026.
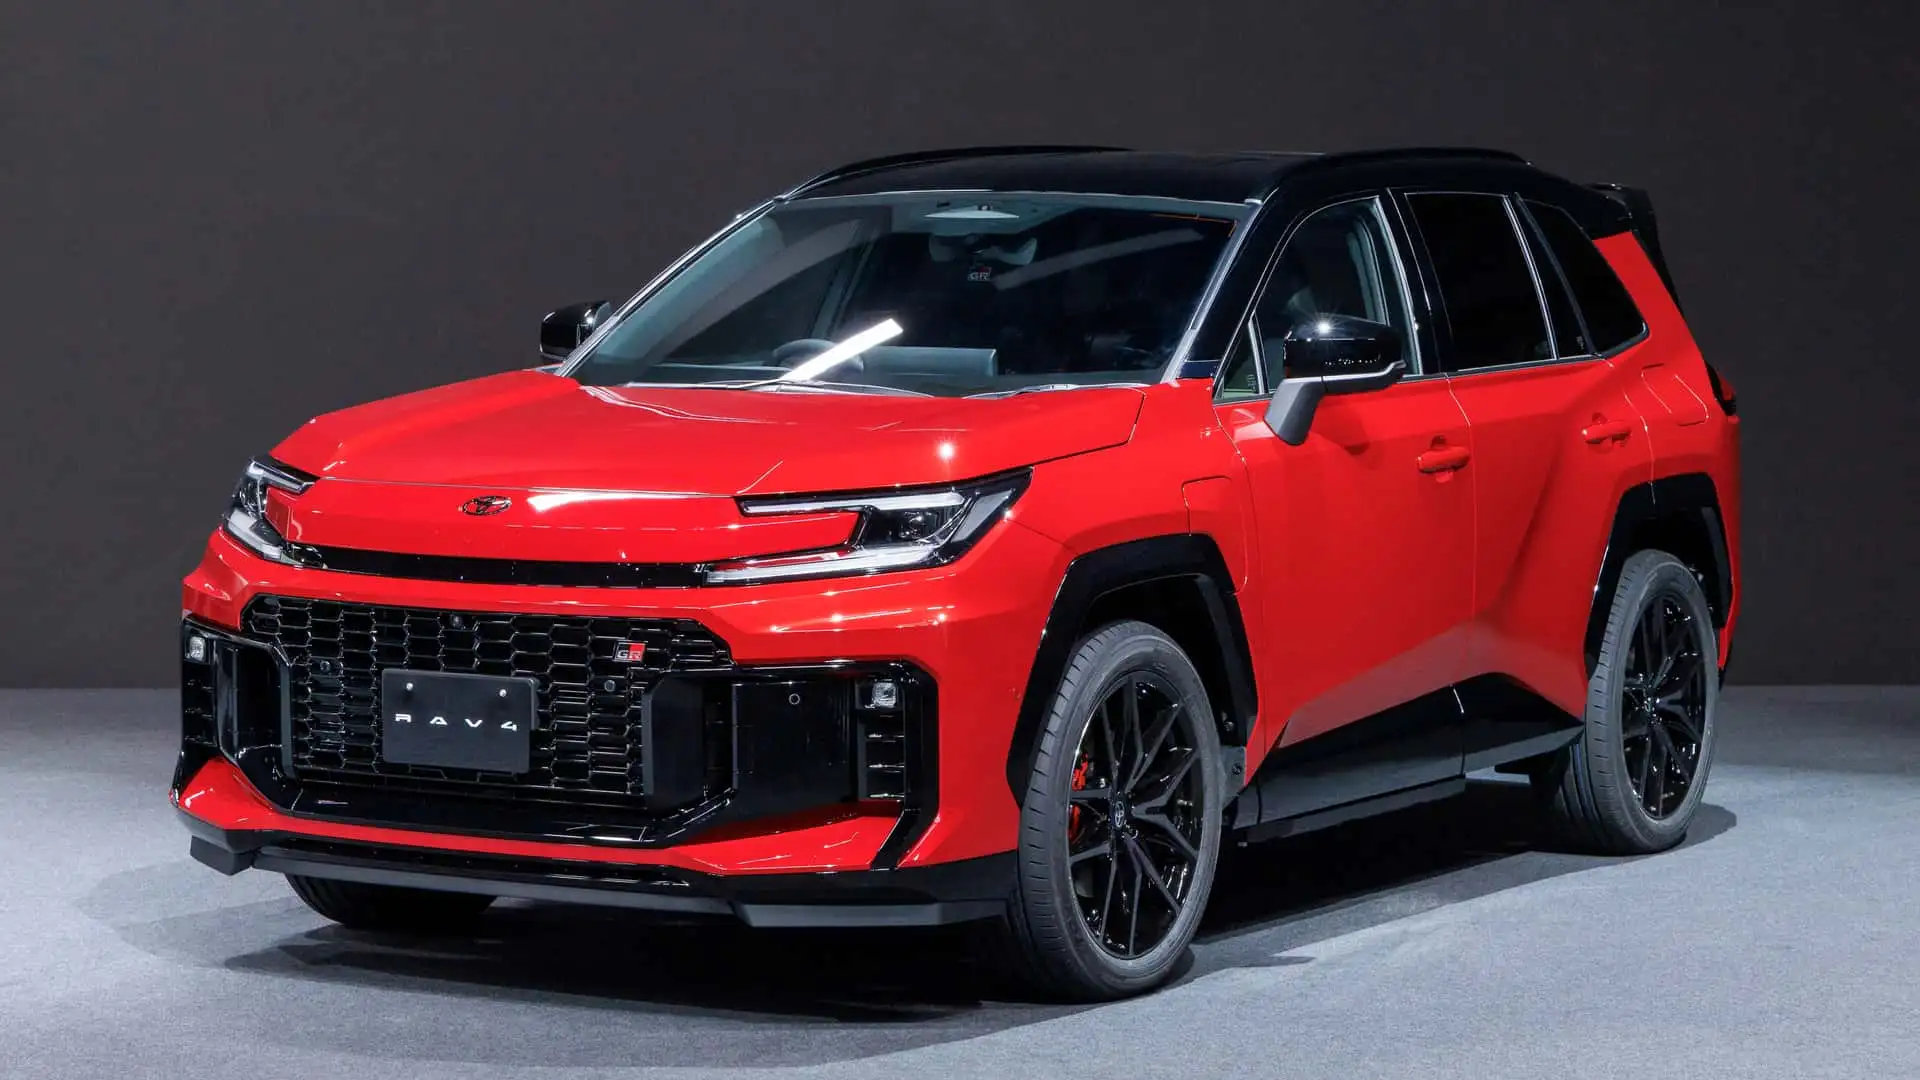
The appeal is the combination of SUV practicality and plug-in capability. A driver who can charge regularly may be able to complete many daily trips using electricity while retaining the convenience of a gasoline-powered system for longer journeys.
The lease payment itself is only part of the calculation. Spread across 36 months, the $4,398 due at signing adds about $122 per month before taxes and fees. That puts the effective pre-tax cost substantially higher than the advertised $399 figure, although it remains below $617.
The vehicle also demonstrates why consumers should compare the complete lease structure rather than simply choosing the advertisement with the lowest monthly number. Money due at signing, mileage allowance, acquisition fees and disposition charges can materially affect the total cost.
Still, for a driver seeking an electrified SUV on a three-year cycle, the current RAV4 Plug-in Hybrid promotion shows how leasing can produce a substantially lower monthly obligation than financing a new vehicle at today’s average loan payment.
8. 2026 Toyota Crown
The 2026 Toyota Crown occupies a different position from the compact Corolla and midsize Accord, making its current lease promotion particularly notable. Toyota lists the Crown XLE at $449 per month for 36 months with $4,448 due at signing through September 30, 2026.
That payment is still $168 below the $617 benchmark for a new-vehicle lease and $316 below the $765 average new-car loan payment cited by NerdWallet.
The Crown is a larger, more distinctive sedan-like vehicle than the Corolla, making the lease attractive to shoppers who want something positioned above a traditional compact or midsize sedan without moving into a luxury-brand payment.
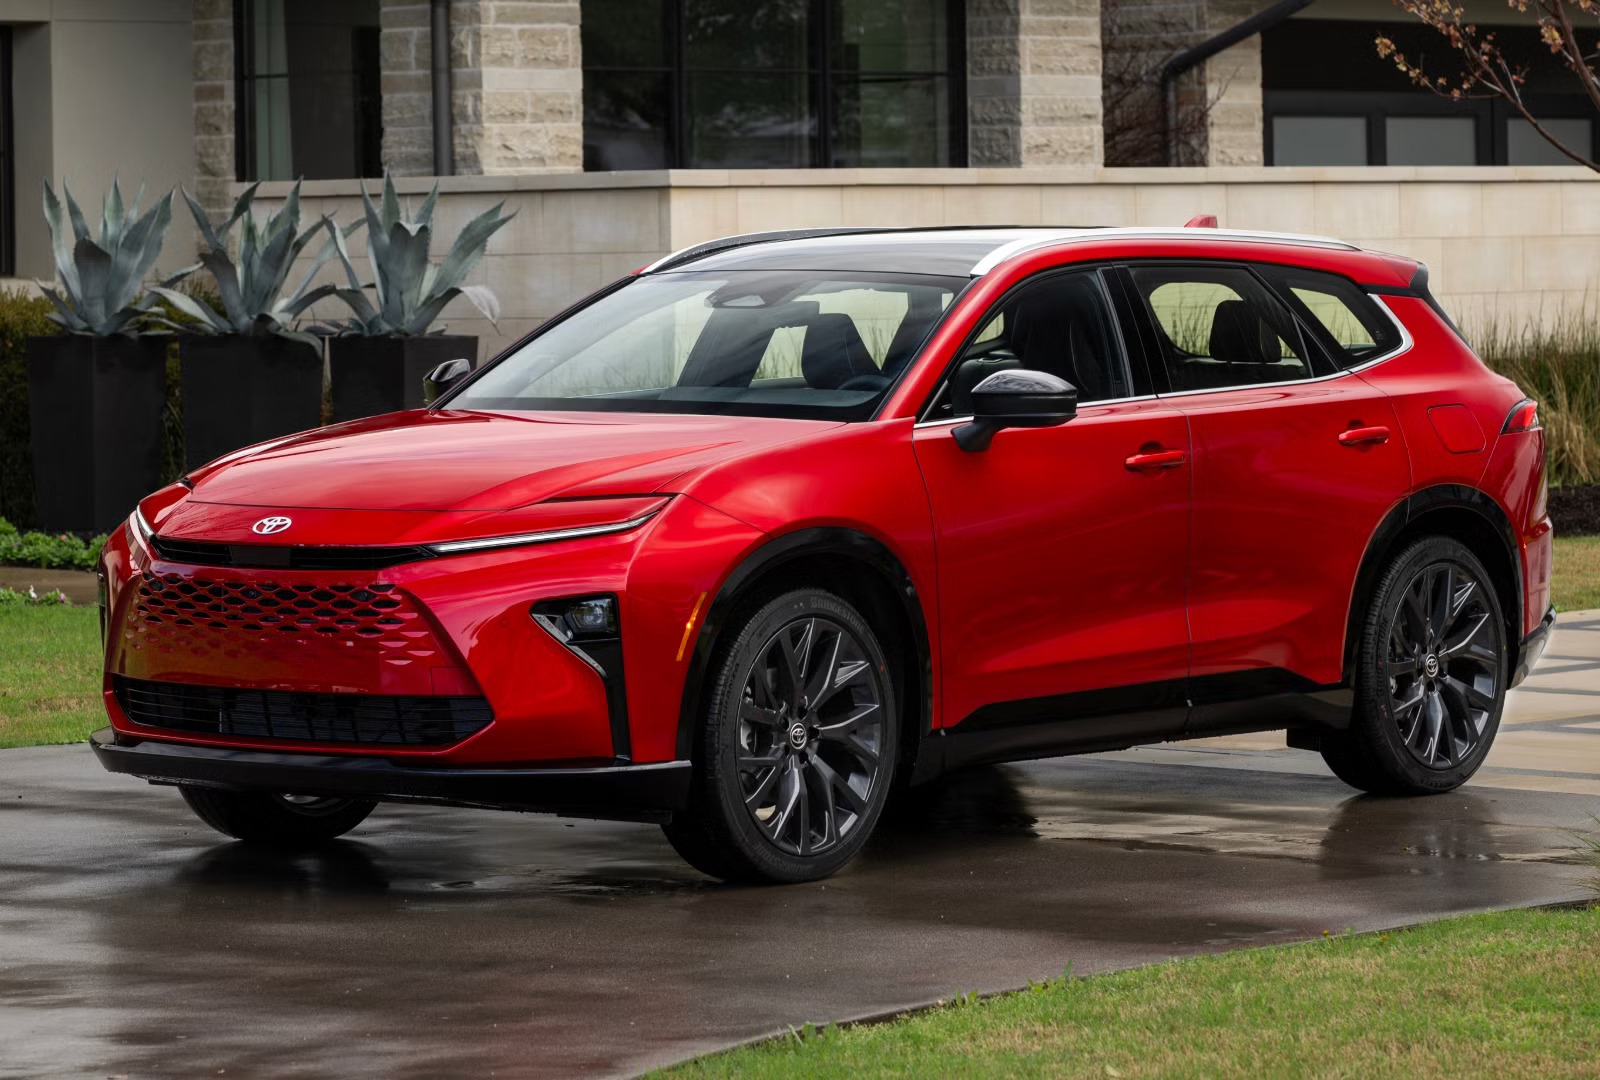
The upfront payment changes the picture somewhat. Dividing $4,448 over the 36-month term adds roughly $124 per month before taxes and other charges. Consequently, the effective monthly cost is considerably higher than the advertised $449, although it remains below the $617 benchmark before other expenses.
This is an important distinction for any lease article: advertised monthly payments should not be treated as the complete cost of the vehicle.
The Crown also makes sense as a lease candidate for people who appreciate regularly changing vehicles. Technology, styling and electrified powertrains continue to evolve quickly, and a three-year lease can provide a relatively short commitment.
For someone who wants to own the vehicle for a decade, however, the benefits of eventual ownership should be weighed against the lower initial lease payment.
9. 2026 Kia EV9
The 2026 Kia EV9 demonstrates how leasing can be particularly compelling in the electric-vehicle market. Edmunds’ September 2026 lease analysis lists the EV9 at $511 per month, with $511 due at signing, for a 36-month term. The listed MSRP is $59,545.
That is an important difference from many conventional financing scenarios because the EV9 is a large three-row electric SUV rather than an entry-level compact car. Its advertised lease payment remains below the $617 national lease benchmark and well below the $765 average new-car loan payment.
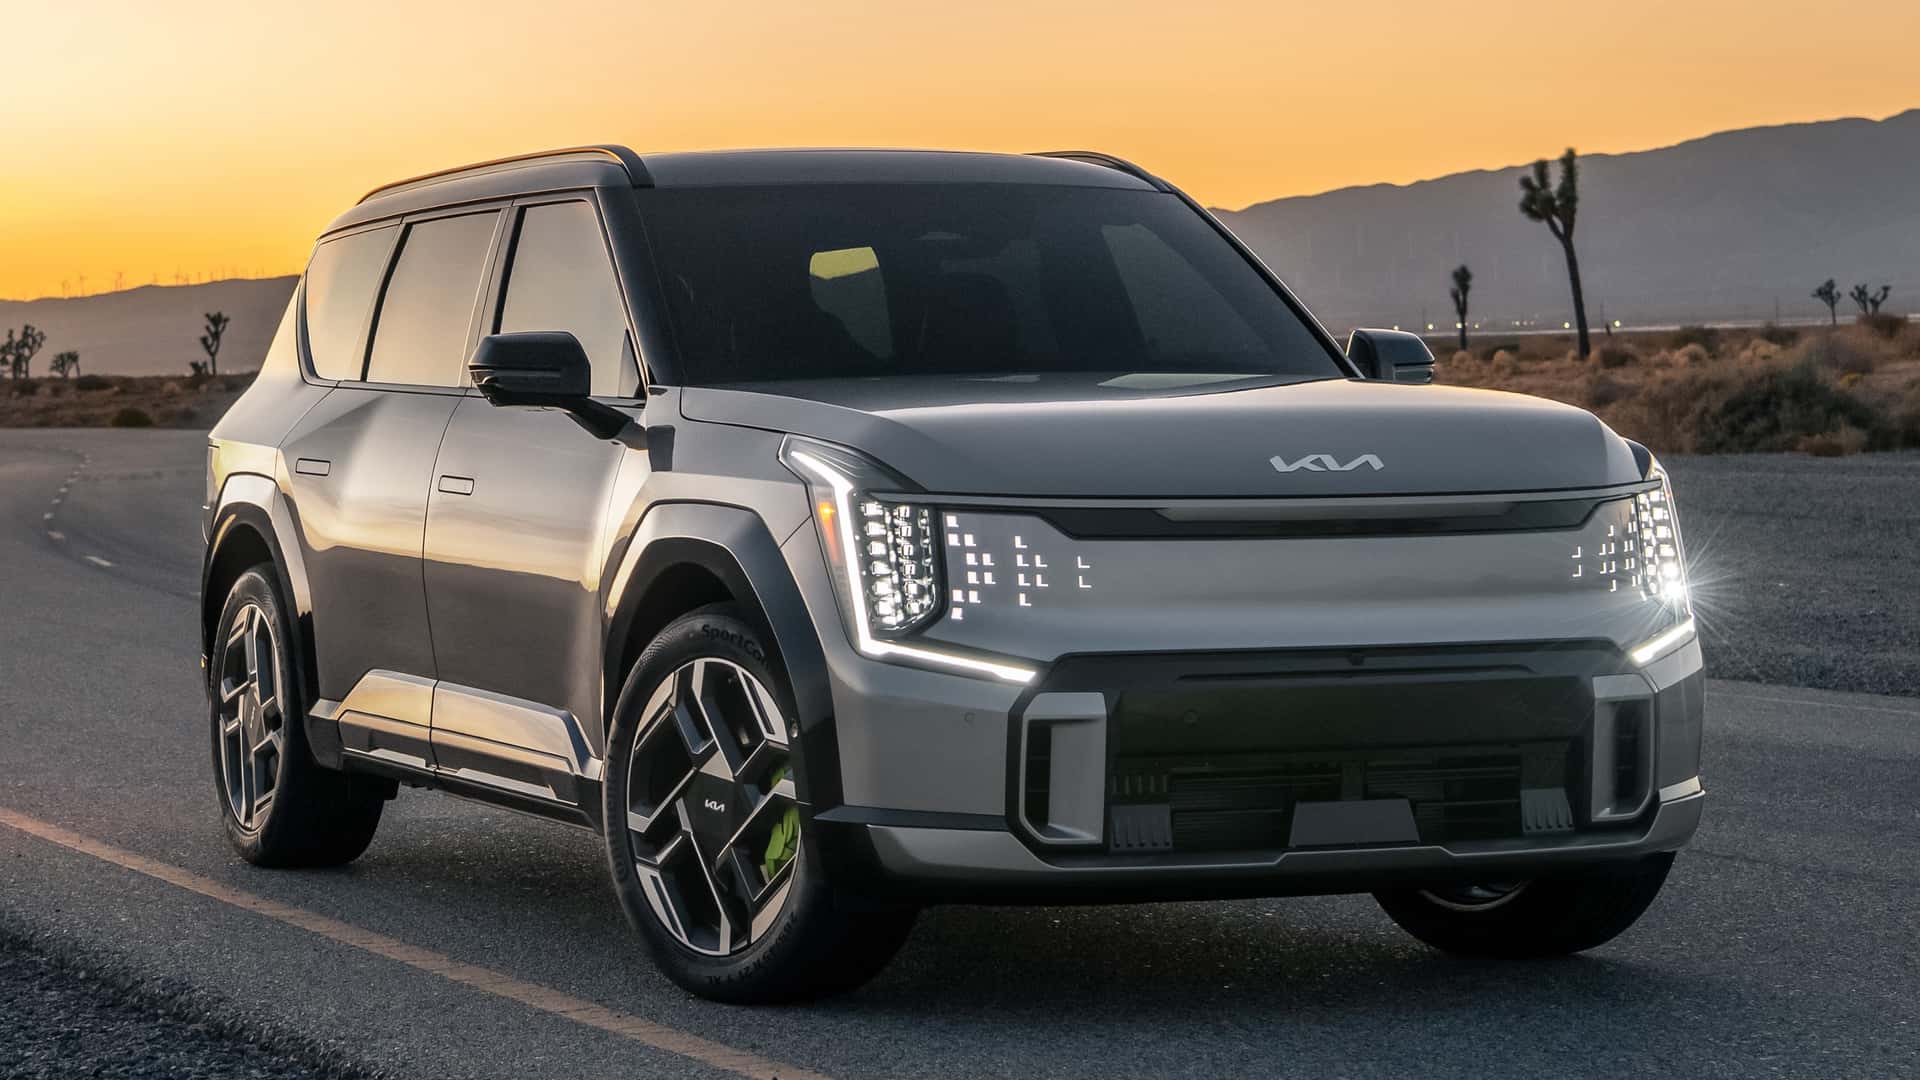
EVs can be especially sensitive to lease incentives because manufacturers sometimes use leasing programs to provide access to incentives that aren’t structured the same way for traditional purchases. Edmunds specifically identifies the EV9 as one of its September 2026 “Hidden Gem” lease offers based on the relationship between advertised payment and MSRP.
Leasing also reduces the amount of long-term resale-value risk a consumer takes on. That doesn’t mean an EV lease is automatically cheaper in total, but it can be attractive to people who prefer not to make a long-term commitment to rapidly changing electric-vehicle technology.
The EV9 therefore represents a different kind of lease opportunity: instead of simply lowering the payment on an inexpensive car, the lease structure can place a relatively expensive electric SUV within a monthly budget below the national average for new-car financing.
10. 2026 Honda Prologue
The 2026 Honda Prologue is another electric SUV that currently illustrates the difference between a vehicle’s sticker price and its lease payment. Edmunds lists a September 2026 lease offer at $471 per month, with $471 due at signing for 36 months. Its listed MSRP is $48,595.
At face value, that puts the Prologue $146 below the $617 average lease payment and nearly $300 below the $765 average new-car loan payment reported for the second quarter of 2026.
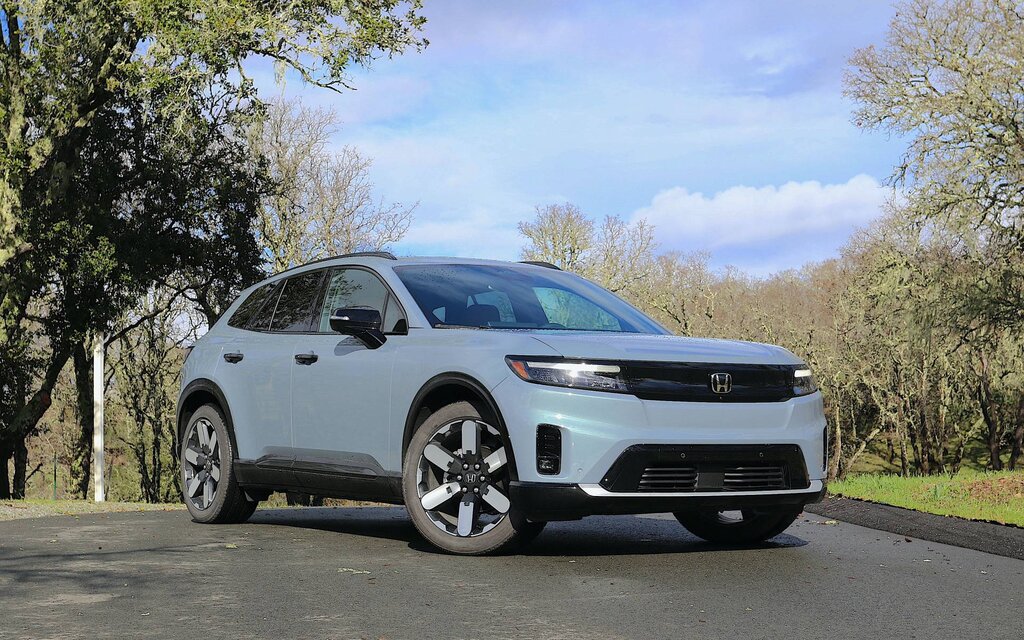
The Prologue’s lease structure may be particularly relevant for shoppers interested in an EV but reluctant to commit to long-term ownership. Electric vehicles continue to develop quickly, and leasing allows drivers to change vehicles after a relatively short contract rather than keeping the same EV through several years of technological changes.
Edmunds identifies the Prologue among its September 2026 lease “Hidden Gems,” comparing advertised payments with vehicle MSRP.
The key caveat is that lease advertisements don’t represent every shopper’s actual offer. Credit requirements, taxes, registration, dealer fees, mileage allowances, and regional incentives can change the final payment.
Still, with only the advertised first payment due at signing in Edmunds’ listing, the Prologue is an example of an EV lease that can sit comfortably below both the average lease benchmark and the average new-car financing payment.
For an EV shopper focused on monthly cash flow, that difference can be meaningful.
11. 2026 Toyota Tacoma
The 2026 Toyota Tacoma proves that the lease advantage isn’t limited to sedans, compact crossovers, and electric vehicles. Edmunds lists a September 2026 lease offer for the Tacoma at $396 per month, with $396 due at signing for a 24-month term. The listed MSRP is $40,508.
Toyota also lists several Tacoma lease programs in September, including a $279-per-month offer for the SR5 with $4,278 due at signing, while other configurations carry higher payments.
That variation demonstrates why shoppers need to pay attention to the exact trim. A $279 payment on an SR5 cannot automatically be applied to a more expensive Tacoma configuration.
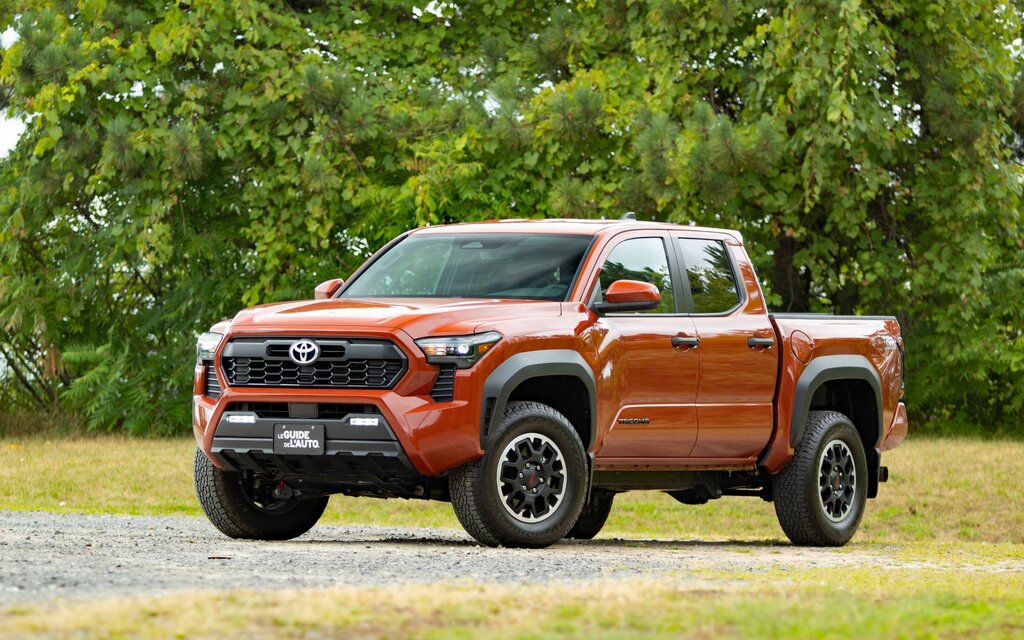
The Tacoma is an especially interesting lease candidate because pickup trucks can become expensive when buyers add options, four-wheel drive, and higher trim levels. A manufacturer-supported lease can reduce the monthly obligation by charging primarily for the vehicle’s expected depreciation during the lease term rather than financing its entire purchase price.
The downside is that truck users need to examine mileage and usage restrictions carefully. Someone who uses a Tacoma for heavy work, high-mileage commuting or frequent towing should scrutinize the lease terms before deciding.
For drivers who want a new midsize pickup for a defined two- or three-year period, however, the current Tacoma offers a clear example of a lease payment that sits substantially below both the $617 lease benchmark and the $765 average new-car loan payment.
The $617 figure is a useful benchmark, but it should not be treated as proof that leasing is always cheaper than buying. Current Experian data puts the average new-vehicle lease payment at about $619 in Q1 2026, while the average new-car loan payment reached $765 in Q2 2026.
The biggest issue is that lease advertisements frequently separate the monthly payment from the amount due at signing. A $229 lease with $3,999 due upfront does not actually cost $229 per month when the complete cash outlay is considered.
For a fair comparison, calculate the total lease payments plus upfront costs and applicable fees, then compare that figure with the total cost of financing, including interest, taxes, down payment, and eventual ownership value.