The global automotive industry reached a new production record in 2025, manufacturing 96.38 million motor vehicles worldwide, according to the International Organization of Motor Vehicle Manufacturers (OICA).
China maintained a commanding lead, while the United States, Japan, and India formed the next tier of major producers. These rankings count vehicles manufactured within each country, including passenger cars and commercial vehicles where reported.
Some national figures cover passenger cars only or specific vehicle categories, so those exceptions are identified rather than treated as directly comparable totals. The latest figures reveal where manufacturing capacity is expanding, where it is slowing, and which countries remain essential to the world’s automotive supply chains.
1. China
2025 production: 34,530,738 motor vehicles
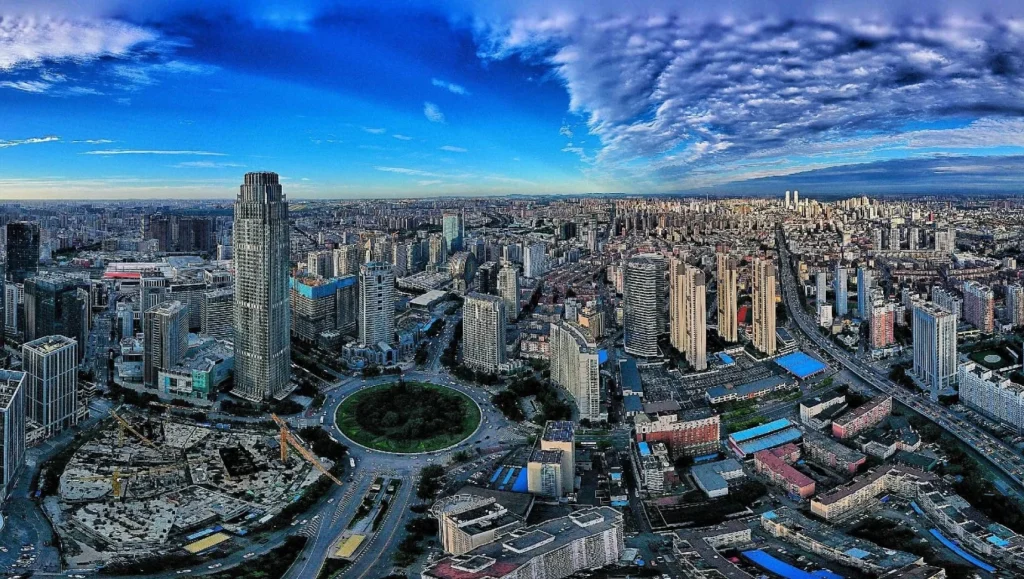
China is the world’s largest automotive manufacturing nation by a substantial margin. OICA recorded 34.53 million vehicles produced in 2025, up approximately 10% from 31.28 million in 2024. That single-country output represents more than one-third of global vehicle production, reflecting the enormous scale of China’s industrial base.
The country manufactures conventional gasoline cars, hybrids, plug-in hybrids, battery-electric vehicles, and commercial vehicles. Domestic companies such as BYD, Geely, Chery, and SAIC compete alongside international automakers operating factories and joint ventures in China.
This combination supports a large manufacturing ecosystem that includes vehicle assembly, batteries, electronics, motors, and other essential components.
Electric vehicles are a particularly important part of China’s growth. OICA reported that Chinese new-energy vehicle production reached approximately 16.63 million units in 2025, an increase of 29%. That category includes more than battery-electric cars alone, so it should not be confused with a count of fully electric vehicles.
China also benefits from substantial domestic demand and an extensive supplier network. Manufacturers can produce at scale while competing aggressively on price, features, and technology.
Exports have become increasingly important, although tariffs and trade restrictions can affect which markets Chinese-built vehicles reach.
The country’s production lead reflects more than cheap manufacturing. It combines industrial capacity, battery supply chains, intense competition, and a large home market. Decisions made by Chinese automakers now influence global vehicle pricing, electrification strategies, and the competitive direction of the automotive industry.
2. United States
2025 production: 10,243,844 motor vehicles
The United States remained the world’s second-largest vehicle producer in 2025, although output declined approximately 3% from the previous year’s 10.52 million units. OICA recorded 10.24 million vehicles manufactured in American factories, including passenger cars, pickups, SUVs, vans, and other commercial vehicles.
The American industry has a distinctive production mix. Full-size pickups and SUVs occupy a major position, reflecting domestic demand for towing capability, passenger space, and versatile cargo capacity.
Ford, General Motors, and Stellantis operate extensive manufacturing networks, while international companies, including Toyota, Honda, Hyundai, BMW, and Mercedes-Benz, also build vehicles in the country.
American factories supply both domestic buyers and overseas markets. The industry depends on a closely integrated North American supply chain, with components and finished vehicles moving between the United States, Mexico, and Canada. Engines, transmissions, batteries, electronics, and other components may cross borders during production.
Electrification is changing investment decisions. Automakers are developing electric vehicles, hybrids, and battery manufacturing capacity, but conventional gasoline-powered vehicles and pickups remain important to American production. Changes in consumer demand, factory schedules, and trade policies can influence annual output.
The 2025 decline does not mean the United States has lost its position as a manufacturing powerhouse. Its production remains far above that of any country except China.
The scale of its domestic market, established supplier base, engineering expertise, and extensive factory network continue to make it a central part of the global automotive industry.
3. Japan
2025 production: 8,410,232 motor vehicles
Japan produced 8.41 million motor vehicles in 2025, an increase of approximately 2% compared with 2024. Its third-place position reflects a mature manufacturing industry that continues to supply vehicles to customers around the world.
Toyota, Honda, Nissan, Suzuki, Mazda, Subaru, and Mitsubishi are among Japan’s major automakers. Their product ranges cover small city cars, family sedans, hybrids, SUVs, sports cars, and commercial vehicles.
Japanese manufacturers also operate extensive overseas production networks, meaning their worldwide brand output is much larger than the number of vehicles assembled within Japan itself.
Hybrid technology remains one of the country’s major strengths. Toyota and other manufacturers have spent years refining powertrains that combine gasoline engines with electric motors.
These systems can reduce fuel consumption without requiring drivers to plug in their vehicles. Japan also produces conventional gasoline vehicles and battery-electric models, so its manufacturing industry is not tied to a single propulsion technology.
The country’s manufacturing reputation is closely associated with production efficiency, quality-control processes, and coordination between automakers and component suppliers. However, those strengths do not mean every model is free from defects or that all Japanese brands share identical reliability records.
Japan faces challenges as global automakers invest heavily in electric vehicles, software, and batteries. Its companies must maintain competitiveness in established hybrid markets while responding to growing demand for fully electric vehicles in several regions.
The 2025 production increase shows that Japan remains an important industrial force. Its future position will depend on how effectively its manufacturers combine established engineering expertise with new technologies and changing international demand.
4. India
2025 production: 6,490,810 motor vehicles
India produced 6.49 million motor vehicles in 2025, an increase of approximately 8% over 2024. The growth strengthened its position as the world’s fourth-largest producer and highlighted the importance of its expanding domestic market.
The country’s manufacturing industry serves a large population with varied transportation needs. Maruti Suzuki has a major presence in passenger cars, while Tata Motors and Mahindra produce cars, SUVs, and commercial vehicles.
Hyundai, Toyota, Kia, and other international companies also manufacture vehicles in India, supporting competition across several price categories.
Small cars have traditionally been important to Indian production because purchase price, fuel economy, and maintenance expenses matter to many households.
Demand for SUVs has also grown, encouraging manufacturers to change their product ranges and invest in new factory capacity. Commercial vehicles remain essential for freight, construction, and infrastructure development.
India is increasingly important as an export base. Locally assembled vehicles and components reach international markets, while the country’s supplier network supports manufacturing programs for global automakers.
Investment in electric vehicles and battery technology is creating additional opportunities, although charging infrastructure and affordable vehicle pricing remain important factors in wider adoption.
Growth is not guaranteed every year. Manufacturers must navigate emissions requirements, financing conditions, supply-chain challenges, and competition from other manufacturing countries. They also need to balance local customer expectations with the requirements of overseas markets.
India’s production performance demonstrates how a large home market and competitive industrial ecosystem can support substantial manufacturing growth. Continued investment in technology, skilled labor, and component production will help determine whether the country can further strengthen its role in global automotive supply chains.
5. Germany
2025 production: 4,148,836 passenger cars
Germany produced approximately 4.15 million passenger cars in 2025, an increase of around 2% compared with 2024. This figure covers passenger cars rather than the full range of motor vehicles, so it is not directly comparable with countries whose totals include commercial vehicles.
The German automotive industry is known for manufacturers such as Volkswagen, BMW, Mercedes-Benz, and Porsche. Their vehicles span mainstream family transportation, premium sedans, luxury SUVs, and performance cars.
The country also has an extensive network of engineering firms and component suppliers involved in powertrain development, safety technology, electronics, and manufacturing equipment.
Germany’s influence extends beyond the vehicles assembled inside its borders. German automakers operate factories in numerous countries, allowing them to serve customers close to major markets. Domestic production nevertheless remains important for engineering-intensive models and vehicles built at established manufacturing sites.
The industry is undergoing a substantial transition. Battery-electric vehicles require different components and production methods from conventional gasoline and diesel vehicles. German companies are investing in new platforms, battery supply arrangements, software, and factory upgrades while competing with manufacturers in China and elsewhere.
High operating costs and international competition are significant challenges. Energy prices, labor expenses, and changing demand can influence where manufacturers allocate future production. The need to fund new technology while maintaining competitive prices adds further pressure.
Germany’s position demonstrates that automotive leadership is not determined by production volume alone.
Engineering capabilities, premium brands, skilled manufacturing workers, and a large supplier network remain important assets. Its ability to maintain that position will depend on adapting its industrial strengths to the rapidly changing global vehicle market.
6. South Korea
2025 production: 4,102,200 motor vehicles
South Korea produced approximately 4.10 million motor vehicles in 2025, a slight decline from its 2024 output of 4.13 million. The country remains one of the world’s major manufacturing centers, supported by globally competitive automakers and expertise in electronics and advanced manufacturing.
Hyundai Motor Group, which includes Hyundai, Kia, and Genesis, is central to the industry’s international presence. Its product range spans compact cars, family SUVs, luxury vehicles, hybrids, and battery-electric models.
South Korean manufacturers sell worldwide and have expanded production outside their home country to serve major markets more directly.
The country’s wider technology sector also supports automotive development. Electronics, batteries, displays, and software are increasingly important as vehicles become more connected and electrified.
Access to these capabilities can help automakers develop new powertrains and vehicle features, although success still depends on cost, quality, and consumer demand.
Exports are a major part of the industry’s business model. South Korean brands compete in the United States, Europe, and other markets, while overseas factories help them manage trade requirements and regional preferences.
Domestic production figures therefore capture only part of the manufacturing activity associated with South Korean automakers.
The industry faces challenges from tariffs, global competition, and the expense of developing new electric-vehicle platforms. Manufacturers must also decide how quickly to expand battery-electric offerings while continuing to supply gasoline and hybrid vehicles.
South Korea’s production total reflects a sophisticated export-oriented industry rather than simply a large domestic assembly base. Its continued competitiveness will depend on manufacturing efficiency, technological investment, and the ability to adapt products to rapidly changing global demand.
7. Mexico
2025 production: 4,092,448 motor vehicles
Mexico produced 4.09 million motor vehicles in 2025, approximately 3% fewer than in 2024. Despite the decline, it remained one of the world’s largest vehicle manufacturing nations and a crucial part of North America’s integrated automotive industry.
The country hosts production facilities operated by General Motors, Ford, Stellantis, Nissan, Volkswagen, Toyota, Honda, and other manufacturers. These plants build passenger cars, SUVs, pickups, and commercial vehicles for domestic customers and export markets.
Mexico also manufactures engines, transmissions, wiring systems, seats, and other components used throughout the regional supply chain.
Its location is a major advantage. The United States is an important destination for vehicles assembled in Mexico, and established road, rail, and border infrastructure supports the movement of components and finished products.
Parts may cross borders several times as they move through different stages of production, making North American manufacturing highly interconnected.
Mexico’s automotive industry benefits from decades of investment, a substantial supplier base, and workers experienced in vehicle assembly.
Manufacturers can allocate different models to different factories according to costs, capacity, and market requirements. However, this integration also exposes the industry to changes in trade policy and economic conditions across North America.
The shift toward electric vehicles presents both opportunities and challenges. New investment can bring battery production and advanced manufacturing, but factories and suppliers must also adapt to changing component requirements. Decisions about future production locations can depend on incentives, trade rules, and the availability of skilled workers.
Mexico’s 2025 output demonstrates its continuing importance despite a year-on-year decline. Its future production will depend on maintaining competitive manufacturing operations and adapting to changes in regional trade and automotive technology.
8. Brazil
2025 production: 2,644,054 motor vehicles
Brazil produced 2.64 million motor vehicles in 2025, an increase of approximately 4% from 2024. As South America’s largest automotive manufacturing country, it serves a substantial domestic market while supplying vehicles to other countries in the region.
Manufacturers including Volkswagen, General Motors, Stellantis, Toyota, Hyundai, and Renault have established operations in Brazil. Their factories produce passenger cars, SUVs, pickups, and commercial vehicles, while local suppliers manufacture components needed for assembly and servicing.
Brazil has a distinctive place in automotive technology because of its long-standing use of ethanol fuel. Many vehicles sold in the country have flex-fuel engines capable of running on gasoline, ethanol, or a blend of the two.
The system developed partly because Brazil has an established sugarcane ethanol industry. It allows manufacturers to tailor powertrains to local fuel availability, although not every vehicle produced in the country uses flex-fuel technology.
The domestic market strongly influences production decisions. Fuel prices, financing costs, taxation, and household purchasing power all affect the types of vehicles buyers can afford. Manufacturers must also respond to demand for SUVs and commercial vehicles while investing in new powertrains.
Brazil has opportunities to expand hybrid and electric-vehicle manufacturing, but the transition involves costs associated with batteries, charging infrastructure, and factory upgrades. Competition from imported vehicles and other production locations can also influence investment decisions.
The country’s production growth in 2025 reflects its continuing industrial importance. Brazil’s automotive sector supports manufacturing jobs, engineering, and component supply chains, while its fuel technology demonstrates how local resources can shape vehicle development in ways that differ from other major automotive markets.
9. Spain
2025 production: 2,274,026 vehicles reported in OICA’s country table
Spain produced approximately 2.27 million vehicles in 2025, a decline of around 4% from 2024. Its manufacturing industry is closely connected to the wider European market, with factories supplying vehicles to customers across the continent and beyond.
Spanish production includes passenger cars, SUVs, vans, and other vehicles assembled by manufacturers such as SEAT, Volkswagen, Stellantis, Renault, and Ford. The country benefits from established supplier networks, skilled industrial workers, and road, rail, and port infrastructure that supports vehicle exports.
Spain’s place in the industry depends heavily on international demand. Many vehicles built in its factories are intended for markets outside Spain, so production levels can change with consumer preferences and sales conditions elsewhere in Europe. A shift toward one body style or powertrain can affect factory schedules and supplier orders.
Electrification is an important issue for the country’s automotive future. Manufacturers need to adapt assembly lines, component sourcing, and production processes as electric and hybrid vehicles become more prominent.
Investment in battery supply chains and modern manufacturing equipment can help Spain retain production programs, but factories must compete with other European locations and lower-cost manufacturing regions.
The country also faces pressure from operating costs, changes in vehicle demand, and the expense of developing new technologies. These factors make long-term investment decisions particularly important for manufacturers and suppliers.
Spain’s production total shows why its role extends beyond the domestic market. It remains a significant manufacturing base within Europe’s integrated automotive industry. Maintaining that position will require continued investment, efficient factories, and the ability to build vehicles that match changing European and international demand.
10. France
2025 production: 1,463,991 cars and light commercial vehicles
France rounds out this ranking with approximately 1.46 million cars and light commercial vehicles produced in 2025, an increase of around 8% compared with 2024. This figure covers cars and light commercial vehicles rather than every category of motor vehicle, so it should be interpreted according to that narrower reporting scope.
France has a long automotive manufacturing history, with major domestic companies including Renault and Stellantis, the group that owns brands such as Peugeot and Citroën. Factories in the country produce passenger cars and commercial vehicles, while French automakers also manufacture extensively in other countries.
The industry has traditionally served buyers looking for compact cars, family hatchbacks, sedans, and practical commercial vans. These vehicles are relevant to European cities and businesses where maneuverability, fuel consumption, and operating costs matter.
French manufacturers have also invested in electric vehicles, reflecting European emissions rules and changing demand for lower-emission transportation.
France’s automotive sector operates within a competitive European market. Manufacturers must manage labor and energy costs, meet changing regulatory requirements, and compete with vehicles built elsewhere in Europe and Asia.
The transition to electric powertrains adds pressure to update factories and secure access to batteries and electronic components.
The country’s production increase in 2025 is encouraging, but one year of growth does not establish a long-term recovery. Future output will depend on new model launches, export demand, factory investment, and the competitiveness of vehicles assembled in France.
France’s position demonstrates that a country can remain relevant to automotive manufacturing even when its output is far below that of the largest global producers.
Its engineering heritage, established brands, and industrial infrastructure continue to support vehicle production, while investment in new technology will help determine its role in the next phase of the automotive industry.