Car insurance premiums do not always increase because of accidents or traffic violations. Several everyday factors can quietly affect how much you pay for coverage. From changes in your driving habits to vehicle modifications and insurance claim history, small details can influence the final premium.
Many drivers overlook these factors because they do not seem directly connected to insurance costs. However, understanding what affects your policy can help you make better decisions, avoid unnecessary expenses, and maintain affordable coverage.
Knowing these nine hidden factors can help you identify potential premium increases and take practical steps to manage your car insurance costs.
1. Frequent Insurance Claims
Your insurance claim history plays an important role in determining your premium. Insurance companies review previous claims to understand how frequently you have needed financial assistance for vehicle-related damage.
A history of repeated claims may suggest a higher likelihood of future claims, which can influence the amount you pay for coverage.
Even relatively small claims can affect your insurance profile. For example, filing multiple claims for minor scratches, broken mirrors, or small dents may make you appear riskier to an insurer than someone who handles minor repairs independently.
The type of claim also matters. Claims involving major accidents, significant property damage, or injuries may have a greater influence on your insurance assessment. Insurers consider the nature and circumstances of previous incidents when evaluating potential risks.
Drivers sometimes assume that using insurance whenever possible is always the best financial decision. However, filing a claim for every minor repair may not be beneficial in the long run, particularly when the repair cost is close to the policy deductible or excess.
Before submitting a claim, compare the estimated repair expense with the amount you would need to pay out of pocket. This simple calculation can help you decide whether making a claim is financially worthwhile.
Your claims history may also affect your eligibility for certain discounts. Depending on your insurer and location, maintaining a claim-free record could qualify you for a no-claim bonus or other savings.
It is important to understand that not every claim automatically results in a higher premium. Some policies offer claim protection features, while local regulations and insurer-specific rules influence how claims are assessed.
Reviewing your policy regularly and understanding its claim conditions can help you avoid unnecessary expenses. Responsible claim decisions may support more affordable coverage over time.
2. Changes in Your Driving Habits
Your driving habits can quietly influence your car insurance premium. Insurance companies often consider how frequently, how far, and under what conditions you drive when assessing the potential risk associated with your vehicle.
Drivers who spend several hours on the road every day may face greater exposure to accidents than those who drive occasionally. Longer driving distances generally mean more opportunities for unexpected traffic situations, road hazards, and vehicle-related incidents.
Your daily commute can also make a difference. Driving through congested city streets, busy intersections, and crowded commercial areas may increase exposure to minor collisions and traffic-related damage.
Night driving can influence risk assessments as well. Reduced visibility, driver fatigue, and unpredictable road conditions can make certain journeys more challenging, particularly on poorly illuminated roads.
Frequent long-distance travel may also affect your premium, depending on the insurer’s pricing model. Vehicles used regularly for business purposes can have different insurance requirements from those used exclusively for personal transportation.
Some drivers change their routines without informing their insurance providers. For example, someone who starts using their personal car for daily business deliveries may unknowingly create a difference between their actual vehicle usage and the information recorded on their policy.
Providing accurate information about your driving habits is essential. Incorrect details may create complications when you need to make a claim, especially if the vehicle was being used for a purpose not covered by the policy.
Review your estimated annual mileage and vehicle usage whenever your circumstances change. Keeping your insurance information updated helps ensure that your coverage reflects how you actually use your car.
3. Your Residential Location
Where you live can have a noticeable effect on your car insurance premium. Insurance companies evaluate location-based risks because vehicles parked and driven in different areas face different levels of exposure to accidents, theft, vandalism, and environmental damage.
Urban areas often have heavier traffic and more crowded parking conditions. These factors can increase the likelihood of minor accidents, scratches, and damage caused by other vehicles.
Areas with higher vehicle theft rates may also attract higher insurance costs. Insurers consider historical theft patterns when estimating the financial risk associated with covering cars in particular locations.
Weather conditions are another important consideration. Regions frequently affected by flooding, hailstorms, cyclones, or severe rainfall may present additional risks to insured vehicles.
Your parking arrangements can influence insurance assessments too. A vehicle kept inside a secure garage may face a different level of theft or damage risk compared with one regularly parked on an exposed roadside.
Moving to a new neighbourhood can therefore affect your premium, even when your vehicle and driving habits remain unchanged. The difference depends on the risk profile of your new residential area.
It is important to update your insurer when you permanently change your address. Using outdated residential information may create problems during policy verification and claim processing.
If you are planning to relocate, consider checking insurance costs before making the move. Understanding location-related pricing can help you prepare for possible changes in your vehicle ownership expenses.
4. Your Vehicle’s Make, Model, and Age
The type of car you own is a major factor in determining your insurance premium. Insurers assess vehicles based on their market value, repair costs, safety features, theft statistics, and the availability of replacement parts.
Luxury vehicles often cost more to insure because their components can be expensive to repair or replace. Advanced electronics, specialised materials, and premium exterior features may increase repair bills following an accident.
The vehicle’s popularity can also influence insurance risk. Certain models are more frequently targeted by thieves, which may result in higher premiums for comprehensive coverage in some markets.
Older vehicles are not necessarily cheaper to insure. While their market value may be lower, discontinued parts and limited availability of replacement components can make repairs expensive.
Modern vehicles also contain sophisticated technology that can increase repair costs. Cameras, sensors, driver assistance systems, and electronic control units may require specialised equipment and trained technicians.
Safety ratings can influence pricing as well. Vehicles equipped with effective safety systems may receive more favourable insurance assessments, depending on the insurer and the available data.
Before purchasing a car, consider its insurance expenses alongside the purchase price, fuel efficiency, maintenance requirements, and resale value. A vehicle that appears affordable initially may have relatively high insurance costs.
Comparing insurance quotations for different models can help you make a more informed purchasing decision. This approach allows you to understand the financial impact of vehicle ownership before committing to a purchase.
5. Installing Aftermarket Modifications
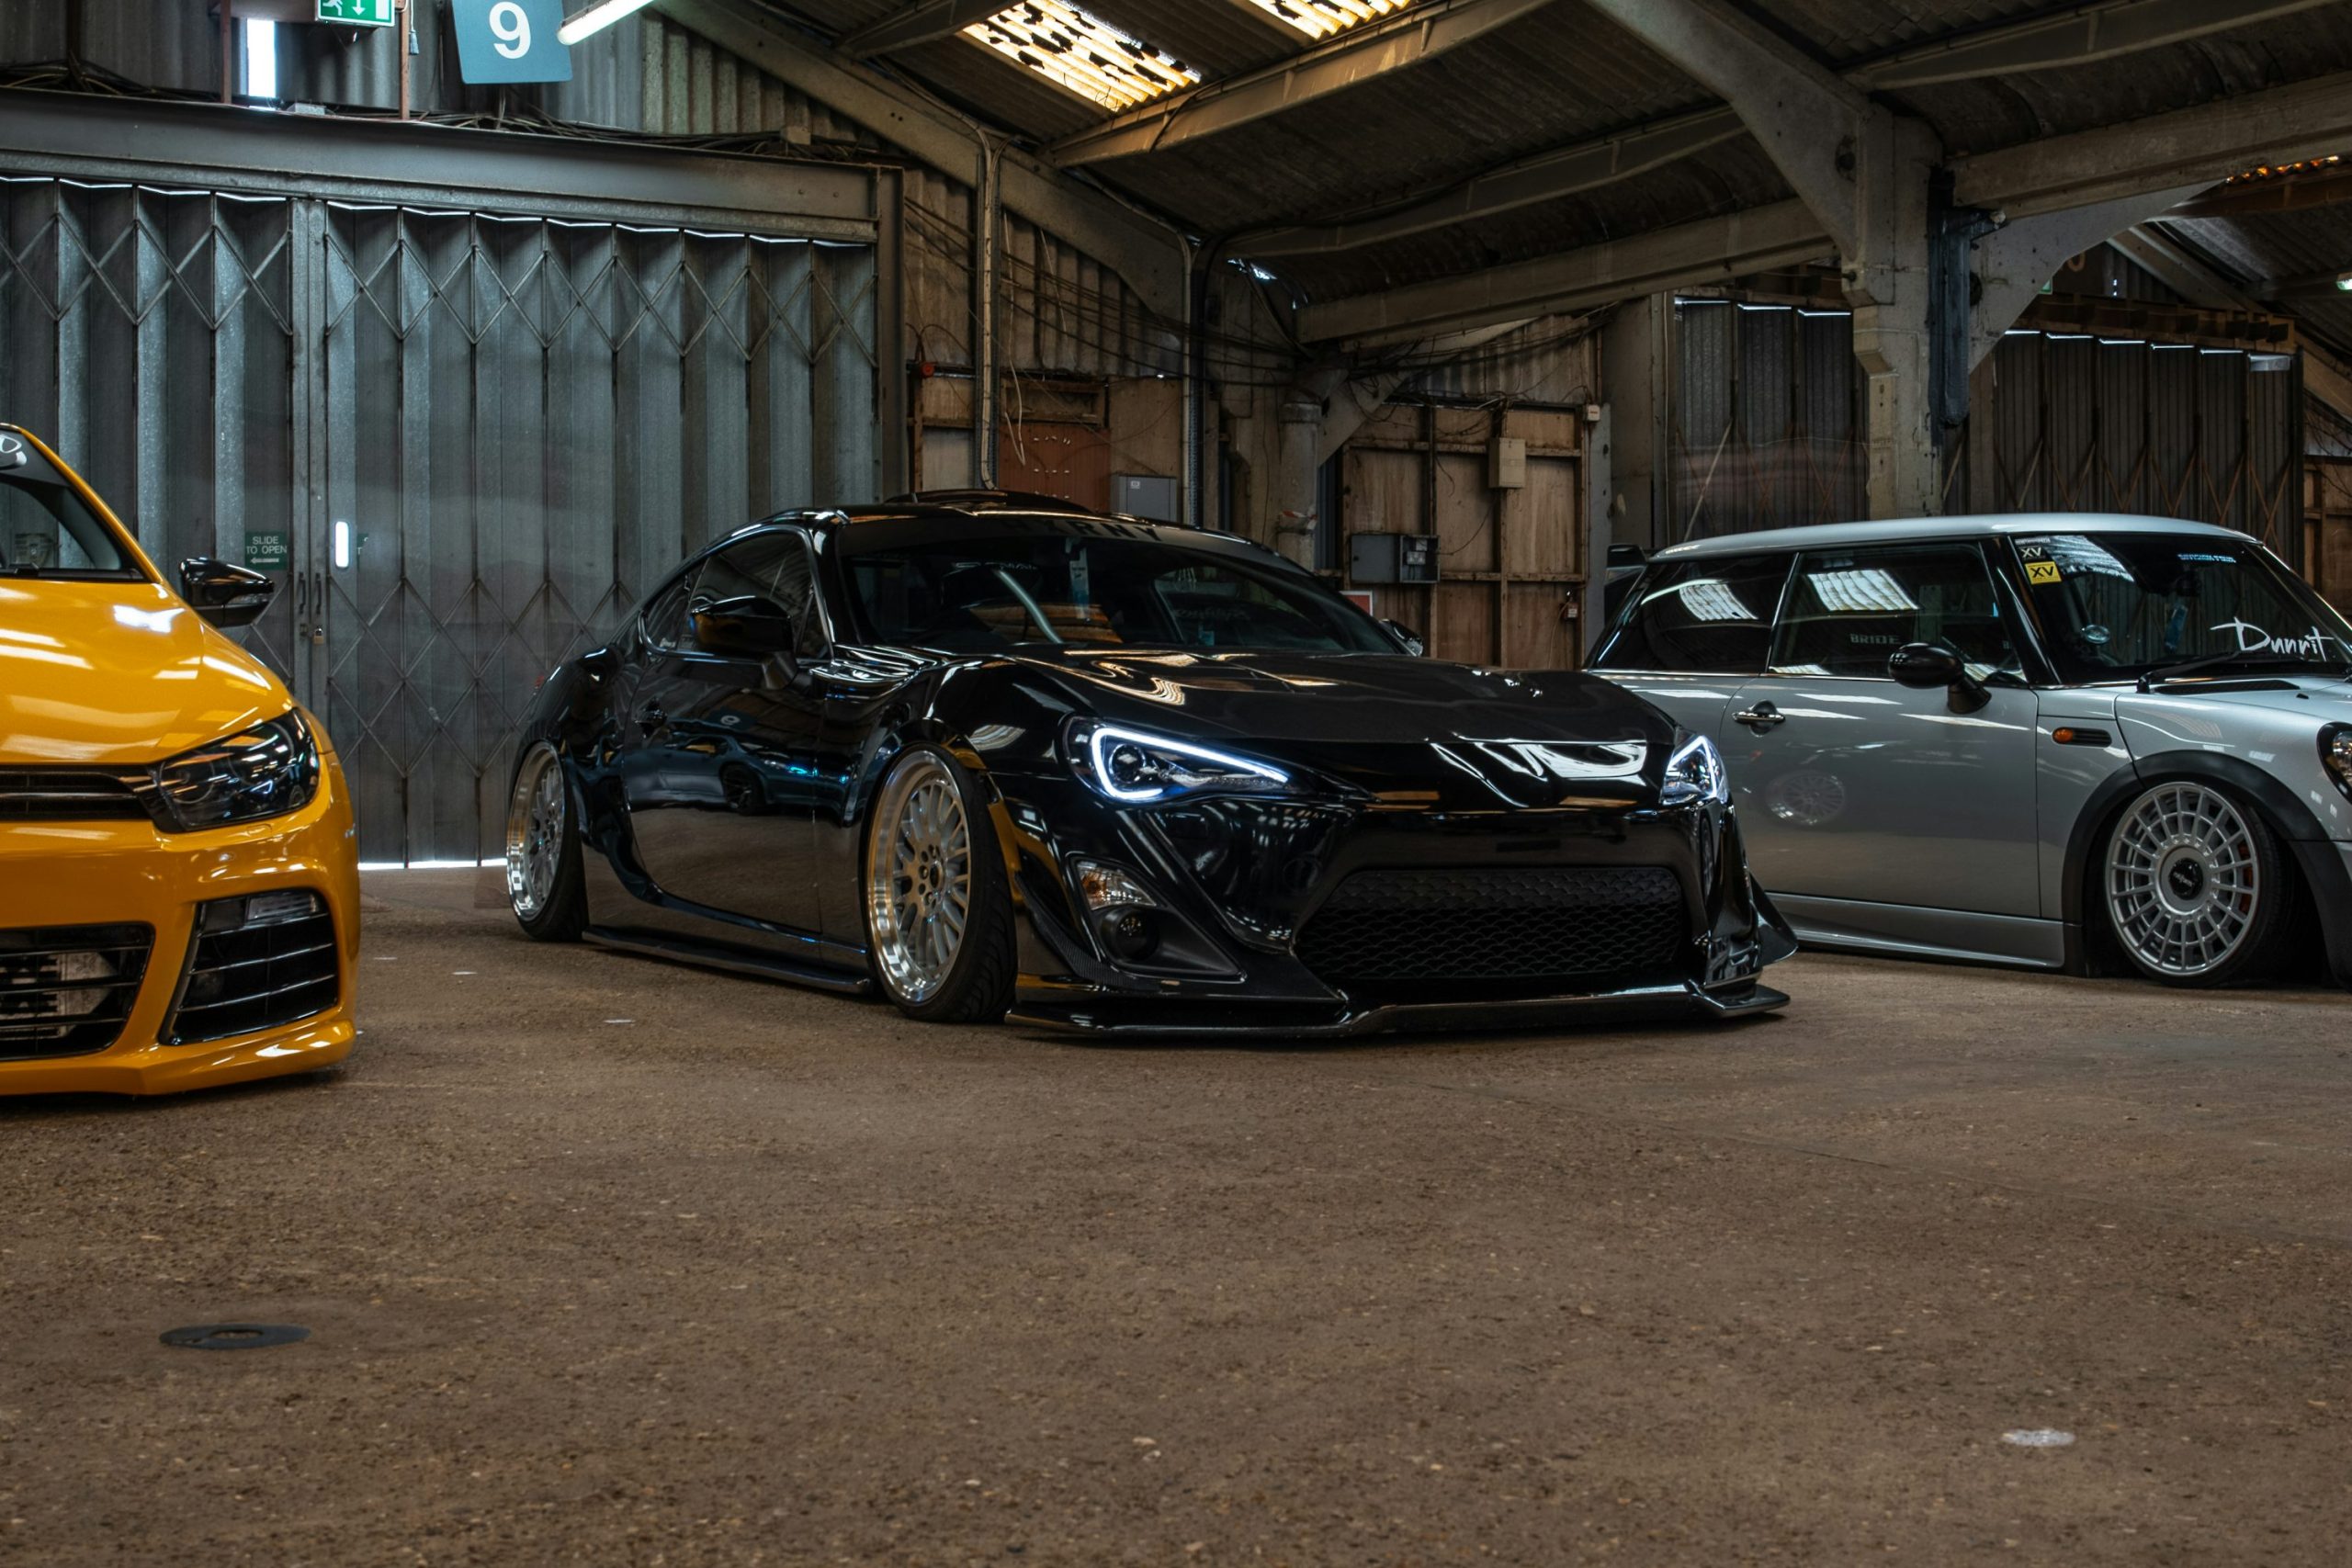
Vehicle modifications can change your insurance premium without you immediately noticing. Even modifications intended to improve appearance, performance, or convenience may affect how an insurer evaluates your vehicle.
Performance upgrades are particularly important. Engine tuning, turbocharger installations, and changes to suspension systems can alter a vehicle’s performance characteristics, potentially increasing the perceived risk of accidents or mechanical problems.
Exterior modifications may also affect coverage. Custom body kits, specialised paintwork, aftermarket bumpers, and expensive alloy wheels can increase the cost of repairing or replacing the vehicle.
Interior upgrades are not always exempt from insurance considerations. Premium sound systems, customised seating, entertainment screens, and additional electronic equipment may increase the total value of the vehicle.
Some modifications can also affect vehicle safety. Changes to braking systems, lighting arrangements, suspension components, or structural elements may create concerns if they do not meet applicable safety standards.
Insurers generally require policyholders to disclose modifications that affect the vehicle’s condition or value. Failing to provide accurate information may lead to coverage disputes or claim complications.
Not every modification automatically increases premiums. Certain security improvements, such as approved anti-theft devices, may qualify for discounts or more favourable insurance terms.
Before installing aftermarket accessories, contact your insurance provider and ask whether the changes need to be declared. This can help you avoid unexpected costs and ensure that your modified vehicle remains appropriately insured.
6. A Poor Credit-Based Insurance Score
In some countries, insurance companies use credit-related information as part of their premium calculations. This practice is more common in certain insurance markets, particularly in the United States, where insurers may use credit-based insurance scores to estimate potential claim risk.
These scores are different from ordinary credit scores. They generally use selected credit-related information to help insurers evaluate statistical risk rather than directly measure a person’s driving ability.
Factors such as payment history, outstanding debt, credit account activity, and the length of credit history may contribute to credit-based assessments, depending on the scoring model.
A lower credit-based insurance score may result in higher premiums in locations where this pricing method is permitted. However, the relationship between credit information and insurance costs varies between companies and jurisdictions.
It is important to recognise that this practice is not universal. Many countries restrict or prohibit insurers from using personal credit information when determining vehicle insurance premiums.
For example, drivers in India generally do not face the same credit-based insurance pricing structure commonly found in parts of the United States. Indian motor insurance premiums are influenced by factors such as vehicle characteristics, insured declared value, applicable regulations, add-on covers, and insurer-specific pricing.
If your insurer operates in a market where credit information affects premiums, reviewing your credit reports and correcting inaccurate entries may help improve your financial profile.
Maintaining responsible financial habits can also support better access to financial products. However, drivers should check their local insurance regulations before assuming that credit improvements will reduce their car insurance expenses.
7. Adding a Young or Inexperienced Driver to Your Policy
Adding another driver to your insurance policy can increase the premium, particularly when that person has limited driving experience. Insurance companies consider the experience and risk profile of everyone covered under a policy when calculating potential costs.
Young drivers often face higher insurance rates because they generally have less experience identifying road hazards, responding to emergencies, and managing challenging traffic conditions.
A newly licensed driver may also have a limited driving record. Without an established history of safe driving, insurers may have less information to assess their risk accurately.
Adding a teenager or inexperienced family member to a vehicle policy can therefore increase the total insurance cost. The impact depends on the driver’s age, experience, location, vehicle type, and insurer requirements.
The vehicle itself also matters. An inexperienced driver using a powerful sports car or an expensive vehicle may face different insurance costs from someone driving a smaller car with standard safety features.
Some insurers offer discounts or special programmes for young drivers who complete approved defensive driving courses. These programmes can help develop safer driving habits while potentially reducing insurance expenses.
It is essential to list regular drivers accurately. Allowing someone to drive your car frequently without properly disclosing their usage may create complications when submitting a claim.
Before adding a new driver, discuss available coverage options with your insurer. Understanding the premium difference can help your household make an informed decision without compromising necessary protection.
8. Gaps in Your Insurance Coverage
Allowing your car insurance policy to expire without arranging replacement coverage can create financial and administrative problems. A lapse in insurance may influence the premium you receive when purchasing a new policy, depending on your location and insurer.
Insurance companies may view a coverage gap as a sign of increased risk, particularly when they cannot verify continuous insurance history. However, the effect varies between insurance markets and individual providers.
In some countries, maintaining continuous coverage can help drivers qualify for preferred rates or specific discounts. Losing that history may affect eligibility when applying for a new policy.
An expired policy can also leave you financially exposed. If your vehicle is involved in an accident during an uninsured period, you may have to pay for repairs and other covered losses yourself.
In India, third-party motor insurance is legally mandatory for vehicles used on public roads. Driving without the required insurance can result in penalties under applicable motor vehicle laws.
A lapse can also create problems with no-claim bonuses. Depending on the applicable rules and insurer conditions, failing to renew within the permitted period may result in losing an accumulated benefit.
The easiest way to avoid these issues is to renew your insurance before its expiry date. Setting calendar reminders and enabling renewal notifications can help prevent accidental gaps in coverage.
If your policy has already expired, contact an insurer to understand the available renewal or new-policy options. Avoid driving until the required insurance coverage is active.
9. Not Reviewing Your Policy Regularly
Many car owners purchase insurance once and continue renewing the same policy without reviewing its terms. This habit can quietly increase expenses because insurance needs, vehicle values, and available coverage options change over time.
Your car may lose market value as it gets older. If your insured declared value remains higher than necessary or your coverage no longer matches your vehicle’s current worth, you may end up paying for protection that does not provide the expected financial benefit.
Add-on covers can also increase your premium. Features such as zero depreciation, roadside assistance, engine protection, return-to-invoice coverage, and consumables protection can be useful, but not every driver needs every option.
Some policyholders continue paying for add-ons that no longer match their requirements. Reviewing these features during renewal can help identify unnecessary expenses without sacrificing important protection.
Insurance providers may also revise their pricing, discounts, and policy conditions. Staying with the same insurer for several years does not automatically guarantee the most competitive premium.
Comparing quotations from different insurers can help you identify better pricing and coverage combinations. However, the cheapest policy is not necessarily the best choice if it offers limited protection or restrictive claim conditions.
Pay attention to important details such as deductibles, exclusions, claim settlement procedures, network garages, and policy limits. These terms can make a significant difference when you need financial assistance after an accident.
Reviewing your policy at least once a year is a practical way to keep your coverage relevant. A few minutes spent comparing options can help you avoid unnecessary spending and make better insurance decisions.