Buying a car can make everyday travel easier, but monthly loan payments can put pressure on your budget. Rising living costs, unexpected expenses, and changing financial priorities may leave you looking for ways to reduce what you pay each month.
The good news is that several practical options can help make your car loan more affordable. Whether you recently purchased a vehicle or have been making payments for several years, reviewing your loan terms and financial situation can reveal opportunities for savings.
Understanding your choices can help you lower monthly expenses without creating unnecessary financial problems in the future.
1. Refinance Your Existing Car Loan
Refinancing your current auto loan can be an effective way to reduce your monthly car payment. This process involves replacing your existing loan with a new loan that has different terms.
If your credit score has improved since you purchased your vehicle, you may qualify for a lower interest rate. A reduced rate can decrease the amount of interest you pay throughout the repayment period.
Start by reviewing your current loan agreement. Check the remaining balance, interest rate, monthly payment, and number of payments left.
These details will help you compare your existing loan with available refinancing offers. Having accurate information makes it easier to determine whether refinancing could provide meaningful savings.
Contact several banks, credit unions, and online lenders to compare their refinancing options. Different lenders have different eligibility requirements, interest rates, and repayment terms.
Requesting multiple quotes can help you identify an offer that fits your financial situation. Pay attention to the annual percentage rate rather than focusing only on the advertised monthly payment.
Your credit history plays an important role in refinancing approval. Lenders generally consider your payment history, outstanding debts, income, and credit score when evaluating applications. Making regular payments on existing accounts and correcting errors on your credit report may improve your chances of qualifying for better financing terms.
Before accepting a new loan, review its fees and conditions. Some lenders charge application, processing, or title-related fees. Your current loan may also include an early repayment penalty, depending on the agreement and applicable laws. These expenses can reduce the financial benefits of refinancing.
It is also important to consider how much longer you will be making payments. A refinancing offer with a lower monthly installment may extend your repayment period.
This can increase the total interest paid, even when the monthly amount becomes more manageable. Compare the complete repayment cost before making a decision.
Refinancing works best when the new loan offers a genuinely better financial arrangement. A lower interest rate, reasonable fees, and a suitable repayment period can make a noticeable difference to your monthly budget. Avoid choosing an offer simply because it advertises the smallest payment.
2. Extend Your Car Loan Term
Extending your car loan term can reduce the amount you need to pay each month. A loan term refers to the length of time you have to repay borrowed money. For example, changing a loan from 48 months to 60 months spreads the remaining balance across a longer period. This can make monthly installments smaller.
The main benefit of a longer repayment period is improved monthly cash flow. If your current payment takes up a large portion of your income, reducing it may help you manage rent, groceries, insurance, and other essential expenses.
This approach can provide temporary financial relief when your budget becomes difficult to manage.
You can ask your existing lender whether changing the repayment schedule is possible. Some financial institutions allow borrowers to modify loan terms through refinancing or loan restructuring. The approval process depends on your payment history, outstanding balance, income, and the lender’s policies.
Before extending your loan, calculate the total interest you may pay. A longer repayment period usually means more interest charges because the outstanding balance remains unpaid for a greater amount of time. A lower monthly payment does not automatically mean a cheaper loan.
Consider your vehicle’s age and expected condition as well. Cars lose value over time, and a longer loan can increase the possibility of owing more than the vehicle is worth. This situation is commonly called negative equity. It can create financial difficulties if you need to sell or replace your vehicle before the loan is fully repaid.
Check whether the lender offers flexible repayment arrangements. Some agreements allow additional payments toward the principal balance without penalties. This can help you reduce interest costs when your financial circumstances improve.
Avoid extending the loan simply to make an expensive vehicle appear affordable. If the payment remains too high even after restructuring, reviewing your transportation needs and considering a less expensive vehicle may be a better financial decision.
3. Make a Larger Down Payment When Possible
A larger down payment can reduce the amount you need to borrow when purchasing a vehicle. Since your loan balance starts at a lower amount, your monthly payments may also decrease.
This approach is particularly useful for people who are planning to purchase a car rather than those who already have an established loan.
For example, imagine purchasing a vehicle worth $25,000. If you make a down payment of $5,000, you only need to finance the remaining $20,000, excluding applicable taxes and fees. A smaller financed amount generally results in lower monthly payments when the interest rate and loan term remain unchanged.
Saving for a larger down payment requires planning. You can begin by setting aside a fixed amount from each paycheck. Reducing unnecessary subscriptions, limiting impulse purchases, and preparing meals at home may help you build savings more consistently.
Selling unused household items can also provide additional money for your down payment. Electronics, furniture, clothing, and recreational equipment may have resale value. Putting these earnings toward your vehicle purchase can reduce the amount you need to finance.
Your current vehicle may also contribute to the down payment through a trade-in. However, compare the dealer’s offer with the estimated private sale value.
A dealership may offer convenience, while a private sale could provide a higher amount depending on the vehicle’s condition and local demand.
Avoid using your entire savings account to make a larger down payment. Keeping an emergency fund is important because vehicle ownership can involve unexpected repair costs, medical expenses, and other financial emergencies. Maintaining some accessible savings can prevent future borrowing.
4. Negotiate a Lower Interest Rate
Your interest rate has a direct effect on how much you pay for your vehicle over time. Even a small reduction can make a difference to the monthly installment, particularly when the loan balance is substantial. Reviewing your financing agreement and asking for better terms may help you reduce borrowing costs.
Start by checking your current interest rate. Compare it with rates offered by banks, credit unions, and other reputable lenders. Your credit profile, income, loan amount, repayment history, and vehicle details may affect the offers available to you.
If you have consistently made payments on time, contact your lender and ask whether a lower rate is available. A strong repayment record may support your request, particularly if your financial profile has improved since the original loan approval.
You can also obtain competing loan offers before contacting your current lender. Showing that another institution is willing to provide more favorable terms may encourage your lender to review your account. However, lenders are not required to change an existing interest rate.
Improving your credit score can help you qualify for better financing terms in the future. Pay your bills on time, reduce revolving credit balances, and avoid unnecessary credit applications. Check your credit report for inaccurate information that could negatively affect your score.
When comparing interest rates, look at the annual percentage rate, loan fees, and repayment conditions. A loan with a slightly lower advertised interest rate may include additional charges that make it more expensive. Reviewing the complete agreement helps you avoid misleading comparisons.
5. Trade in Your Current Car for a More Affordable Vehicle
If your current car payment is taking up too much of your monthly income, replacing your vehicle with a less expensive model may be worth considering.
A smaller loan balance can significantly reduce your monthly financial commitment. This option may be especially helpful if you purchased a vehicle that no longer fits your budget.
Start by determining your car’s current market value. You can review vehicle valuation websites, dealership estimates, and local listings for similar models. Consider the mileage, maintenance history, accident records, and condition when estimating its selling price.
Next, find out how much you still owe on your existing loan. Contact your lender or review your latest statement to obtain the payoff amount.
Comparing the vehicle’s estimated value with the outstanding balance will help you understand whether selling or trading it makes financial sense.
If your vehicle is worth more than the remaining loan balance, the difference may be used toward your next purchase. For example, if your car sells for $18,000 and you owe $12,000, you may have approximately $6,000 in equity before transaction expenses.
However, if you owe more than your vehicle is worth, you have negative equity. Trading in the car may require you to pay the difference or include it in your next loan, subject to lender approval. Rolling negative equity into a new loan can increase borrowing costs and create further financial pressure.
6. Remove Unnecessary Add-Ons From Your Loan
When purchasing a vehicle, dealerships may offer additional products such as extended warranties, protection packages, service plans, and other optional features. These products can increase the total amount financed. If they are included in your loan, you may also pay interest on their cost.
Review your original purchase agreement to identify all additional products and services.
Look for charges related to maintenance packages, paint protection, fabric protection, extended service contracts, and other optional items. Understanding what you purchased is the first step toward identifying potential savings.
Some add-ons may provide genuine value, depending on your driving habits, vehicle age, and expected repair expenses.
For example, an extended warranty may be useful for certain vehicles with expensive repair components. However, its value depends on coverage limitations, exclusions, deductibles, and the price paid.
Contact the dealership or service provider to ask about cancellation options. Some optional products allow cancellation within a specified period. Others may provide partial refunds based on the remaining coverage period or usage. Read the contract carefully before submitting a cancellation request.
If a refund is approved, it may be applied toward your outstanding loan balance rather than provided directly to you. This can reduce the principal amount owed, which may lower future interest costs. However, your monthly payment will not necessarily change automatically.
Ask your lender whether the reduced balance can result in a payment recalculation or loan modification. In many cases, the original monthly installment remains unchanged, but you may finish repaying the loan earlier. Understanding this distinction can help you set realistic expectations.
7. Ask Your Lender About Payment Assistance Programs
Financial difficulties can happen unexpectedly. A job change, reduced income, medical expenses, or family responsibilities may make it harder to maintain your regular car payments.
If you are struggling financially, contacting your lender early can help you understand available assistance options.
Many lenders have hardship programs designed to support borrowers facing temporary financial difficulties. Depending on the institution and loan agreement, these programs may include payment extensions, deferred installments, modified repayment schedules, or temporary reductions in payment amounts.
A payment extension allows you to postpone a scheduled installment for an agreed period. This can provide short-term relief when you need additional time to manage essential expenses.
However, interest may continue accumulating during the extension, increasing the total amount you eventually repay.
Payment deferral works differently depending on the lender. Some institutions move missed installments to the end of the loan term, while others adjust the repayment schedule. Always request a written explanation of how deferred payments will affect your loan balance and final repayment date.
Prepare your financial information before contacting the lender. Be ready to explain your current circumstances, monthly income, essential expenses, and the amount you can realistically afford. Clear information can help the lender evaluate suitable assistance arrangements.
Do not wait until you have missed several payments before requesting help. Late payments can result in additional fees, credit score damage, and further financial complications.
Contacting the lender early demonstrates that you are trying to manage the obligation responsibly.
8. Make Extra Payments Toward the Principal Balance
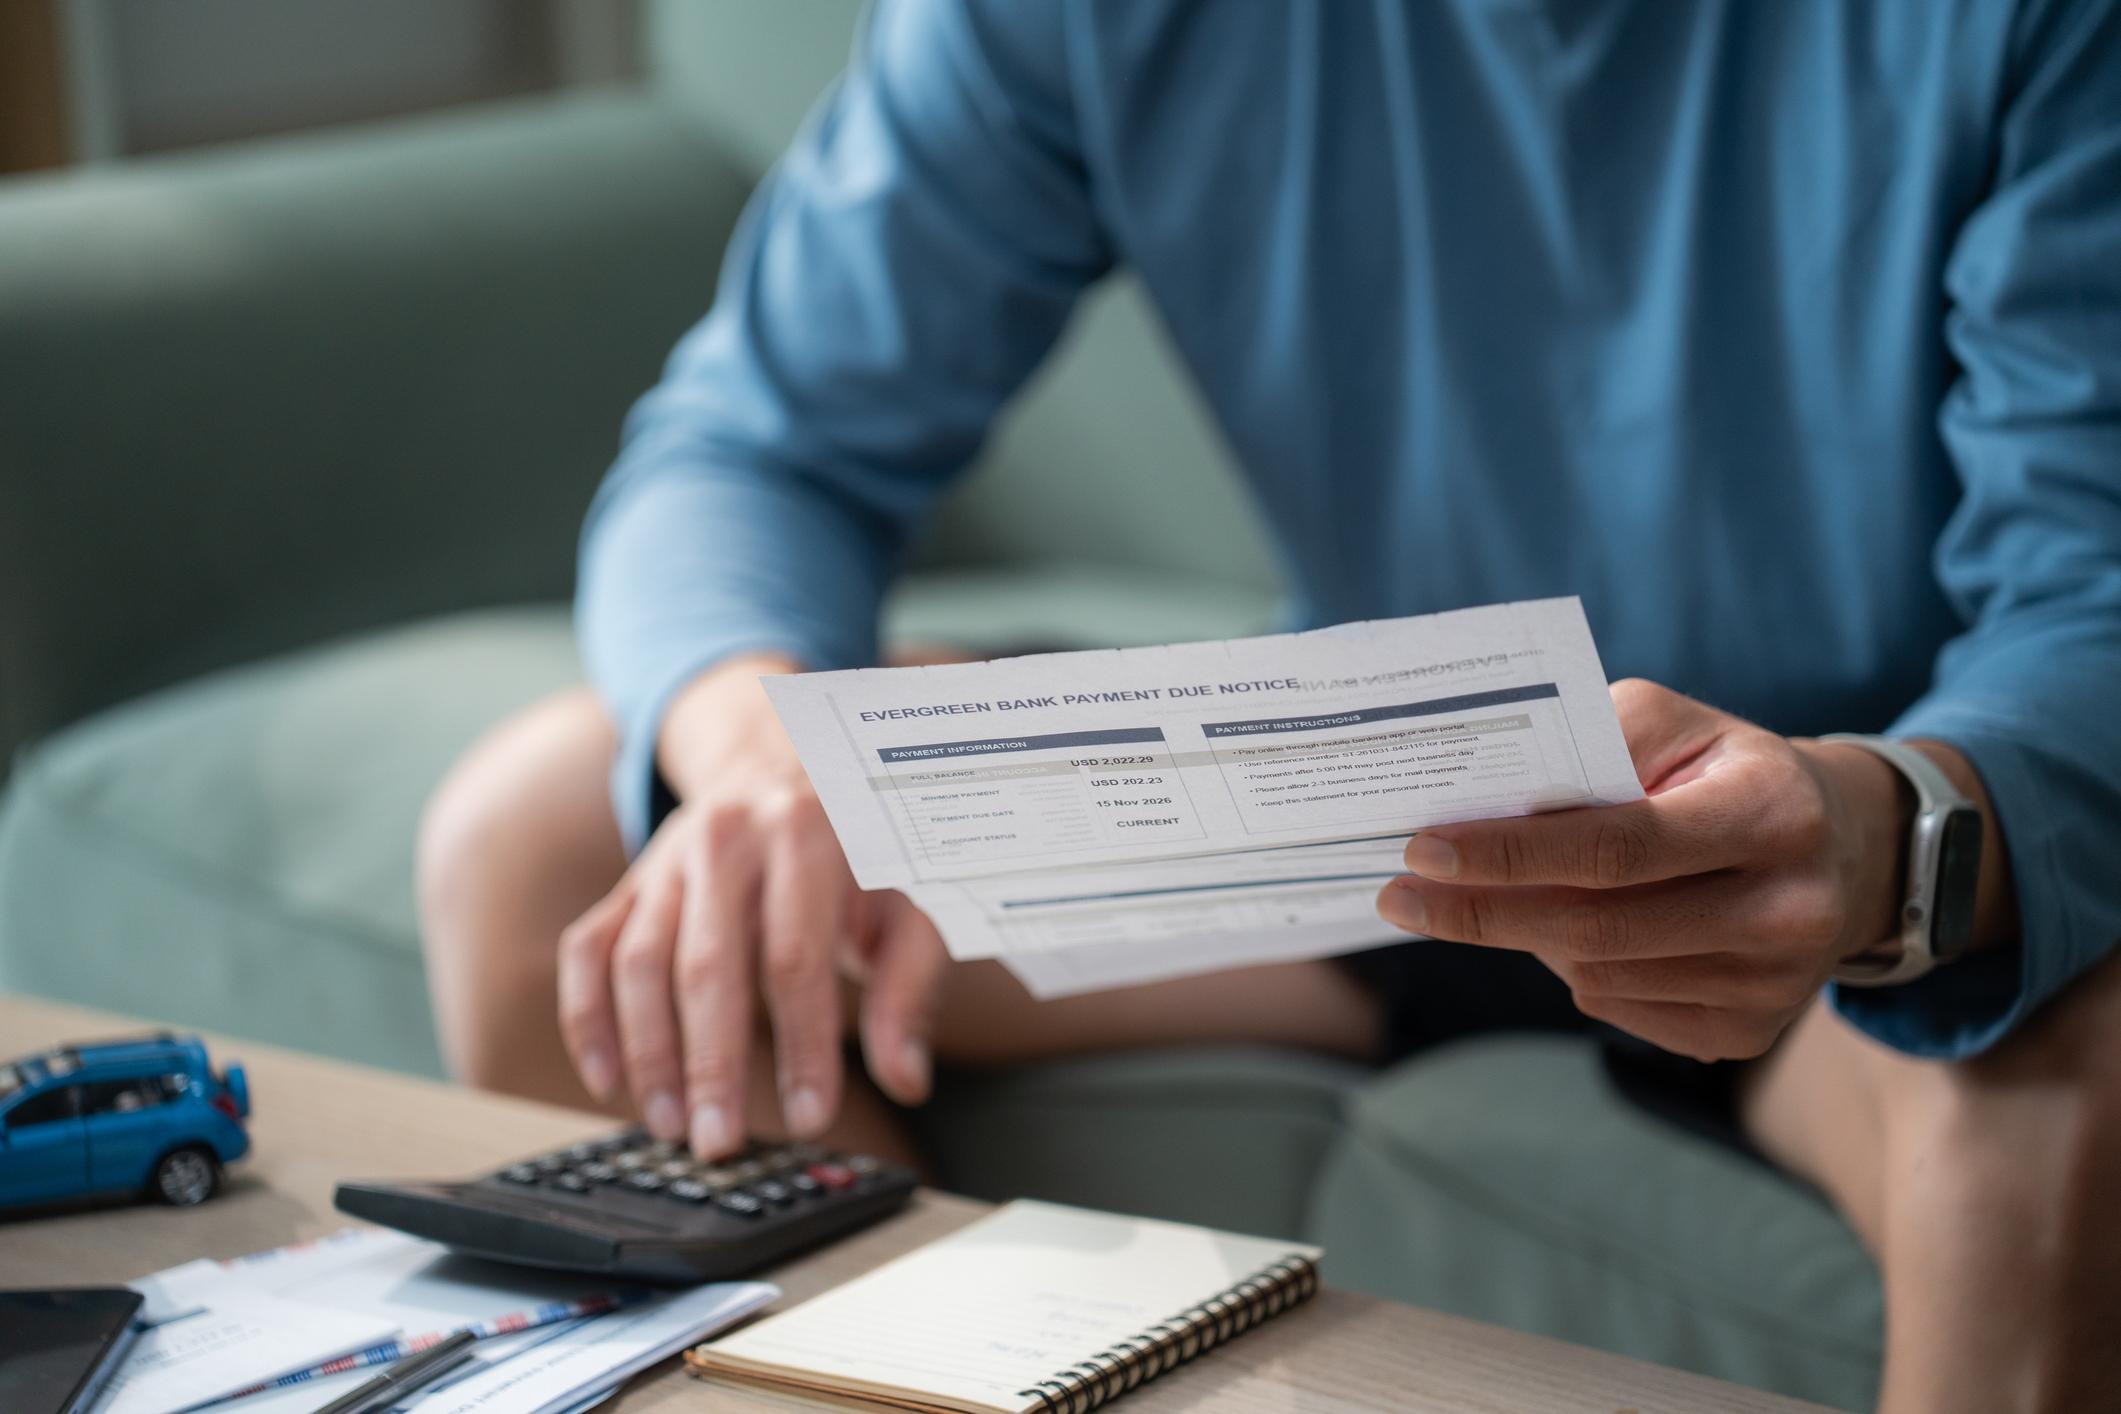
Making additional payments toward your car loan principal can reduce the amount of interest you pay over time. The principal is the original amount borrowed, excluding interest and other charges. Reducing this balance faster can help you repay the loan sooner.
Even small additional payments may contribute to meaningful savings over an extended period. For example, paying an extra $50 or $100 each month can reduce your outstanding balance faster than following the standard repayment schedule. The exact savings depend on your interest rate, remaining balance, and loan terms.
Before making extra payments, contact your lender to understand how additional money is applied. Some lenders automatically apply extra funds toward future installments unless you specifically request a principal reduction. You should confirm that the payment is being allocated correctly.
Check whether your loan includes prepayment penalties or additional payment restrictions. Many auto loans allow borrowers to make extra payments without penalties, but the conditions depend on the agreement and applicable regulations. Reviewing these terms can help you avoid unexpected charges.
Creating a consistent payment habit can make this strategy easier. You might use part of a work bonus, tax refund, or additional income to reduce your loan balance. Setting aside a small amount each month can also help you make occasional lump-sum payments.
Keep your emergency savings in mind before sending extra money to your lender. Using all available cash to pay down your vehicle loan could leave you financially vulnerable when unexpected expenses arise. Maintaining a reasonable savings reserve should remain a priority.
9. Review Your Car Insurance and Related Expenses
Your car payment is only part of the total cost of owning a vehicle. Insurance premiums, fuel, maintenance, registration, and parking can significantly affect your monthly transportation budget. Reducing these additional expenses may free up money that makes your existing loan payment easier to manage.
Start by reviewing your current car insurance policy. Compare coverage, deductibles, exclusions, and premiums with offers from other reputable insurance companies. Different insurers may charge different amounts for similar coverage based on their pricing methods and eligibility requirements.
Ask your insurance provider whether you qualify for discounts. Some companies offer lower premiums for safe driving records, multiple policies, vehicle safety features, or qualifying security devices. Available discounts vary by insurer, location, and individual circumstances.
You may also consider adjusting your insurance deductible. A higher deductible can sometimes reduce your premium, but it means you will need to pay more out of pocket when making an eligible claim. Choose an amount that you could comfortably afford during an emergency.
Avoid removing essential coverage simply to save money. If your vehicle is financed, your lender may require comprehensive and collision coverage. Failing to maintain the required insurance could violate your loan agreement and create additional financial risks.
Fuel expenses offer another opportunity for savings. Combining errands, maintaining proper tire pressure, avoiding unnecessary idling, and following recommended vehicle maintenance schedules can improve fuel efficiency. Driving smoothly and avoiding excessive acceleration may also reduce fuel consumption.
10. Create a Realistic Budget and Reassess Your Car Expenses
A practical monthly budget can help you understand whether your car payment is affordable. Many people focus on the loan installment without considering the complete cost of vehicle ownership. Reviewing all transportation expenses provides a clearer picture of where your money goes.
Begin by calculating your monthly take-home income. Then list your essential expenses, including housing, groceries, utilities, healthcare, debt payments, insurance, and transportation. Comparing your income with these expenses can reveal how much money remains available after necessary obligations.
Include every vehicle-related cost in your calculations. Consider your loan installment, fuel, insurance, routine maintenance, registration, parking, and potential repair expenses. Setting aside a small amount for unexpected vehicle costs can prevent financial surprises.
If your car payment is consuming too much of your income, identify expenses that can be reduced without affecting essential needs. Canceling unused subscriptions, limiting unnecessary shopping, and planning purchases can create additional room in your monthly budget.
You should also consider whether your vehicle matches your current financial situation. A car that was affordable when you had a higher income may become difficult to maintain after a change in employment or household expenses. Adjusting your transportation choices can help restore financial stability.
Set a realistic target for your monthly transportation budget. Your target should account for your income, existing financial obligations, savings goals, and the cost of living in your area. Avoid relying on general affordability rules without considering your individual circumstances.