Most drivers never see the full picture of a collision repair bill. The insurer sees one version of the numbers. You may see another. This gap confuses many people after an accident. A repair estimate can look simple on paper. Yet it hides many layers of cost, rules, and negotiation.
Body shops work with two very different customers. One is the insurance company that pays the claim. The other is you, the vehicle owner. Each customer gets billed under different rules. The insurer follows contracts, estimating software, and agreed labor rates. You follow the policy terms and your own deductible.
Knowing how these bills differ helps you protect your money. It also helps you spot errors or padding. This article explains the topic in three clear parts. First, we look at how the insurer’s bill is built. Second, we look at what lands on your bill. Third, we cover how to protect yourself and check every line.
Think of it as reading a repair invoice with a trained eye. Once you know the pattern, the numbers make much more sense. Many myths surround this topic. Some people believe shops always inflate prices for insurers. Others think insurers always underpay.
The truth sits in the middle. Both sides have real pressures and real limits. By the end, you will understand where each charge comes from. You will also know which questions to ask before you sign anything.
How the Insurer’s Bill Is Built
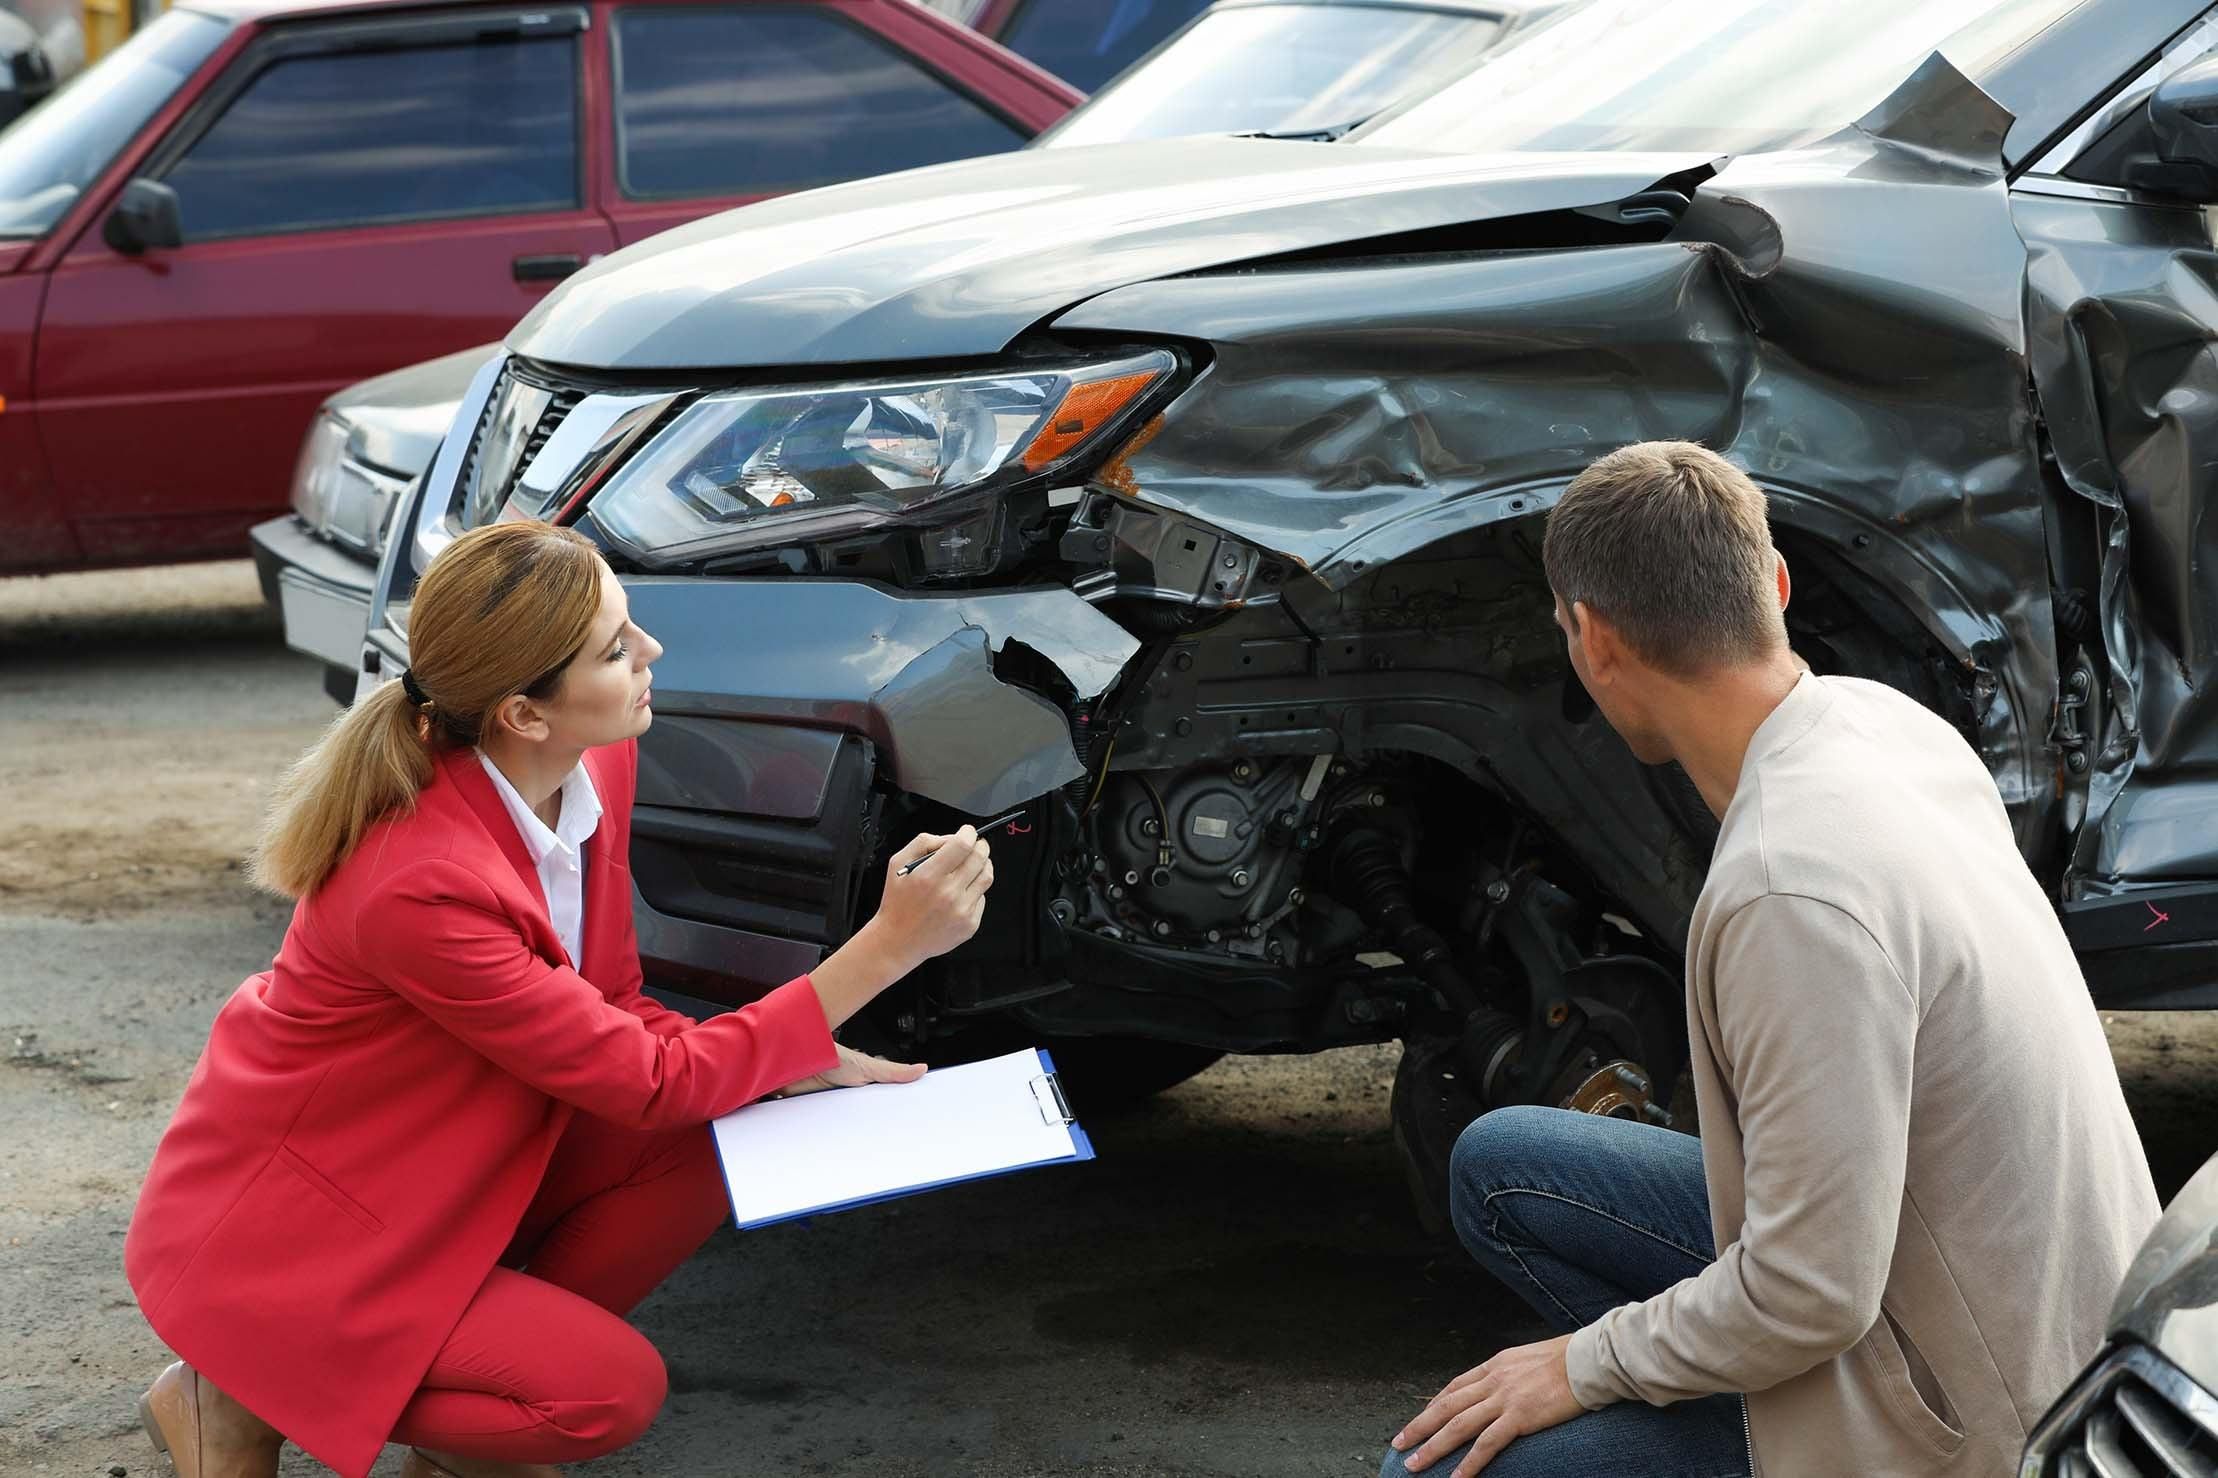
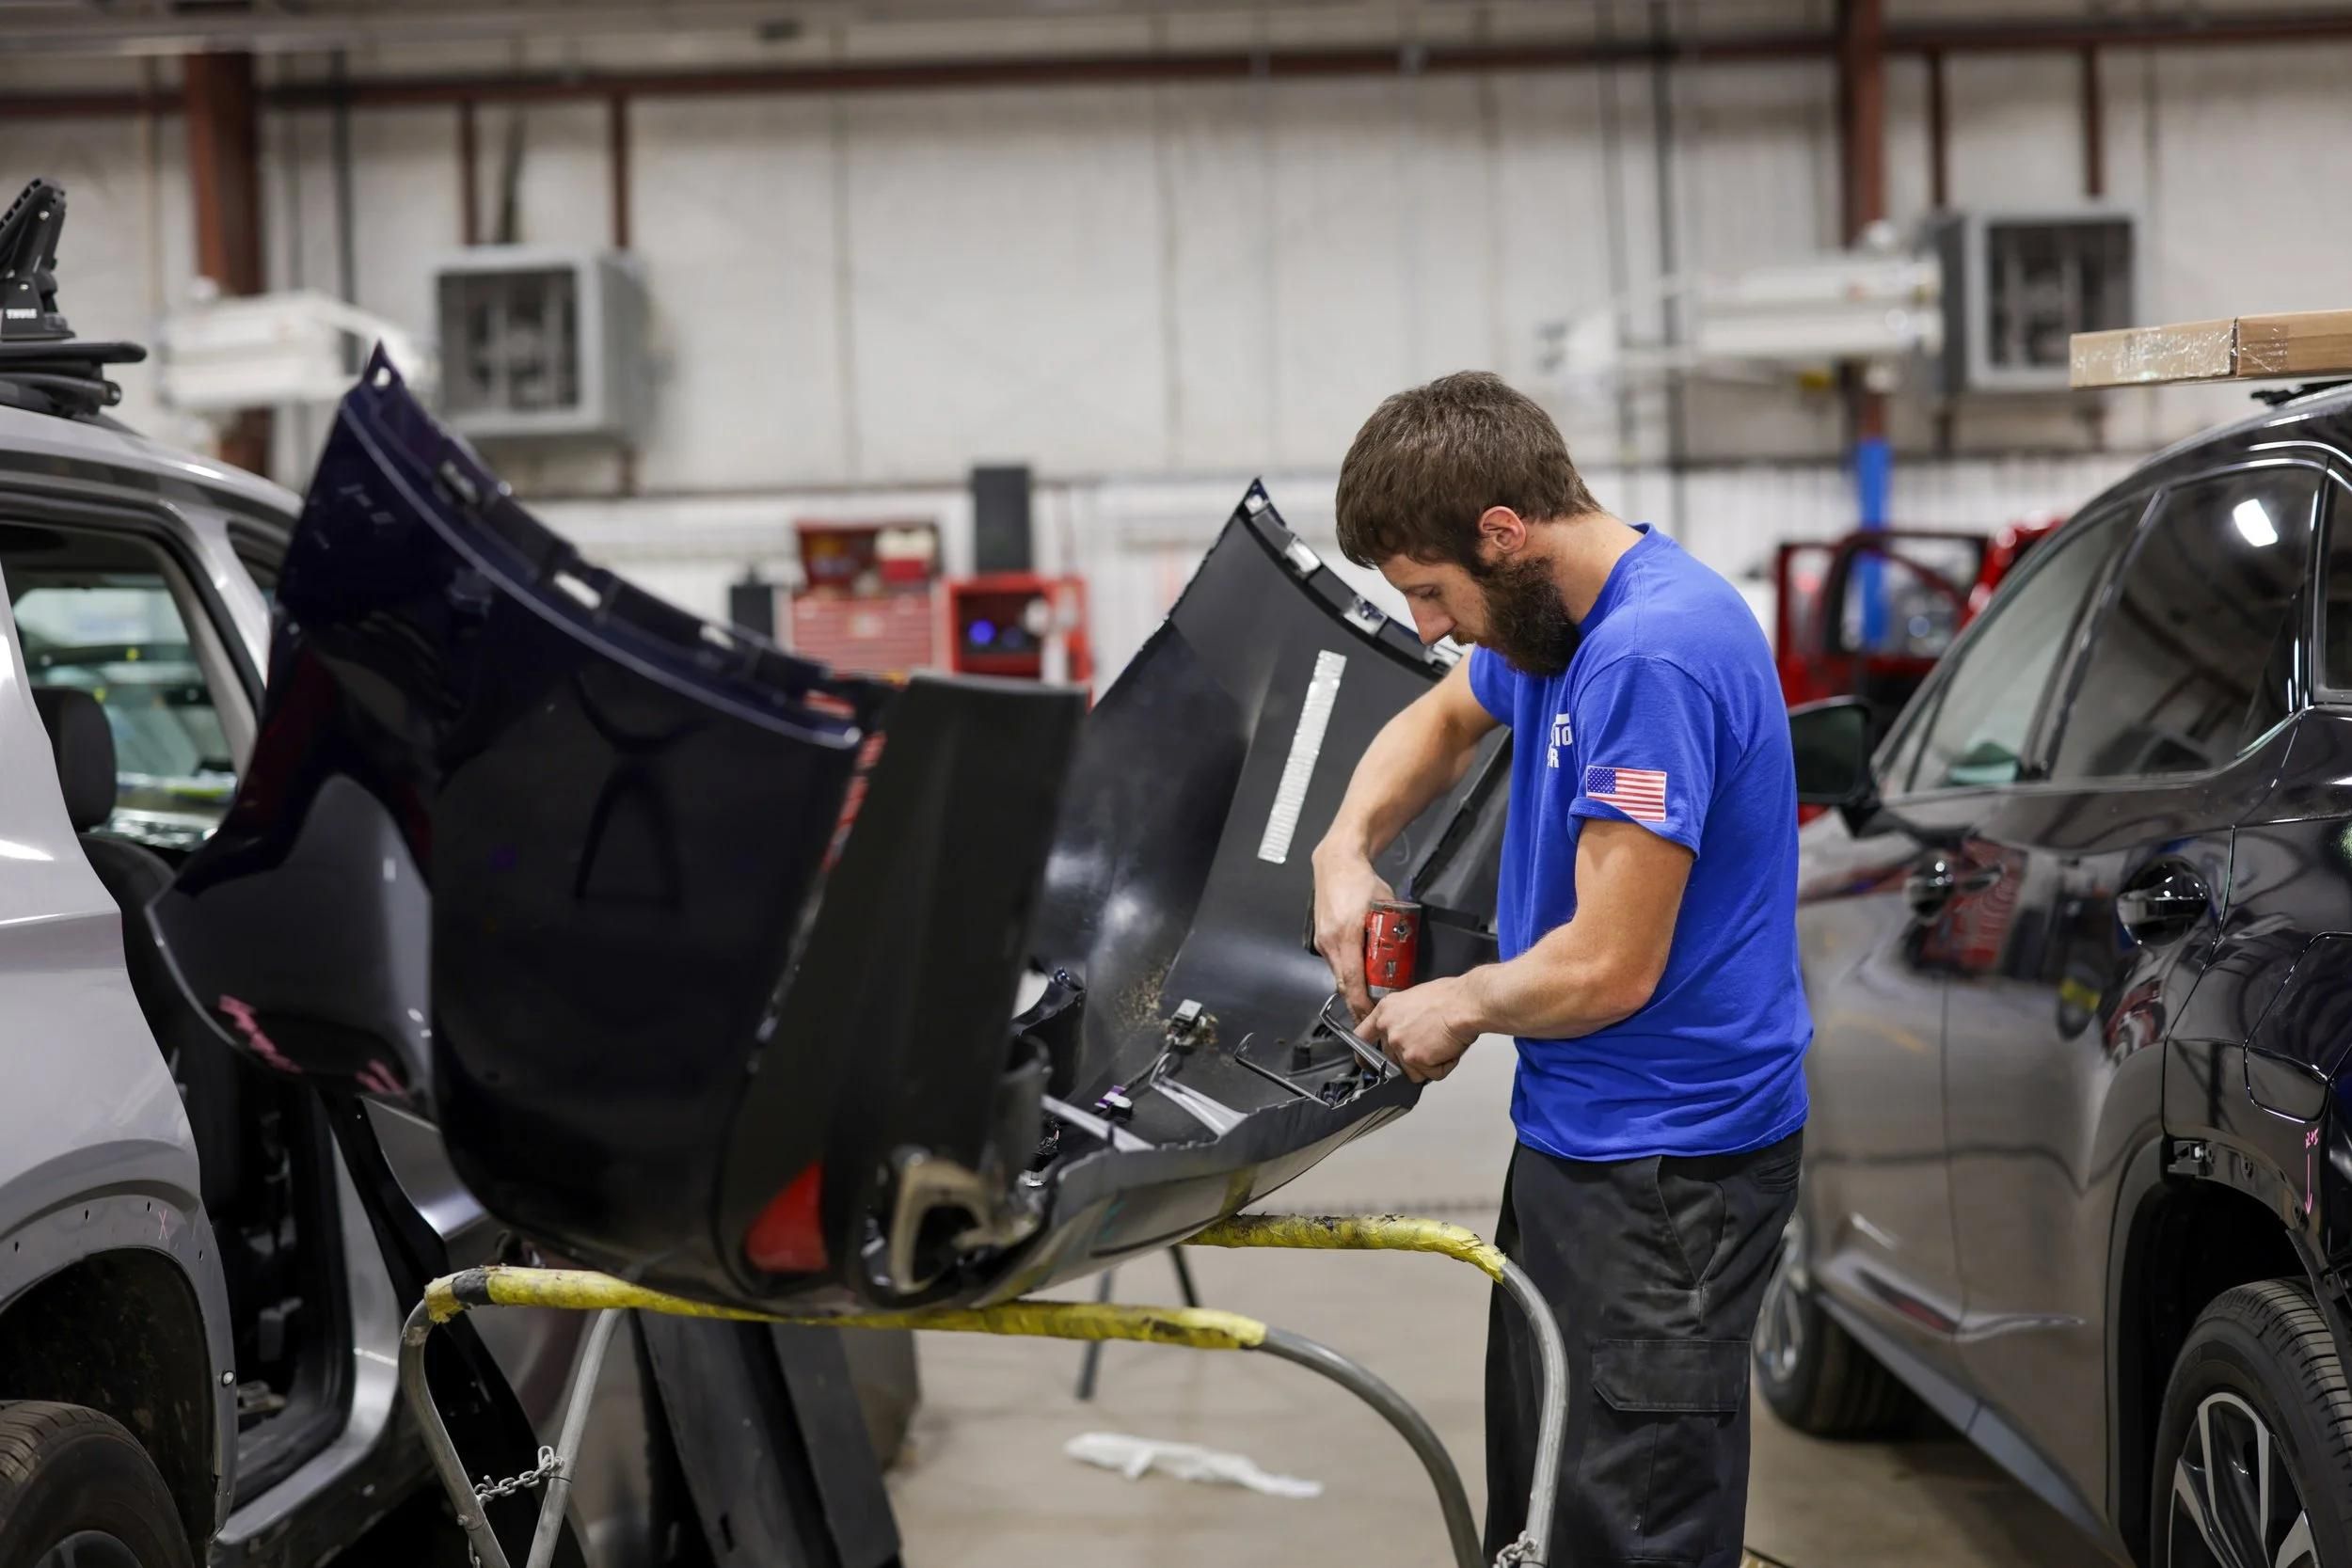
The insurer’s bill starts with an estimate. A shop inspects the damage and builds a repair plan. This plan lists every part, every labor hour, and every material.
Most shops use estimating software for this step. The software draws on industry databases of labor times. These databases set how long each repair should take.
Labor is split into several categories. Body labor covers dent repair and panel work. Paint labor covers refinishing. Mechanical labor covers suspension, cooling, and similar systems.
Frame labor and glass labor are separate again. Each category has its own hourly rate. Body labor is often the cheapest rate, while mechanical and frame work cost more.
Insurers often pay a set labor rate. This rate is based on local market surveys. It may be lower than what a shop wants to charge. Parts form the next big section. The estimate lists each part with a price. Parts can be new, aftermarket, used, or remanufactured.
Original manufacturer parts cost the most. Aftermarket parts cost less and are made by third parties. Used parts come from salvage vehicles. Many policies allow lower-cost parts on older cars. Some states require the insurer to disclose this on the estimate. Always check which parts type is listed.
Paint and materials are billed as a separate line. This covers paint, primer, clear coat, sandpaper, and masking tape. It is usually calculated per paint labor hour.
The rate for materials varies by region. Some insurers cap this charge. Shops sometimes dispute the cap. Sublet work also appears on the insurer’s bill. Sublet means work sent to an outside vendor. Examples include wheel alignment, glass, and airbag scanning.
The shop adds its own markup or handling in some cases. Insurers may question this markup. Agreements differ from shop to shop. Then comes the supplement. A supplement is an added charge found during repair. Hidden damage often appears after the car is taken apart.
The shop sends the supplement to the insurer for approval. An adjuster reviews it and may approve or reduce it. This is a very common source of delay.
Many shops also bill for tasks that are not obvious. Examples include scanning for fault codes and calibrating safety sensors. Modern cars need these steps after many repairs.
Calibration of cameras and radar has become a major cost. A simple bumper repair may now trigger sensor work. This can add hundreds of dollars.
Some shops join a direct repair program. These are agreements between a shop and an insurer. The shop accepts negotiated rates in exchange for steady referrals.
Direct repair programs speed up approvals. They also push shops toward set pricing. Critics say this can pressure shops to cut corners. Storage and towing may also be billed. These charges appear if the car sits at the shop. Insurers often cover reasonable towing and storage after a covered claim.
Rental car costs are usually separate from the body shop bill. The insurer pays the rental company directly. Policy limits apply to daily rate and total days.
The final insurer invoice combines all of these lines. It shows parts, labor, materials, sublet, and taxes. The insurer pays this total minus your deductible.
The shop must justify each line to the adjuster. Photos, repair orders, and parts invoices serve as proof. A weak paper trail can lead to payment cuts.
Insurers also audit shops from time to time. They compare estimates with final bills. Large gaps can trigger a review. This system has checks, but it is not perfect. Errors, disputes, and delays still happen. Understanding the structure helps you follow along.
What the Body Shop Bills You
Your bill is usually much smaller and simpler. In most claims, you pay the deductible. The insurer covers the rest. The deductible is the amount you agree to pay on every claim. Common amounts range from a few hundred dollars to a thousand or more. The shop collects it when you pick up the car.
Some shops collect the deductible at drop-off. Most wait until the work is done. Ask about the policy before you hand over your keys. Beyond the deductible, you may face other charges. These happen when the insurer does not cover something. The shop then bills you for the difference.
One common case is a labor rate gap. The shop may charge more than the insurer pays. The shop may ask you to cover the shortfall. This practice is called balance billing. Rules on it vary by state and by contract. Some shops absorb the difference to keep customers happy.
Another case is the parts upgrade. You may ask for original parts when the policy pays for aftermarket. The price difference becomes your cost. Upgrades and extras also fall on you. Examples include custom paint, upgraded wheels, and cosmetic add-ons. Insurers only pay to restore the car to its prior condition.
Pre-existing damage is another trap. Old scratches or dents are not part of the claim. If you ask the shop to fix them, you pay for that work. Betterment charges can appear as well. Betterment means the repair leaves the car better than before. Insurers may reduce payment for new tires or a new battery.
Wear items often trigger this rule. A worn tire replaced with a new one adds value. The insurer may ask you to cover part of it. Non-covered repairs also land on your bill. If the insurer denies part of the claim, you owe that cost. This can include mechanical failure unrelated to the accident.
Total loss situations work differently. The insurer pays the car’s market value minus your deductible. The shop may still charge you for storage and teardown.
Silence or vague answers are a warning sign. Your bill should always match what you agreed to. If new charges appear, ask for written proof. Never pay for work you did not approve.
How to Protect Yourself and Check Every Line
Start by getting everything in writing. Ask for a detailed estimate before work begins. It should list parts, labor hours, and materials. Compare that estimate with the insurer’s version. The two should align closely. Ask the shop to explain any gap.
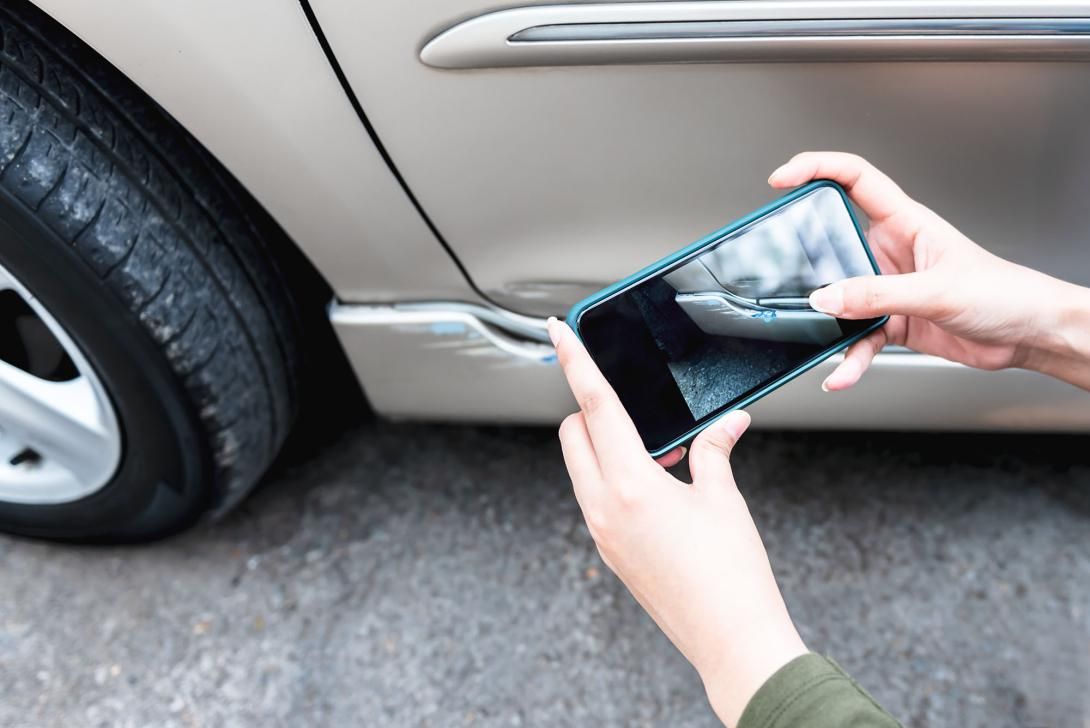
Keep copies of every document. This includes photos, estimates, and supplements. A clear record helps in any dispute. Take your own photos of the car before drop-off. Capture all sides and any existing damage. This protects you from pre-existing damage disputes.
You have the right to choose your repair shop in most places. An insurer may suggest a shop, but it cannot always force you. Pick one you trust. Check the shop’s certifications and reviews. Manufacturer certification shows training for your car brand. This matters for modern vehicles with complex systems.
Ask which parts will be used. Request that the parts type be written on the estimate. If the policy covers original parts, insist on them. Ask about warranty coverage. Good shops offer a written warranty on repairs and paint. Lifetime warranties are common at reputable shops.
Review the labor hours carefully. Compare them with the type of damage. Very high hours for minor damage may signal padding. Check for duplicate charges. Sometimes the same task appears under two labor categories. This is a known source of overbilling.
Look at the paint and materials line. Make sure it matches the paint labor hours. Large jumps deserve a question. Watch the supplement process closely. Ask for a copy of every supplement. Confirm that each added item matches real hidden damage.
Ask whether sensor calibration was done. If the car has driver assist features, it likely needs it. Request a printed report as proof. Understand your policy before you need it. Read the sections on parts, rental, and deductible. Know what your coverage promises.
Call your insurer if the shop asks for money beyond your deductible. Ask if that charge is valid. The insurer may resolve it with the shop. If the insurer underpays, ask for a re-inspection. A second look often leads to a fair adjustment. Bring documents that support your case.
You can also get an independent estimate. This gives you a comparison point. It strengthens your argument for a higher payout. Some people use an independent appraiser. This is a professional who values the damage. Many policies include an appraisal clause for disputes.
Diminished value is another issue to know. A repaired car often loses resale value. Some policies and some regions allow a claim for this loss. If problems continue, contact your state insurance department. They handle complaints about unfair practices. The process is usually free.
Consumer protection offices can also help with shop disputes. They review billing complaints and misleading practices. Keep your records ready. Inspect the car carefully before paying. Check panel gaps, paint match, and trim fit. Look in daylight if possible.
Fraud harms everyone through higher premiums. Never agree to inflate a claim. Honest billing protects you legally. The insurer’s bill and your bill serve different purposes. One covers the full repair cost under contract. The other covers your share and any extras.
Knowledge is your best protection. Read each line and ask questions. A little effort can save real money. Take control of the process from the start. Choose your shop wisely and keep records. You will then understand exactly what you are paying for.