The average new-car payment has hit a record. Edmunds says financed buyers paid $787 a month in the third quarter of 2026. Many are stretching loans to seven years or longer. Loans of 84 months or more now make up 25.5% of new-car financing.
So a payment under $500 can feel like a relic. It isn’t. It just takes the right car and the right method. Experian found nearly one in five new buyers still landed under $500 in early 2026. Most of them downsized or brought real cash. You don’t have to do either.
The cheapest new sedans now start near $23,500. Inexpensive new cars are getting harder to find because of material costs and tariffs. Lease specials, though, push payments far lower. Autotrader’s cheapest October leases all sit below $250 a month.
One warning first. Advertised payments hide the cash due at signing. I spread that cash across each lease term to show a truer monthly cost. Most offers below end around November 2. Deals also vary by region. Check your zip code before you visit a dealer.
1. Kia K4
The K4 is the best pure value on this list. The base LX starts at $22,290, or $23,535 with destination. That makes it the cheapest new car in America right now.
The lease is strong too. The EX trim is available at $229 a month for 24 months, with $3,499 due at signing. Spread that cash across 24 months and the real cost is about $375.
Buying works as well. GOBankingRates estimated a $349 payment with 20% down. That leaves over $150 of room under your $500 ceiling. The base car is not bare-bones. It carries a modern interior and a long warranty. TrueCar praises its modern styling and high-tech cabin.
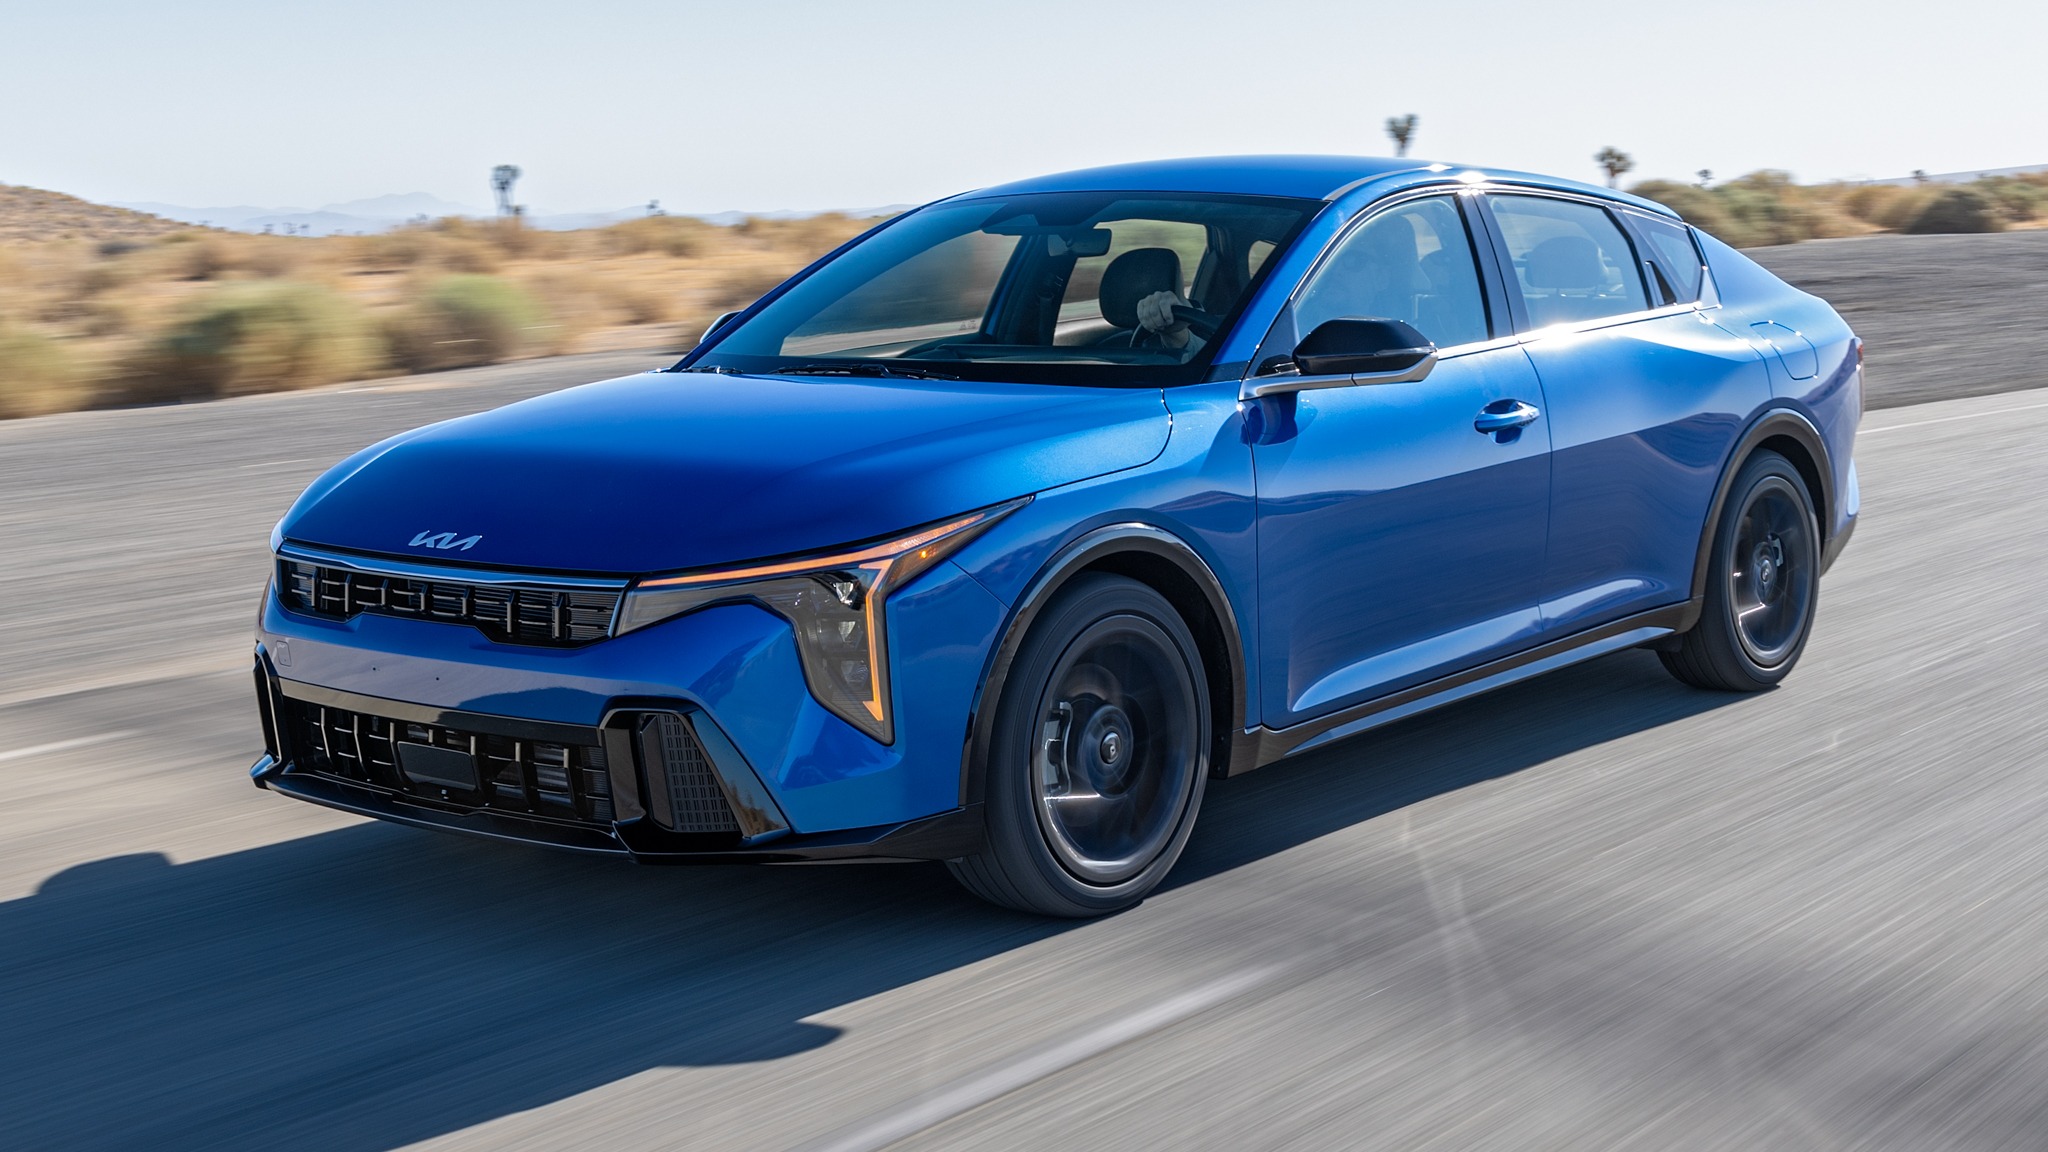
Insurance matters here. Kia says the K4 is its safest car. KBB calls it the safest Kia, according to IIHS. Safer cars often cost less to insure. The weak spot is power. The base engine lacks punch. Highway merging takes planning.
The K4 also comes as a hatchback. Expect to pay a few thousand dollars more for it. The K4 Hatchback starts at $26,235. Who should buy it? Commuters who want maximum car for minimum money. Anyone who keeps cars for a decade will love the warranty.
Who should skip it? Drivers who crave speed. Also anyone who needs all-wheel drive. My advice is simple. Take the 24-month lease if you like new cars every two years. Finance if you plan to keep it.
Either route leaves real breathing room. You could even add a larger down payment and cut the payment to near $300. That is the quiet power of starting cheap.
2. Hyundai Elantra
The Elantra is the K4’s closest rival. They share a platform and a warranty. Hyundai’s 10-year, 100,000-mile powertrain warranty comes with the Elantra. Pricing is nearly identical. The Elantra lists at $23,870. The lease asks $239 a month for 24 months. Cash due at signing is $3,599.
Add it up and the true cost is about $389. That’s still more than $100 under your limit. One lender-style estimate agrees on buying. The Elantra came in at $374 a month with 20% down.
Some sites list even cheaper leases. One tracker showed the Elantra at $169 a month for 24 months. Treat that as a regional hint, not a promise. Always ask for the out-the-door sheet.
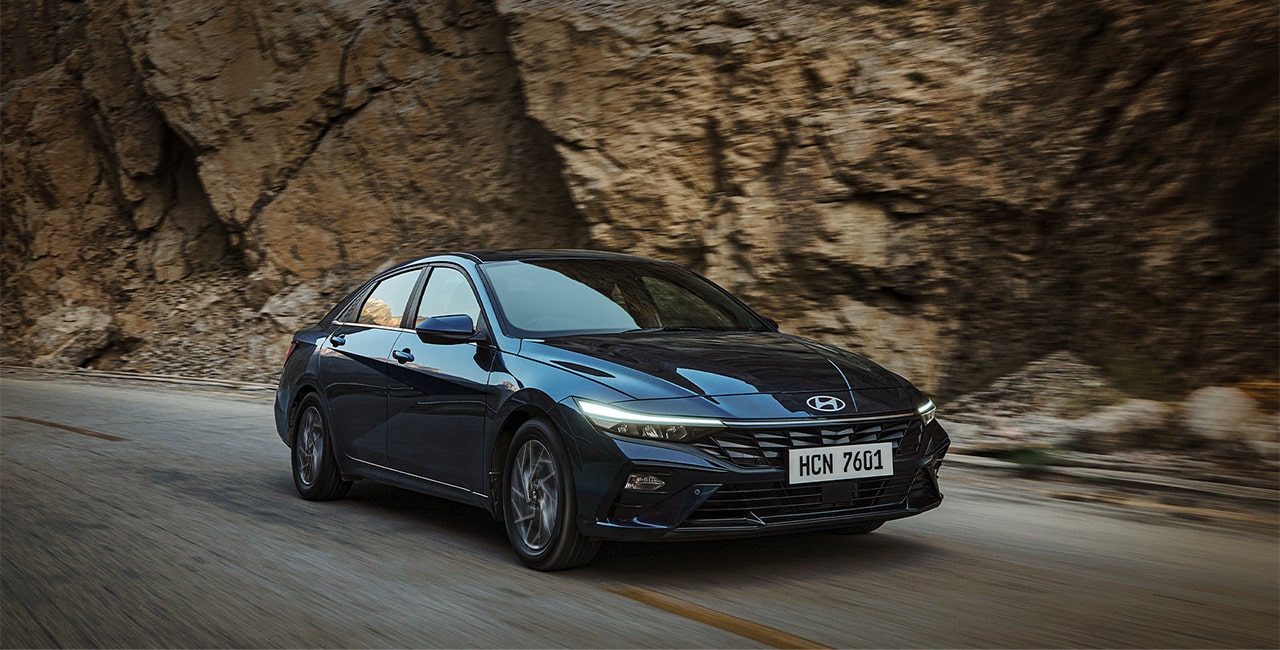
The cabin is the star. The Elantra offers one of the largest interiors in its class, plus a roomy trunk. Rear-seat adults will notice. Want better fuel economy? Look at the hybrid. The Elantra Hybrid starts at $25,450 and costs about $398 a month. That is still safely under $500.
Fuel savings can offset the higher price. Do the math on your yearly miles. High-mileage drivers usually win with the hybrid. Watch the trim ladder. Upper trims climb quickly. A fully loaded Elantra can lose its budget appeal.
Stay on the SE or SEL. Those trims keep the car honest. The base car already carries plenty of safety tech. Who should buy it? Families who need back-seat space on a budget. Also anyone who values a long warranty. The Elantra isn’t flashy. It simply works. That is exactly what a sub-$500 plan needs.
3. Nissan Sentra
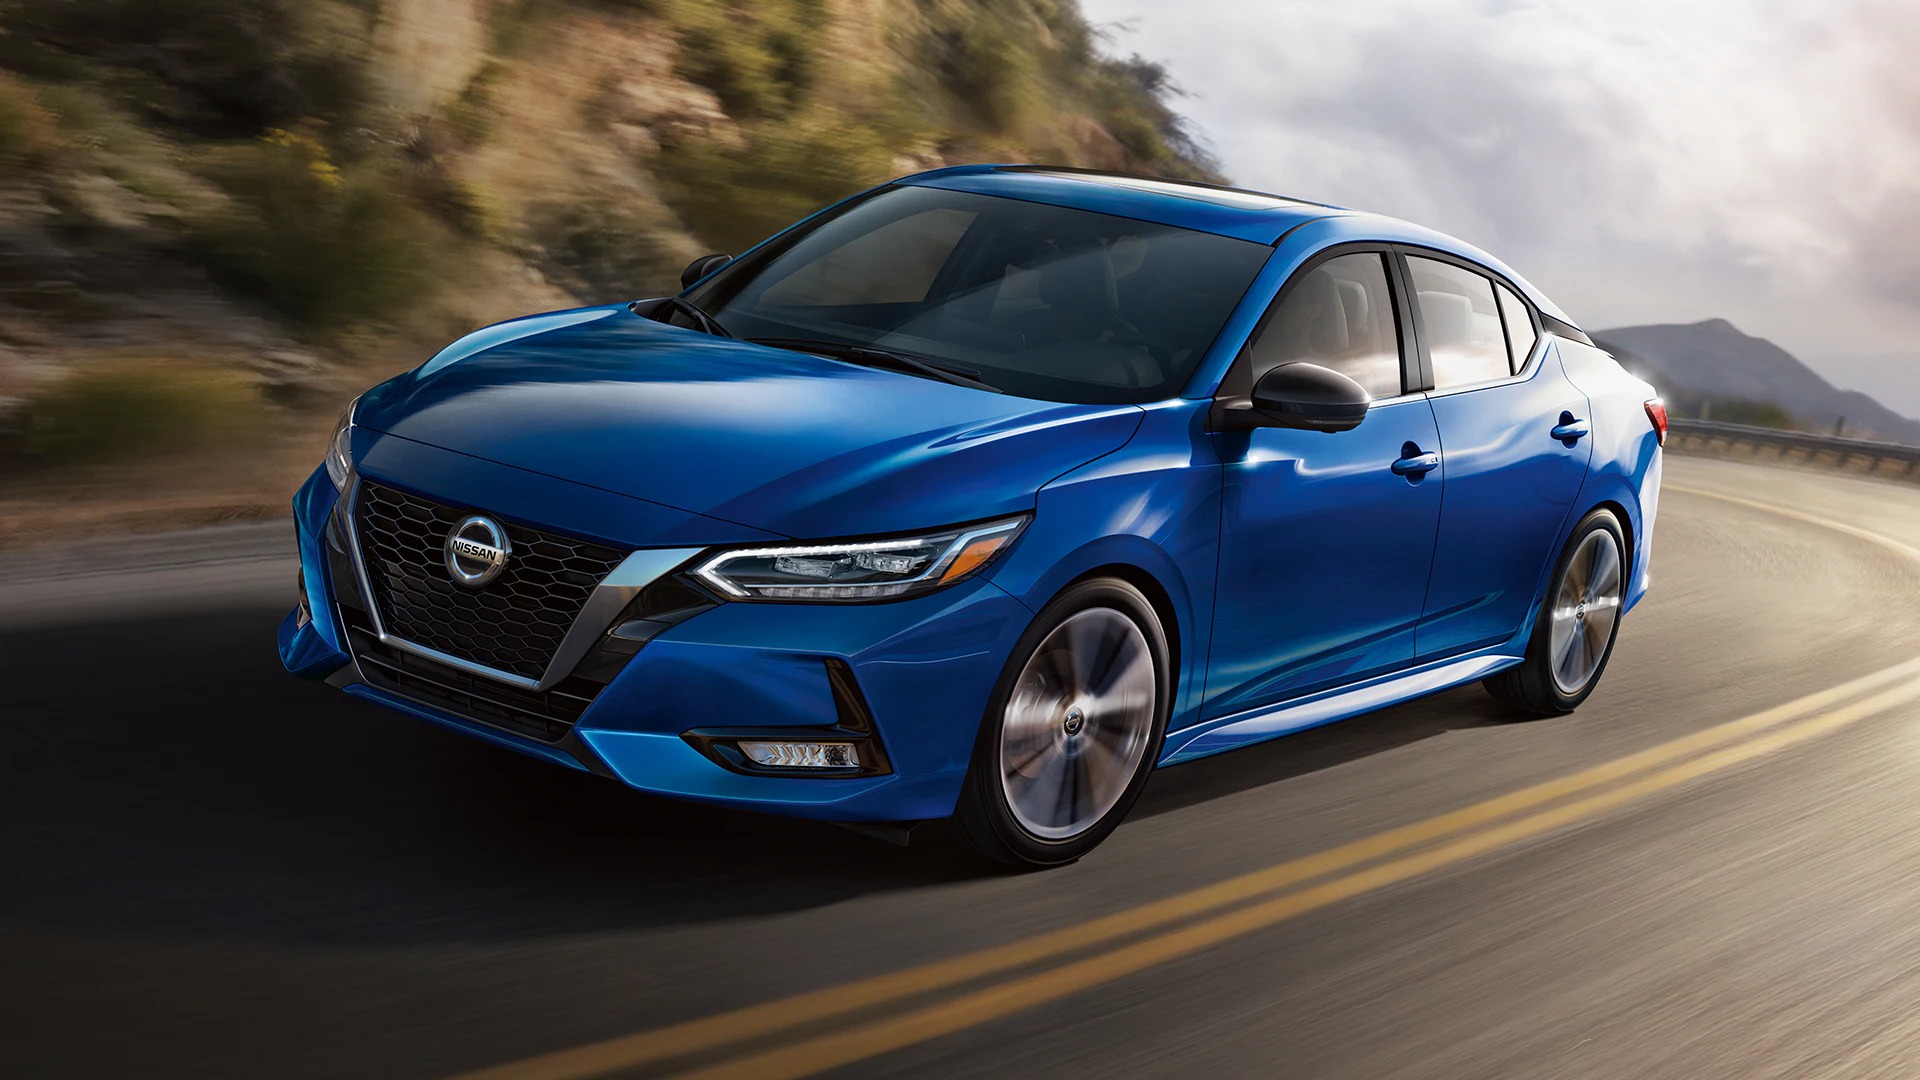
The Sentra is the sleeper pick. Nissan redesigned it for 2026. The sedan arrived completely redone inside and out, with a bold new look. It is also very affordable. The base Sentra S carries a $22,600 MSRP, or $23,845 with destination. Standard driver aids come along too.
The new Sentra has an impressive roster of standard driver aids. Buying is the smart route here. Nissan models took three spots on a list of cars under $400 a month. The Sentra is one of them.
Nissan does run lease deals on its bigger sedan. One dealer group showed an Altima SV at $226 a month for 36 months. That deal allowed only 5,000 miles a year. Another listing had the Altima at $239 for 36 months.
Those mileage limits matter. A cheap lease with 5,000 miles can become expensive. Overage fees add up quickly. If you finance, keep the term sensible. A 60-month loan builds equity faster. Stretching to 84 months lowers the payment but raises interest.
Edmunds says average new-car interest costs hit $9,938 this quarter. A cheap car should not carry an expensive loan. Shorter terms protect you. Who should buy it? Drivers who want a sporty look without paying for it. The Sentra feels more modern than its price suggests.
Who should skip it? Anyone wanting a hybrid option. The Sentra sticks with a gas engine. Trim discipline matters again. The base S is fine. Upper trims push toward $28,000. If your goal is a clean, no-drama payment, this is a great pick. Pair it with a decent down payment. You’ll land comfortably near $350.
4. Toyota Corolla
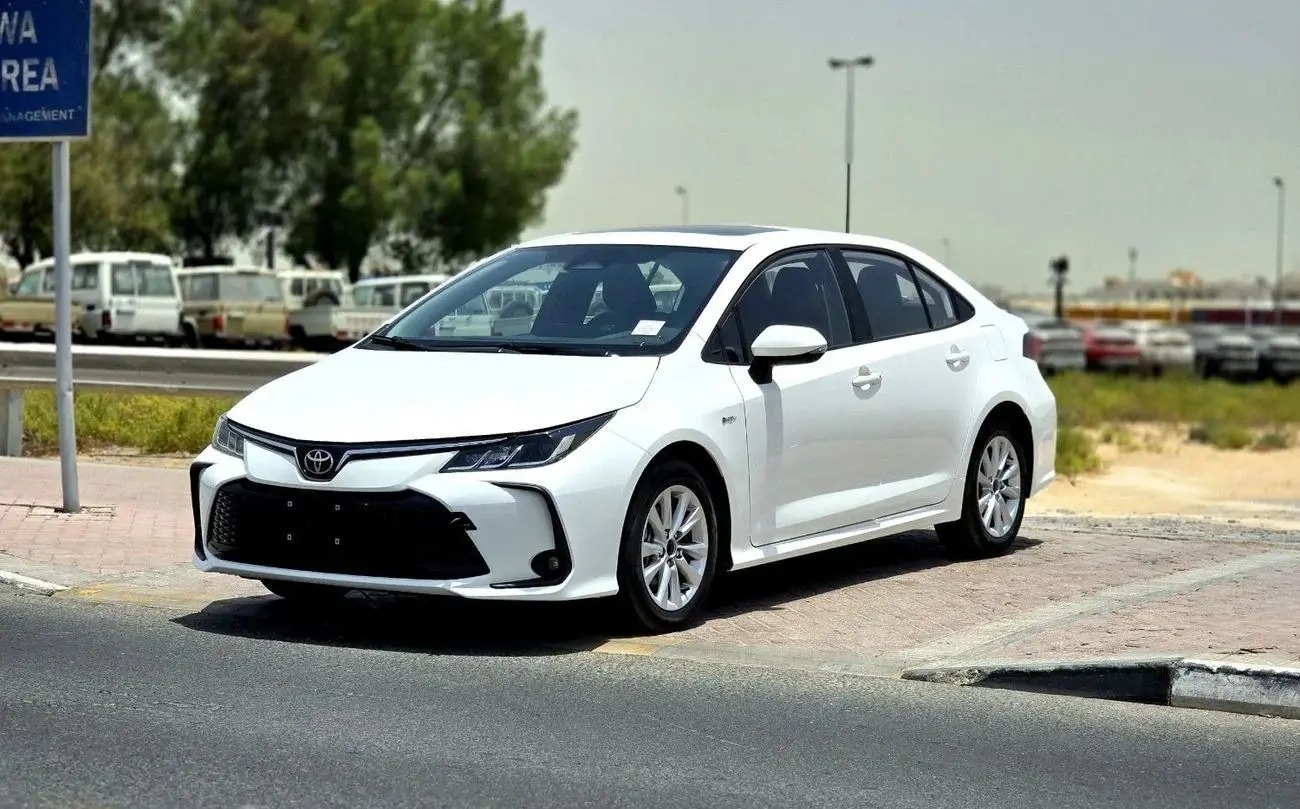
The Corolla earns its reputation. Resale value stays high, and reliability is legendary. Those traits lower your real cost over time. The October lease is excellent. Toyota offers the Corolla LE at $239 a month for 36 months, with $2,999 due at signing. That is a true cost of near $322.
The sticker price is fair. The Corolla lists at $24,420. That sits just above the K4 and Elantra. Why pay more? Toyota’s long-term value. Corollas keep their worth better than most rivals. That helps if you buy and later sell.
Some regional offers look even better. One Chicago-area offer showed the LE at $199 a month for 36 months. The down payment there was $3,999.
Compare these carefully. Lower monthly cost can hide a higher upfront bill. Add the cash due to the payment before you decide. Mileage is the catch. The advertised deal includes 10,000 miles per year. Drive more and you’ll pay extra at lease end.
A commuter doing 15,000 miles should negotiate more miles. Each added 1,000 miles usually costs a small fee. Still cheaper than overage penalties.
The Corolla’s cabin is simple and sturdy. It isn’t exciting. But it’s calm, quiet, and easy to live with. Fuel economy is excellent. Your gas bill will stay low. That helps your total monthly budget, not just the payment.
Who should buy it? Anyone who wants the lowest-stress ownership. Also drivers planning to resell later. Who should skip it? Buyers wanting maximum cabin tech. Rivals offer more screens for the money. The deal ends November 2. If the Corolla is your pick, move quickly.
5. Hyundai Kona
The Kona is the entry point into small SUVs. It sits higher than the sedans above. That helps with visibility and cargo space. The lease deals are remarkable. Autotrader lists the Kona at $219 a month for 36 months, with $3,999 due. The true cost lands near $330.
The Kona’s sticker price is $27,100. That is higher than the compact sedans. But the lease discounts close the gap. There’s a second deal on the newer model. A 2027 Kona SE FWD leases for $239 a month until November 2. Compare both before you sign.
One tracker even listed a $99 monthly lease. It was a 24-month deal with $3,999 due at signing. Treat that as a regional promotion. Verify it in your area.
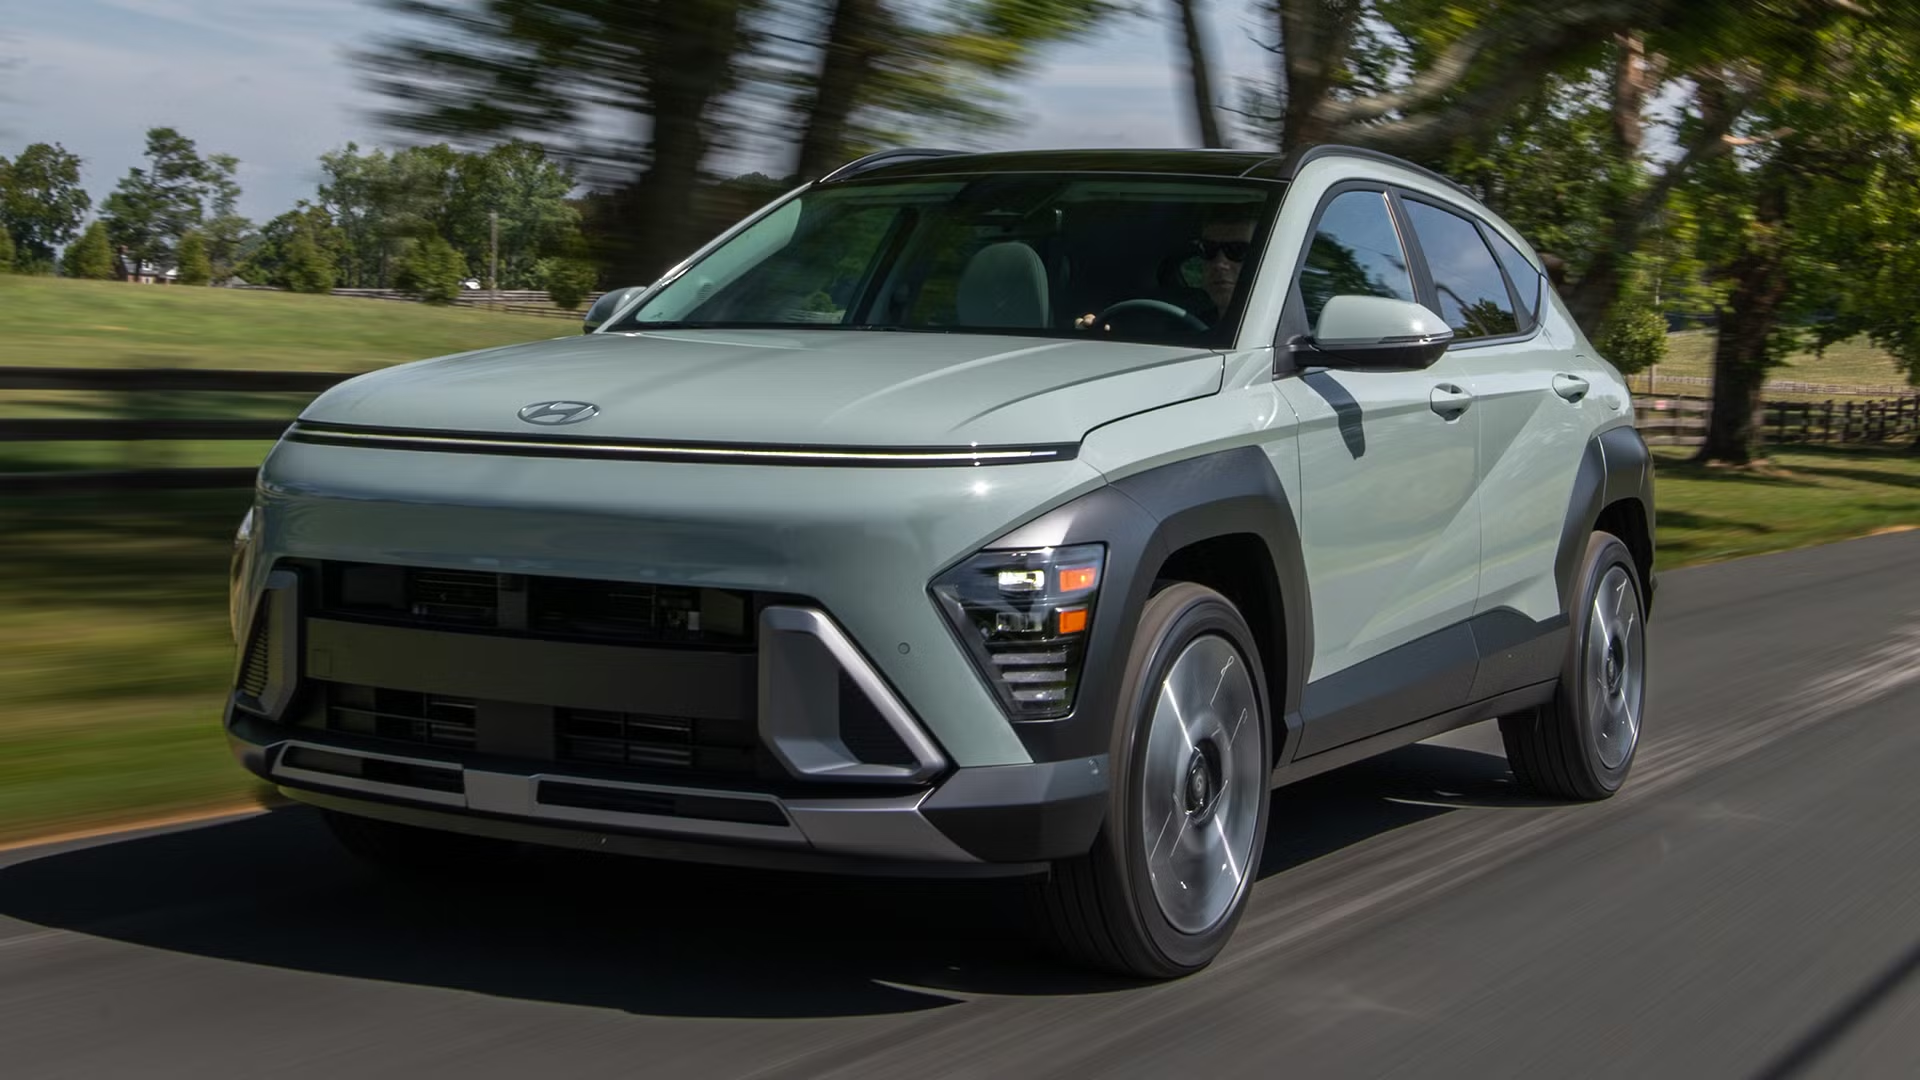
Add the cash due and the picture changes. $3,999 over 24 months adds about $167 monthly. The true cost is closer to $266. That is still impressive. Few SUVs come close. The Kona proves small crossovers can fit tight budgets.
Hyundai’s warranty applies here too. That protects you if you buy at lease end. Many lessees do exactly that. Driving feel is lively. The Kona is small and easy to park. City drivers will enjoy it.
Space is the compromise. Rear legroom is modest. Tall passengers will notice. Front-wheel drive is the base setup. All-wheel drive adds cost. Skip it unless you face snow.
Who should buy it? City commuters who want a higher seat. Also first-time SUV owners. Who should skip it? Families with growing kids. A Tucson fits that job better. The Kona is a flexible budget pick. Choose the lease for the lowest payment. Choose a loan if you plan to keep it.
6. Honda Civic Hatchback
The Civic hatchback is the enthusiast’s budget pick. It drives better than almost anything near its price. It also hauls more than a sedan. The October lease is solid. Autotrader lists it at $249 a month for 39 months, with $3,999 due. The true cost lands near $352.
The sticker price is $29,190. That is higher than the cheapest sedans. But the lease structure keeps payments low. The 39-month term is unusual. It gives you extra time at a low rate. Check whether it includes enough miles.
Honda’s brand strength shows at resale. Civics hold value well. That helps if you later buy the car out. The hatchback body is the real bonus. The cargo area is wide and usable. Bikes, strollers, and groceries all fit.
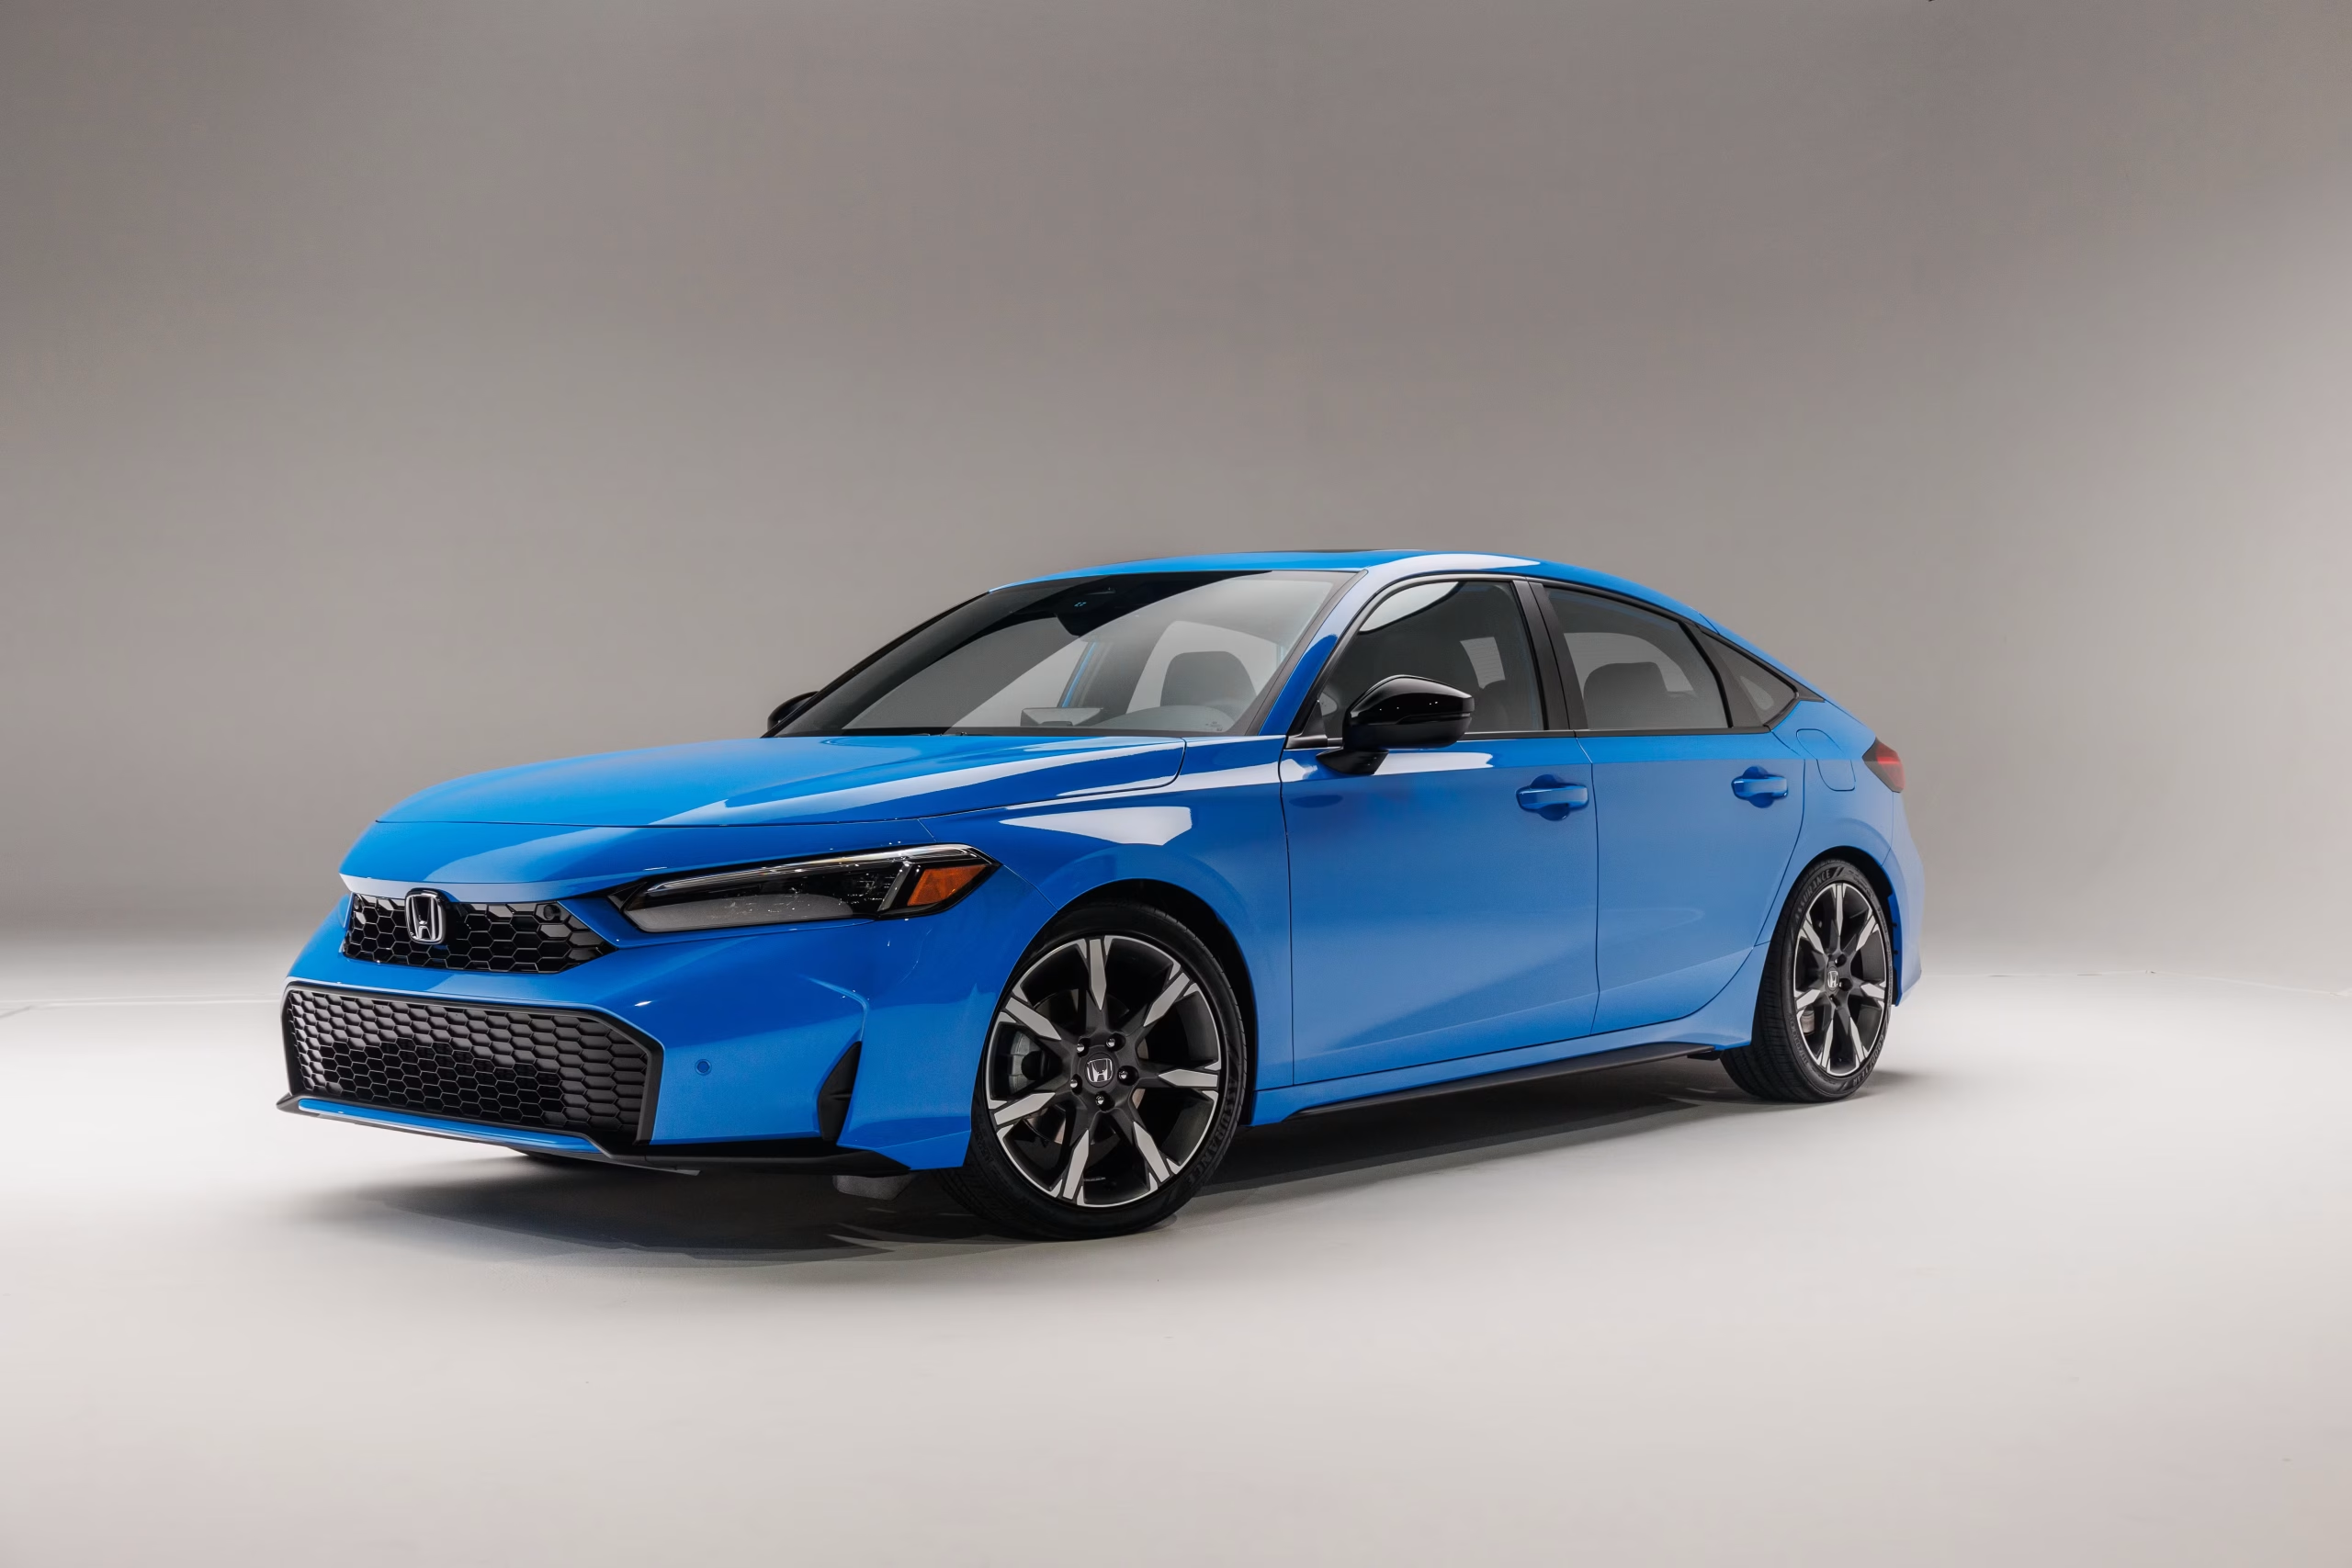
The driving experience is the main draw. Steering is crisp and the chassis is balanced. It feels more expensive than it is. The interior is clean and simple. Physical buttons remain for key controls. Many drivers prefer that.
Fuel economy is excellent. You’ll visit the pump less often. That keeps your total budget lean. The downside is the entry price. A Civic costs more than a Corolla or K4. You’re paying for the driving feel.
Watch the trims. Sport and higher grades add up fast. The LX is the value anchor. Who should buy it? Drivers who want fun without a big bill. Also anyone who needs flexible cargo space.
Who should skip it? Pure bargain hunters. The K4 and Elantra cost less. Even so, a $352 true cost is hard to beat. You get a polished, well-built car. Few rivals feel this complete.
7. Subaru Impreza
The Impreza has one trick no rival matches. Every Subaru comes with standard all-wheel drive. At this price, that is rare. The lease deal is cheap. Subaru offers the Impreza Sport at $249 a month for 36 months, with $2,904 due. The true cost is about $330.
That deal applies to the 2026 Sport trim. The Sport adds nicer features over the base car. It’s a sensible step up. All-wheel drive changes the math. Snowy states usually charge a premium for it. Here it’s built in.
Lucknow readers may shrug at snow. But US shoppers in northern states will care. Rain and gravel roads also benefit. The Impreza is a hatchback. That makes cargo room flexible. Rear seats fold flat.
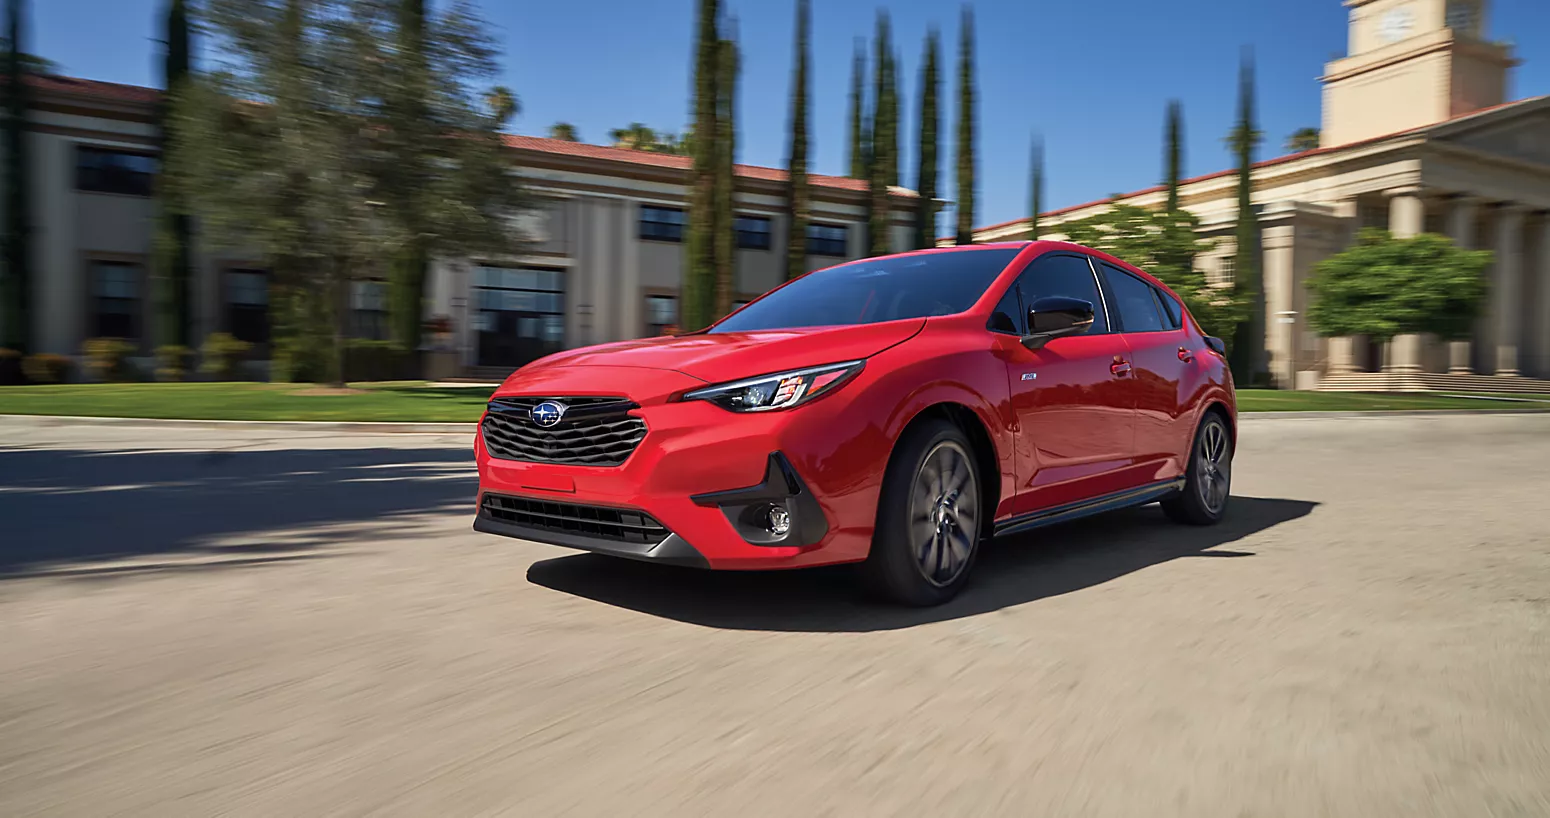
Ground clearance is a quiet advantage. The car handles rough roads well. Potholes feel less punishing. Subaru’s safety tech is strong. Its driver-assist system comes standard. That adds peace of mind.
Fuel economy is slightly lower than front-drive rivals. AWD costs a bit at the pump. Budget a few extra dollars monthly. The cabin is practical rather than fancy. Materials feel durable. Kids and pets won’t wreck it.
Compare the cash due carefully. $2,904 is lower than many rivals. That keeps your true monthly cost down. Who should buy it? Anyone in a snowy or rural region. Also, outdoorsy drivers on a budget.
Who should skip it? City drivers who never see weather. A front-drive car costs less. If you do want AWD, this is the cheapest path. Few new cars offer it under $500 a month. The Impreza makes it easy.
8. Toyota Camry
The Camry is the grown-up choice. It is bigger than a Corolla. Rear passengers get real room. Its hybrid-only lineup means excellent fuel economy. Gas costs stay low. That helps your whole budget.
The lease is competitive. Toyota advertises the Camry LE at $279 a month for 36 months, with $3,999 due. The true cost is about $390. That is still well below $500. You gain a larger car for roughly $70 more than a Corolla. Many drivers find that worthwhile.
Resale value is a major plus. Camrys age well. Buyers pay extra for used ones. The ride is calm. The cabin is quiet at highway speeds. Long trips feel easy.
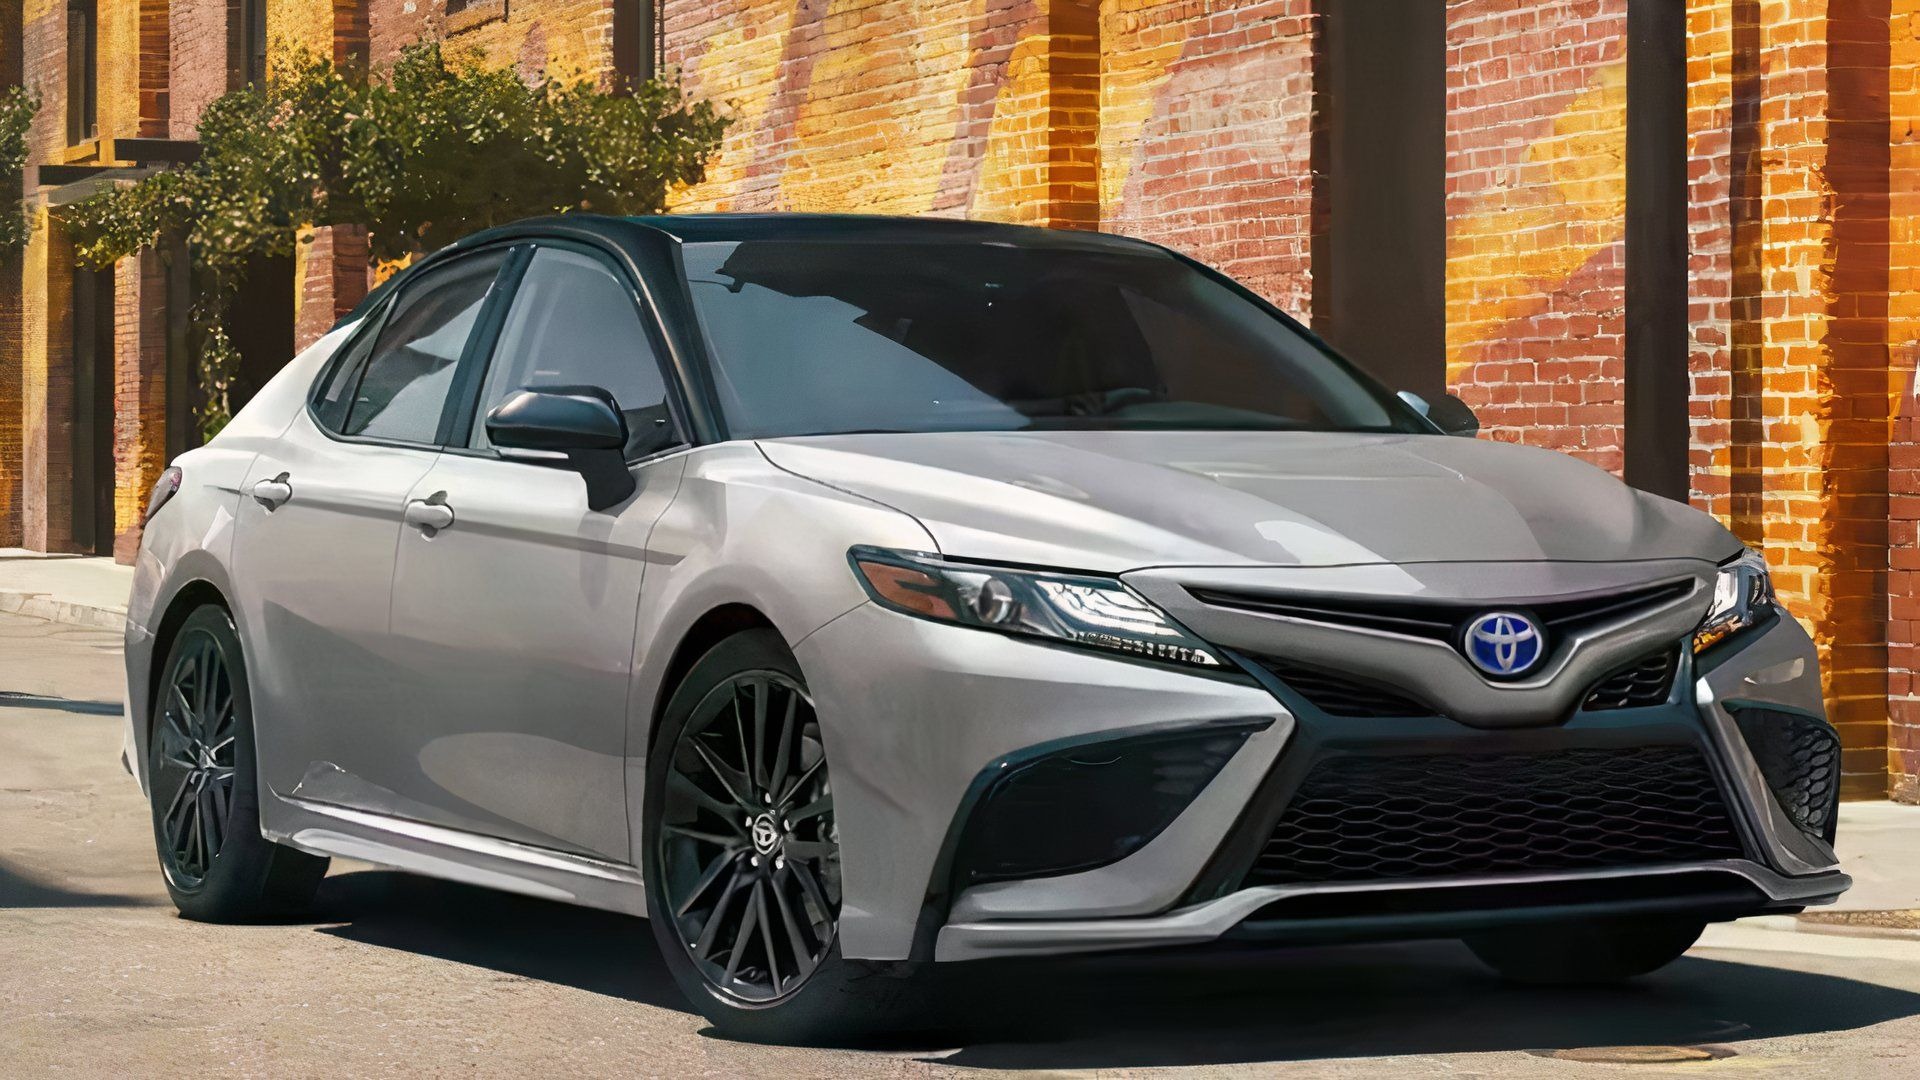
Technology is strong. The LE includes modern safety systems. Toyota’s driver-assist suite is well regarded. Compare it with its rival. The Accord leases for less. But the Camry’s fuel economy may offset that.
Ask the dealer about disposition fees. Some leases hide extra charges at the end. Get them in writing. Mileage limits matter as well. Check the annual allowance. Long commuters should negotiate more miles.
If you plan to buy, expect a bigger sticker. The Camry costs more than compact sedans. A larger down payment helps. Who should buy it? Commuters who want comfort. Also families needing a sedan with real space.
Who should skip it? Buyers wanting a small SUV. The Camry is a sedan only. At $390 true cost, you stay comfortably under $500. You also leave room for insurance. That matters more than people expect.
9. Honda Accord
The Accord is the best midsize sedan deal right now. It looks sharp and drives well. It also leases for very little. The Accord leases at $229 a month for 36 months, with $3,999 due. The true cost lands near $340. That is cheaper than the Camry deal.
The Accord’s MSRP is $29,690. You’re getting a $30,000 car for a compact-car payment. That is the real story here. Honda wins on driving feel. Steering is precise and the ride is composed. Few midsize sedans match it.
The cabin is spacious. Rear seats are generous. A family of four fits easily. The trunk is large. Weekend luggage is no problem. Road trips feel comfortable.
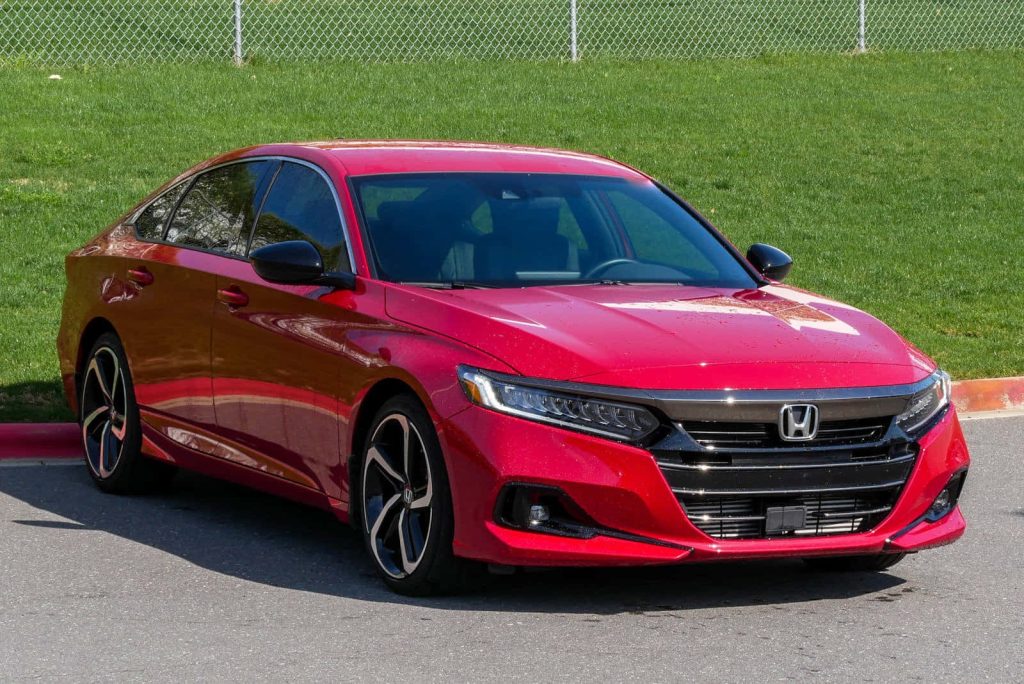
Honda’s reliability record is strong. Maintenance costs stay modest. That protects your budget beyond the payment. Resale value remains high. That helps if you buy the car at lease end. Equity is more likely.
Lease terms matter again. Check mileage limits. Honda leases often cap annual miles. Look at the due-at-signing amount. $3,999 is typical. Some dealers will roll it into payments.
Be careful with that trick. Rolling cash into payments raises the monthly cost. You may exceed your budget. Insurance on a midsize sedan costs more than a compact. Get quotes before you sign. Add them to your monthly total.
Who should buy it? Drivers who want a premium feel for less. Also anyone who values space. Who should skip it? City drivers with tight parking. A smaller car makes life easier. The Accord proves a bigger car doesn’t mean a bigger payment. Right now the lease market rewards it.
10. Kia Sportage Hybrid
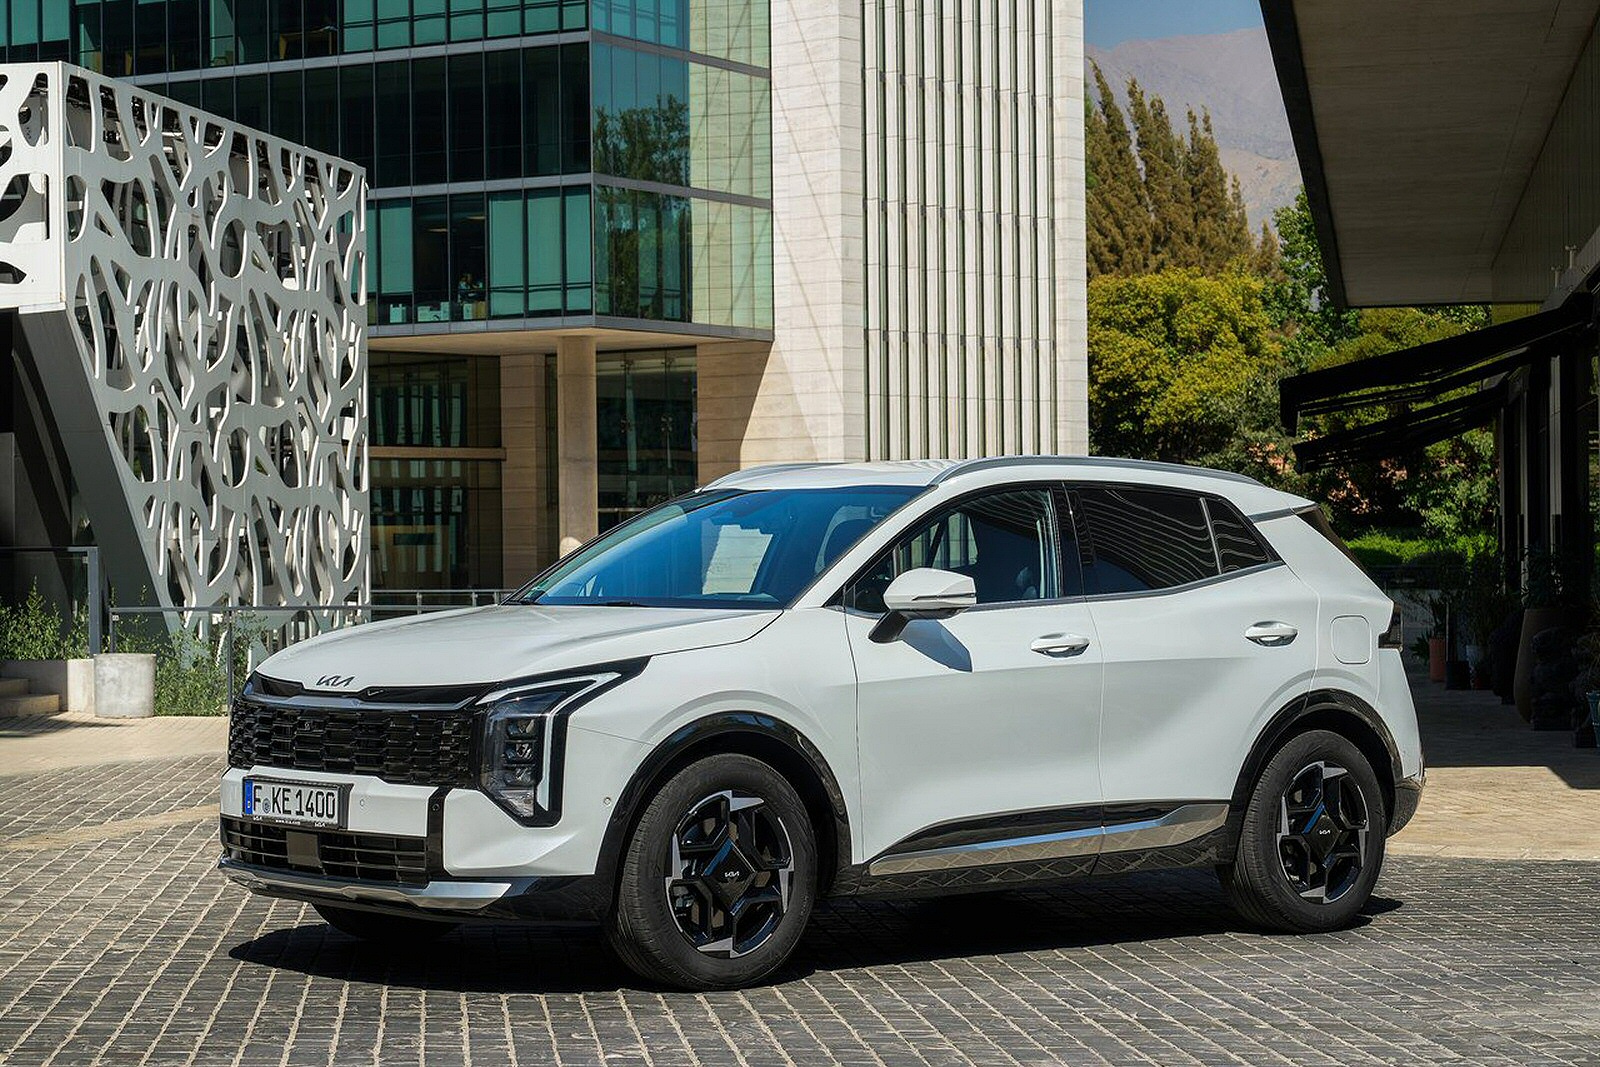
The Sportage Hybrid is the family pick. It’s a compact SUV with real space. It also sips fuel. The sticker price is higher. The Sportage Hybrid lists at $31,985. That is the highest on this list.
Still, the lease holds up. Kia advertises $249 a month for 24 months, with $4,656 due. The true cost lands near $443. That is the closest to $500 here. But it’s still under. You also get a hybrid SUV.
The 24-month term is short. That raises the monthly cost. A 36-month term may lower it. Ask for alternative terms. Dealers can often restructure a lease. Longer terms usually cut the payment.
Cash due is the pain point. $4,656 is significant. Compare it against other deals. Hybrid fuel savings help. Families who drive a lot save the most. Gas costs fall noticeably.
A similar Honda CR-V Hybrid lease costs $319 a month for 39 months. That deal asks for $4,699 down. Compare the two closely. The Sportage has a bold look. Its interior feels modern. Screens are large and easy to use.
Cargo space is generous. Rear seats are comfortable. Kids fit easily. Kia’s warranty adds confidence. Hybrid components are covered. That matters for long ownership.
Who should buy it? Families wanting an efficient SUV. Also anyone who hates frequent fuel stops. Who should skip it? Anyone watching every dollar. The sedans above cost much less. This one demands attention to the fine print. Negotiate the cash due and the term. Do that and it becomes a smart buy.