Truck insurance costs depend on more than a vehicle’s badge or purchase price. Insurers assess how a truck is used, where it travels, who drives it, how much it costs to repair, and the claims associated with similar vehicles. No single national list identifies ten trucks that every insurer has officially labelled high risk.
The vehicles below represent truck categories and examples that may attract closer underwriting or higher premiums under particular conditions. Actual pricing varies by insurer, location, coverage, driving history, equipment, and business use, so buyers should compare quotes before choosing a truck for their needs and budget.
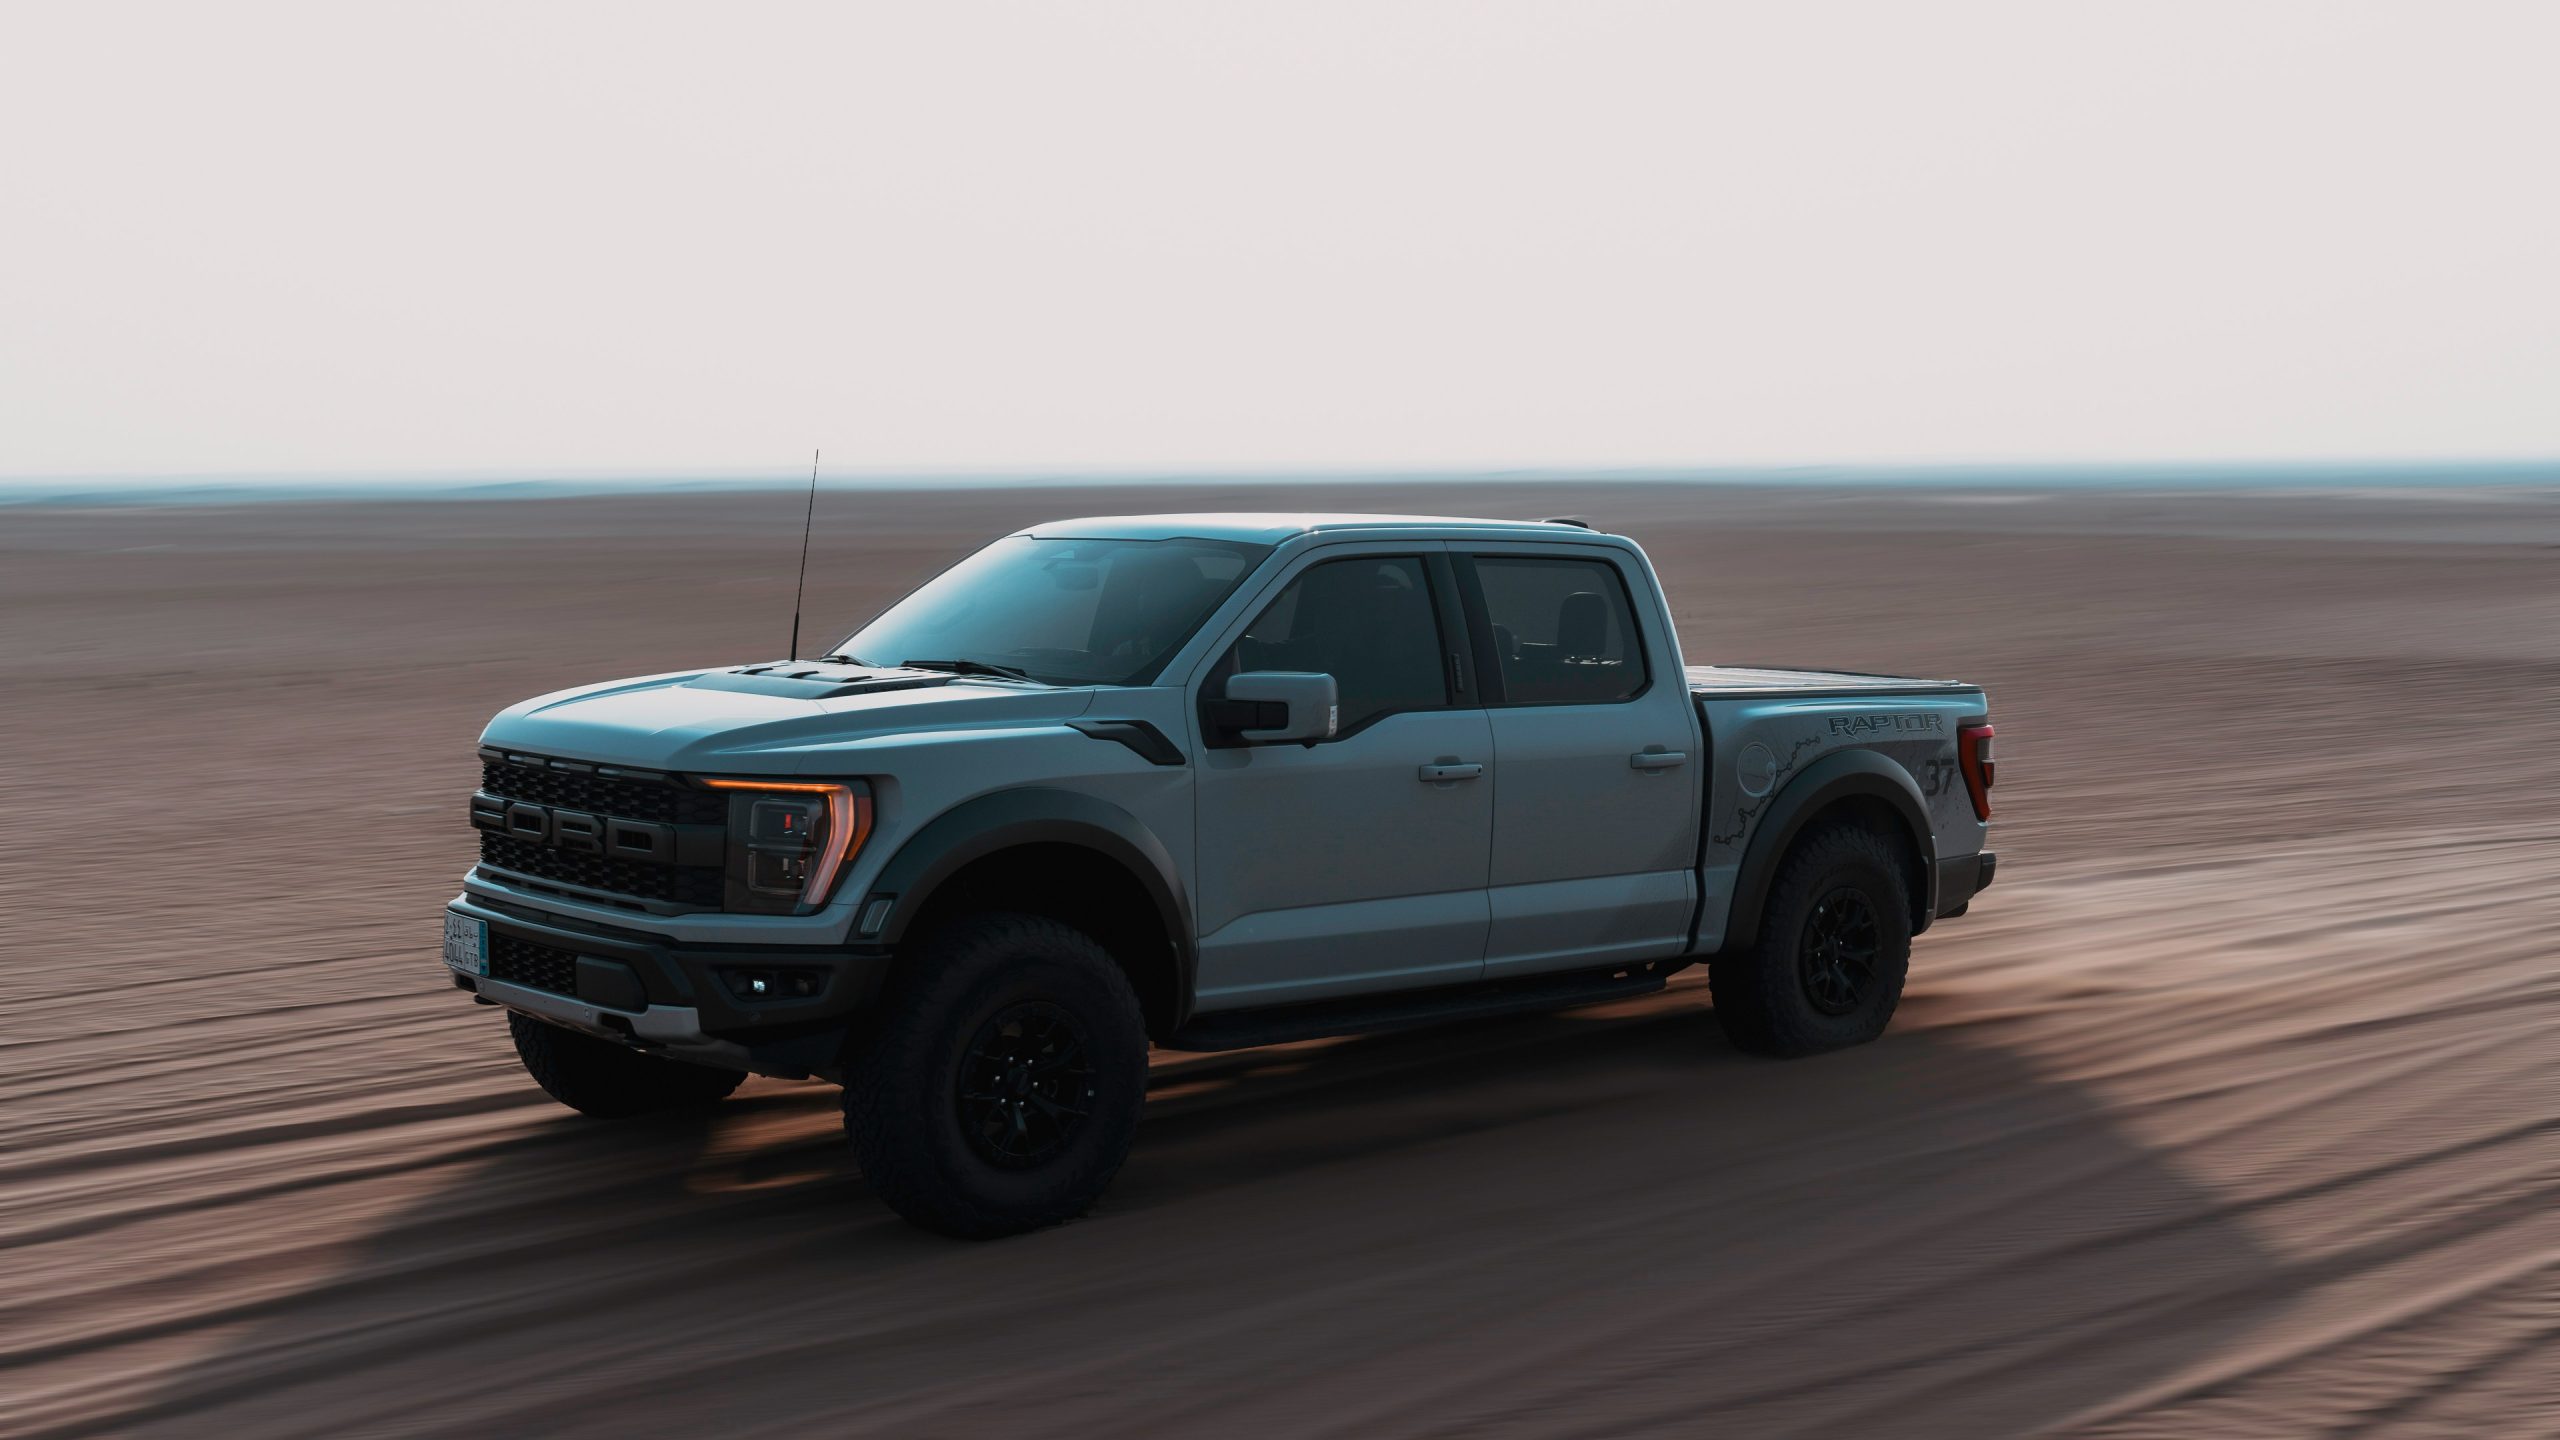
1. Ford F-150 Raptor
The Ford F-150 Raptor is a popular performance pickup designed for drivers who want powerful acceleration, advanced suspension, and serious off-road capability. Its high-performance engineering makes it attractive to truck enthusiasts, but these same features can influence insurance underwriting.
Insurers generally consider vehicle replacement value, engine performance, repair expenses, and the likelihood of expensive claims when calculating premiums. A Raptor can therefore cost more to insure than a conventional pickup with similar dimensions.
Performance is an important consideration when evaluating insurance risk. The Raptor is equipped with a powerful engine and specialised suspension components that support demanding driving conditions. These systems can be costly to repair after an accident, particularly when damage affects specialised equipment.
Insurance companies may pay close attention to repair estimates, replacement parts, and the availability of qualified repair facilities when assessing a vehicle with advanced mechanical components.
The vehicle’s intended use can also influence its insurance classification. Some owners purchase the Raptor for everyday commuting, while others regularly drive it on trails, construction sites, or rough terrain.
Off-road use can introduce additional risks, including underbody damage, suspension problems, and collisions with obstacles. Standard automobile policies may not cover every type of off-road incident, making it important for owners to understand their policy exclusions and additional coverage requirements.
Another consideration is the replacement cost of specialised components. Performance tyres, upgraded suspension systems, electronic equipment, and body panels can increase repair bills.
When an accident involves several expensive components, the insurer may face a substantially higher claim than it would for a basic work truck. Vehicle modifications can create further complications if owners fail to disclose them when purchasing coverage.
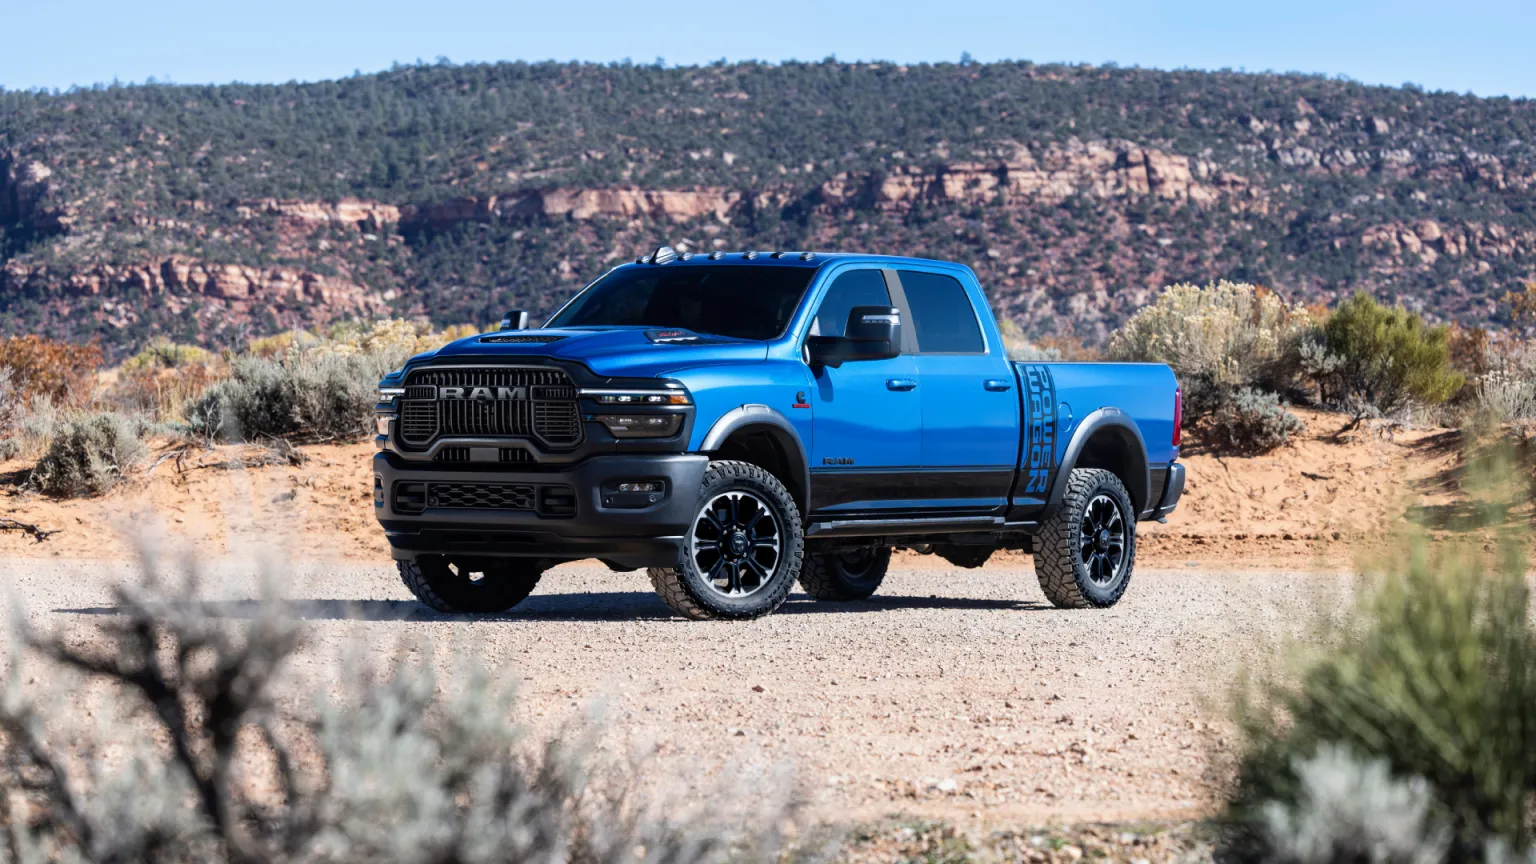
2. Ram 2500 Heavy-Duty Diesel
The Ram 2500 is designed for demanding work, towing, and hauling. Its heavy-duty construction makes it suitable for contractors, agricultural businesses, recreational towing, and commercial operations. Diesel versions can deliver substantial torque and impressive towing capability.
However, their purchase prices, mechanical complexity, and potential repair expenses may influence insurance costs. Insurers often assess how frequently these trucks are used and whether they regularly carry heavy loads.
Diesel engines are built to handle demanding workloads, but their maintenance and repair requirements can be expensive. Fuel injection systems, turbochargers, emissions equipment, and other specialised components may require costly servicing.
Following a collision, damage to these systems can increase repair estimates. Insurance providers may therefore consider replacement parts and labour costs when evaluating coverage for heavy-duty diesel pickups.
Towing is another important underwriting consideration. A Ram 2500 may regularly pull equipment trailers, recreational vehicles, boats, or construction machinery. Towing introduces additional exposure because an accident can involve both the truck and the attached trailer.
Depending on the circumstances and policy wording, damage to the trailer or its contents may require separate coverage. Owners should check whether their policy addresses trailer liability and physical damage.
Commercial usage can further affect premiums. A truck used for personal transportation may qualify for different insurance arrangements than a vehicle operating daily on construction sites or transporting business equipment.
Frequent driving, multiple operators, heavy loads, and long-distance journeys can change the insurer’s assessment. Business owners should provide accurate information about their operations rather than relying on a personal-use policy that may not match the vehicle’s actual purpose.
People considering a Ram 2500 should calculate ownership expenses beyond the monthly vehicle payment. Insurance, maintenance, tyres, fuel, and registration all contribute to long-term costs.
Requesting commercial and personal-use quotes where appropriate can help establish a realistic budget. Regular servicing, responsible towing practices, qualified drivers, and properly documented equipment can also help owners present a stronger insurance application.
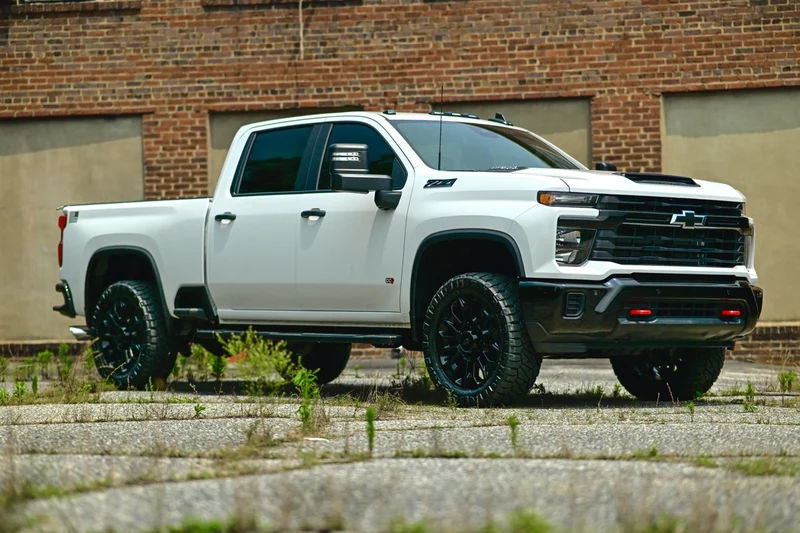
3. Chevrolet Silverado 2500HD
The Chevrolet Silverado 2500HD is another heavy-duty pickup commonly selected for demanding professional and personal applications. Its strong towing capacity, durable construction, and available diesel powertrain make it useful for contractors, farmers, and recreational vehicle owners.
However, a truck designed for heavy workloads can have different insurance considerations from an ordinary passenger vehicle. Its size, replacement value, and operating environment may influence how providers calculate premiums.
Repair expenses can become significant when a heavy-duty truck experiences collision damage. Large body panels, specialised suspension systems, advanced driver assistance technology, and expensive powertrain components can contribute to higher repair estimates.
Modern pickup trucks also contain electronic sensors and cameras that may need recalibration after certain repairs. These additional requirements can increase the total cost of restoring a damaged vehicle.
The Silverado 2500HD is frequently used for towing and transporting equipment. Its working capabilities are valuable, but the additional weight and length of a trailer can create more demanding driving conditions.
Tight turns, reversing, highway merging, and braking require attention and experience. Insurance companies may consider the truck’s operating history and the driver’s experience when reviewing applications involving regular towing.
Vehicle value is another factor. Higher trim levels and optional packages can increase the cost of replacing a damaged or stolen pickup. Owners who install specialised toolboxes, commercial equipment, upgraded wheels, or other accessories should determine whether these additions are included in their policy.
Some policies have limits on aftermarket equipment, while business property carried inside a vehicle may require separate protection.
Silverado 2500HD owners can manage insurance expenses through careful vehicle selection and responsible operation. Choosing equipment that matches actual requirements can prevent unnecessary increases in replacement value.
Maintaining service records, checking tyre condition, following towing recommendations, and ensuring drivers receive appropriate training can support safer operations. Getting several insurance quotations before purchasing is particularly useful for buyers planning to use the vehicle commercially.
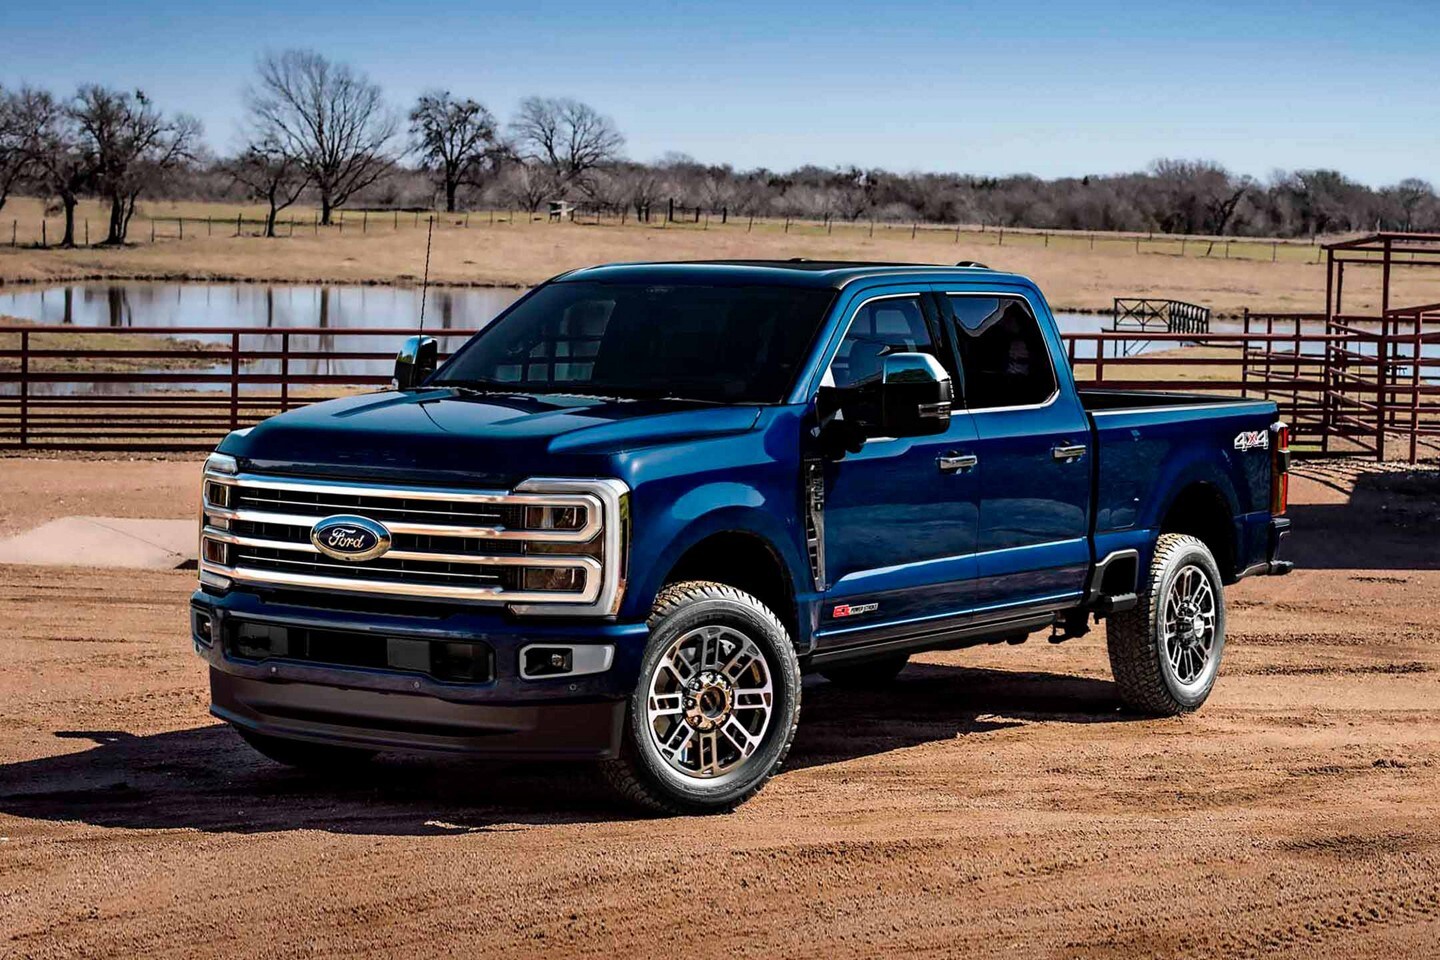
4. Ford F-350 Super Duty
The Ford F-350 Super Duty is built for substantial towing and payload requirements. It is available in configurations intended for demanding professional applications, including construction, agriculture, and specialised transport.
Some versions feature dual rear wheels, larger equipment packages, and powerful diesel engines. These characteristics make the F-350 capable, but they can also affect its insurance profile through higher replacement values and more expensive repair requirements.
Vehicle dimensions and weight are important considerations for insurers. A larger pickup can require more space to manoeuvre and park, particularly in crowded commercial environments. Drivers must account for wider turning circles, longer stopping distances under certain loaded conditions, and additional blind spots.
Accidents involving large vehicles can also result in substantial property damage. These factors may influence underwriting decisions, particularly when the truck operates frequently in urban or industrial locations.
The cost of repairing an F-350 can vary considerably depending on its configuration. Diesel powertrains, advanced towing technology, specialised bodywork, and electronic systems may increase labour and replacement expenses.
Higher trim levels can introduce additional equipment that is expensive to replace. When an insurer calculates potential claim costs, these details can matter as much as the vehicle’s basic classification.
Commercial use presents further considerations. Many F-350 trucks spend considerable time transporting tools, materials, livestock equipment, or heavy trailers. Some operate across several locations each day, increasing annual mileage and exposure to traffic incidents.
Insurers may ask about operating territory, business activities, employee drivers, and the type of cargo transported before determining appropriate coverage.
Owners should select an insurance policy that reflects the truck’s actual responsibilities. A contractor using an F-350 for business purposes may need commercial vehicle coverage, while a private owner may have different requirements.
Appropriate liability limits, physical damage protection, trailer coverage, and equipment protection deserve attention. Driver training and routine maintenance can also reduce preventable incidents and help control long-term ownership expenses.
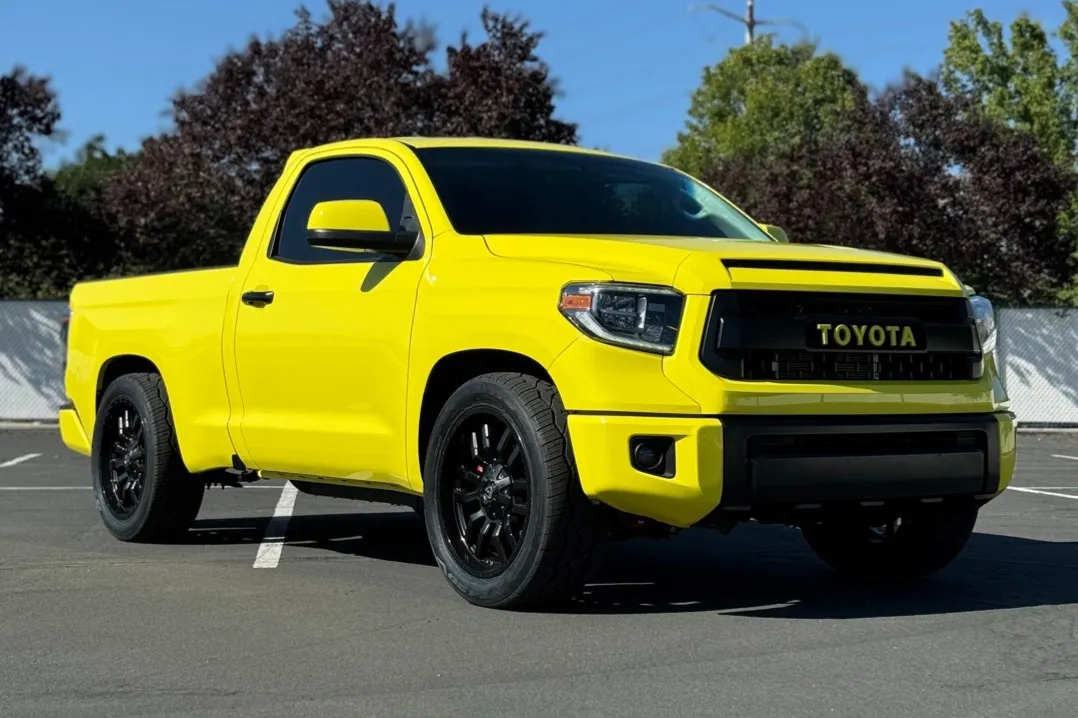
5. Toyota Tundra TRD Pro
The Toyota Tundra TRD Pro combines full-size pickup capability with specialised off-road equipment. Its design appeals to buyers looking for a truck that can handle everyday driving, outdoor activities, and challenging terrain.
The TRD Pro package includes performance-oriented features that can increase the vehicle’s purchase and replacement value. Insurance companies may consider these costs when determining comprehensive and collision premiums.
Advanced equipment can influence repair expenses. Specialised suspension components, off-road tyres, protective body parts, and electronic systems may cost more to replace than standard equipment.
If an accident damages several components at once, repair estimates can rise quickly. Insurers also consider the availability of replacement parts and the labour required to restore a vehicle to its original condition.
Off-road activity is particularly relevant for this model. Drivers may take the Tundra TRD Pro onto unpaved roads, rocky trails, and remote locations. These environments can create risks that are less common during ordinary highway travel.
Damage from rocks, uneven surfaces, water crossings, and collisions with obstacles may not receive the same treatment under every insurance policy. Owners should check their coverage carefully before using the vehicle outside normal road conditions.
The truck’s market value can also influence premiums. Special editions and desirable equipment packages may have higher replacement costs than basic configurations.
Depending on local theft patterns and vehicle security features, comprehensive insurance costs can vary. Owners should consider approved anti-theft systems, secure parking, and appropriate tracking equipment where available.
Before purchasing a Tundra TRD Pro, buyers should obtain quotations for the exact trim and equipment package. They should also ask whether aftermarket accessories are covered and whether off-road damage is excluded.
Maintaining accurate service records and avoiding unnecessary modifications can make insurance arrangements easier to manage. A performance-oriented pickup can remain practical and affordable when its operating conditions and coverage needs are properly understood.
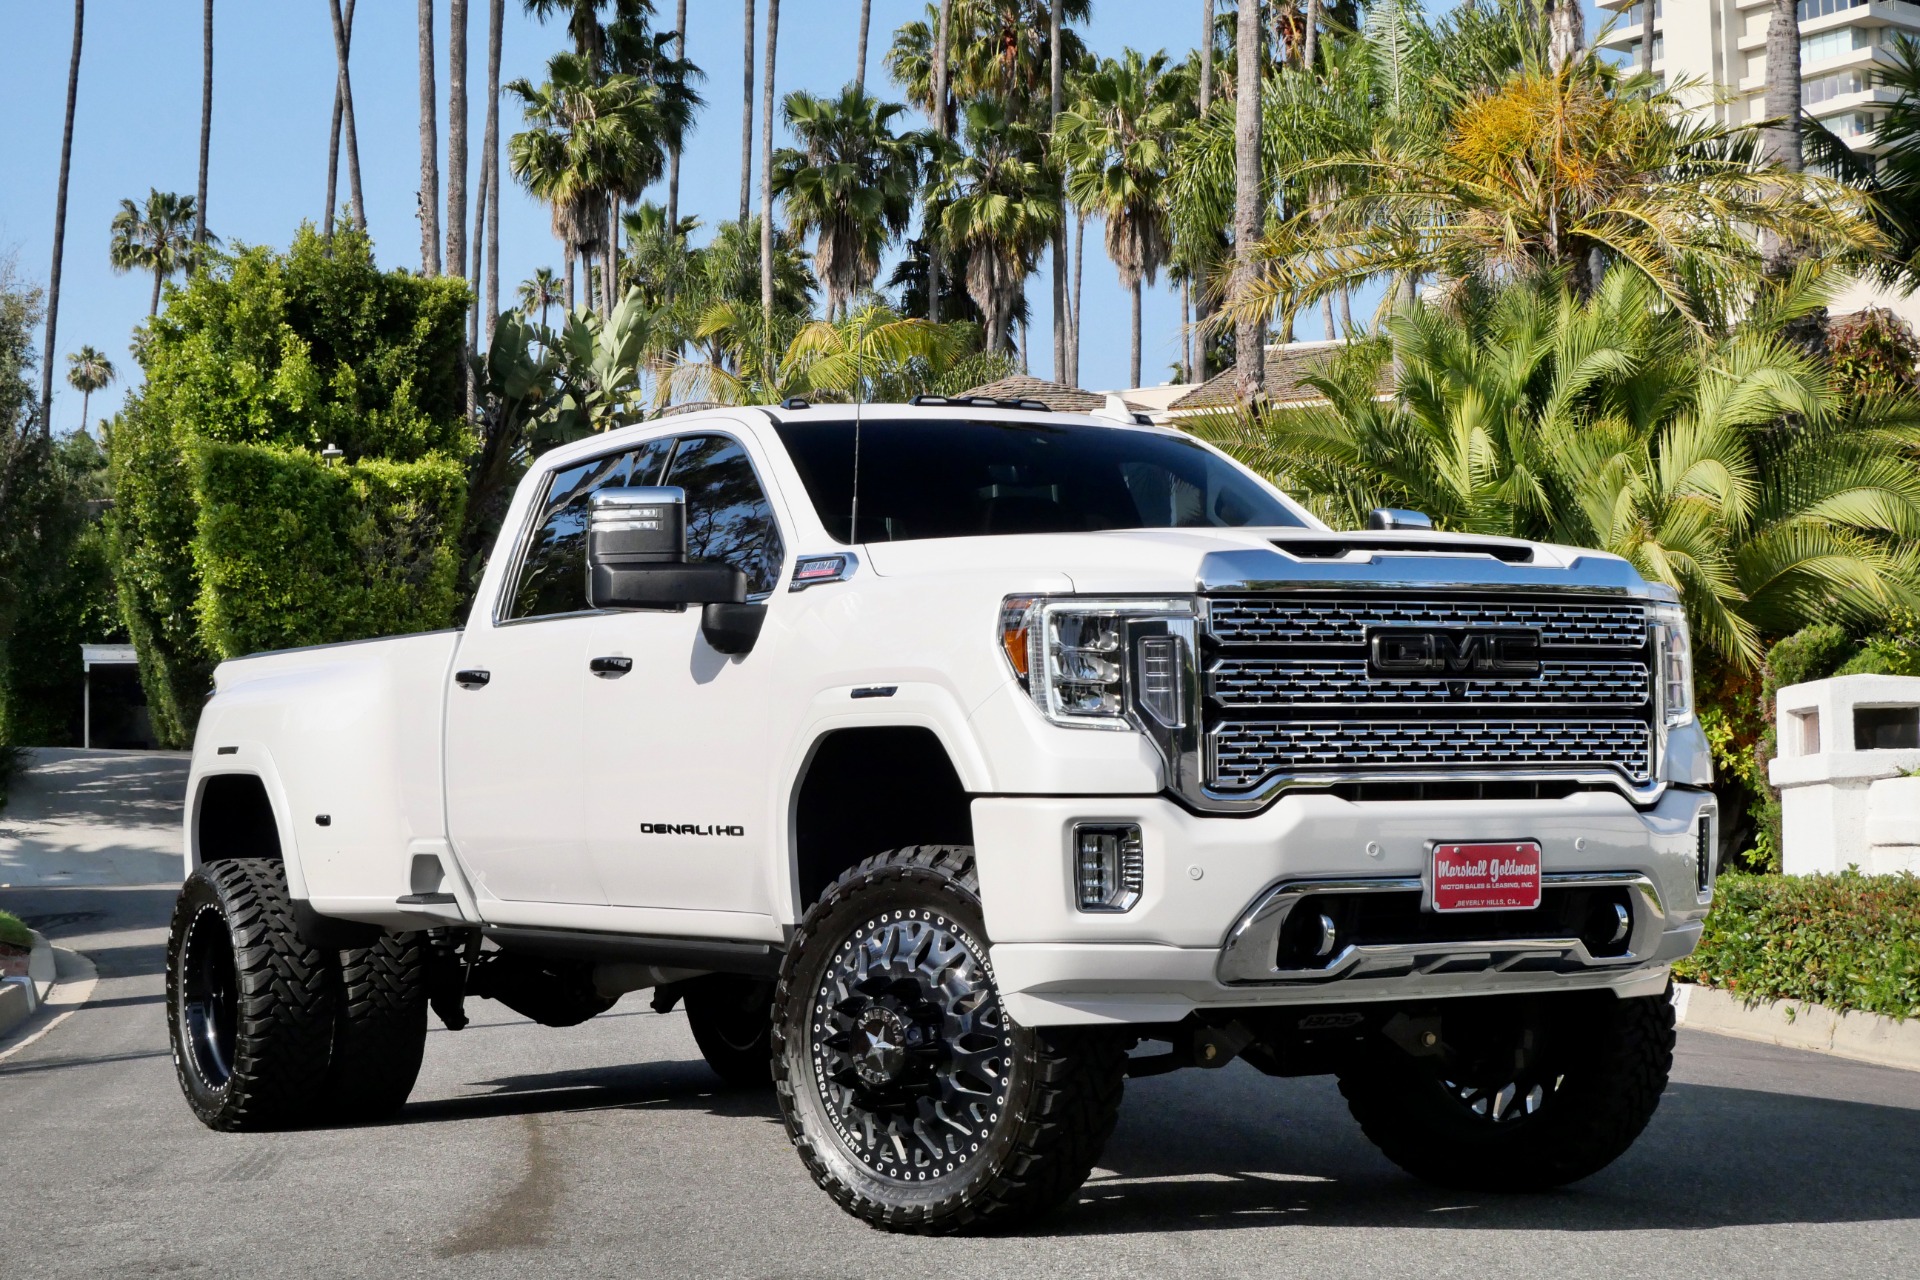
6. GMC Sierra 3500HD
The GMC Sierra 3500HD is designed for serious towing and hauling responsibilities. Its available configurations serve commercial operators, agricultural businesses, and individuals who regularly transport heavy equipment.
Higher specifications and premium trim levels can increase the truck’s value, while diesel powertrains and specialised mechanical components can influence repair costs. These factors may contribute to higher insurance quotations compared with lighter, less expensive pickups.
Heavy-duty trucks can face demanding operating conditions. Construction sites, agricultural properties, industrial facilities, and busy highways expose vehicles to different accident risks.
Dust, debris, uneven surfaces, and frequent loading activities can contribute to wear and accidental damage. Insurers may ask where the truck operates and how regularly it is exposed to these conditions before establishing suitable coverage.
The Sierra 3500HD can also be configured for specialised commercial tasks. Depending on its equipment, it may carry heavy loads, tow trailers, or support business operations.
These activities can require additional liability protection. An accident involving a loaded commercial vehicle may create more complicated claims involving other motorists, property, trailers, or transported equipment.
Repair costs deserve particular attention. Heavy-duty diesel components, advanced electronics, specialised wheels, and large body panels can be expensive.
A vehicle that spends substantial time away from major repair centres may also experience longer repair periods if replacement parts are difficult to obtain. The total financial impact of an accident can therefore extend beyond the immediate repair bill.
Sierra 3500HD owners should discuss their working arrangements with an insurance professional. Providing accurate information about towing, cargo, annual mileage, and driver experience helps prevent coverage problems.
Businesses should also consider whether hired or employee drivers are properly insured. Routine inspections, safe loading practices, and appropriate maintenance can help reduce avoidable claims and support reliable operations.
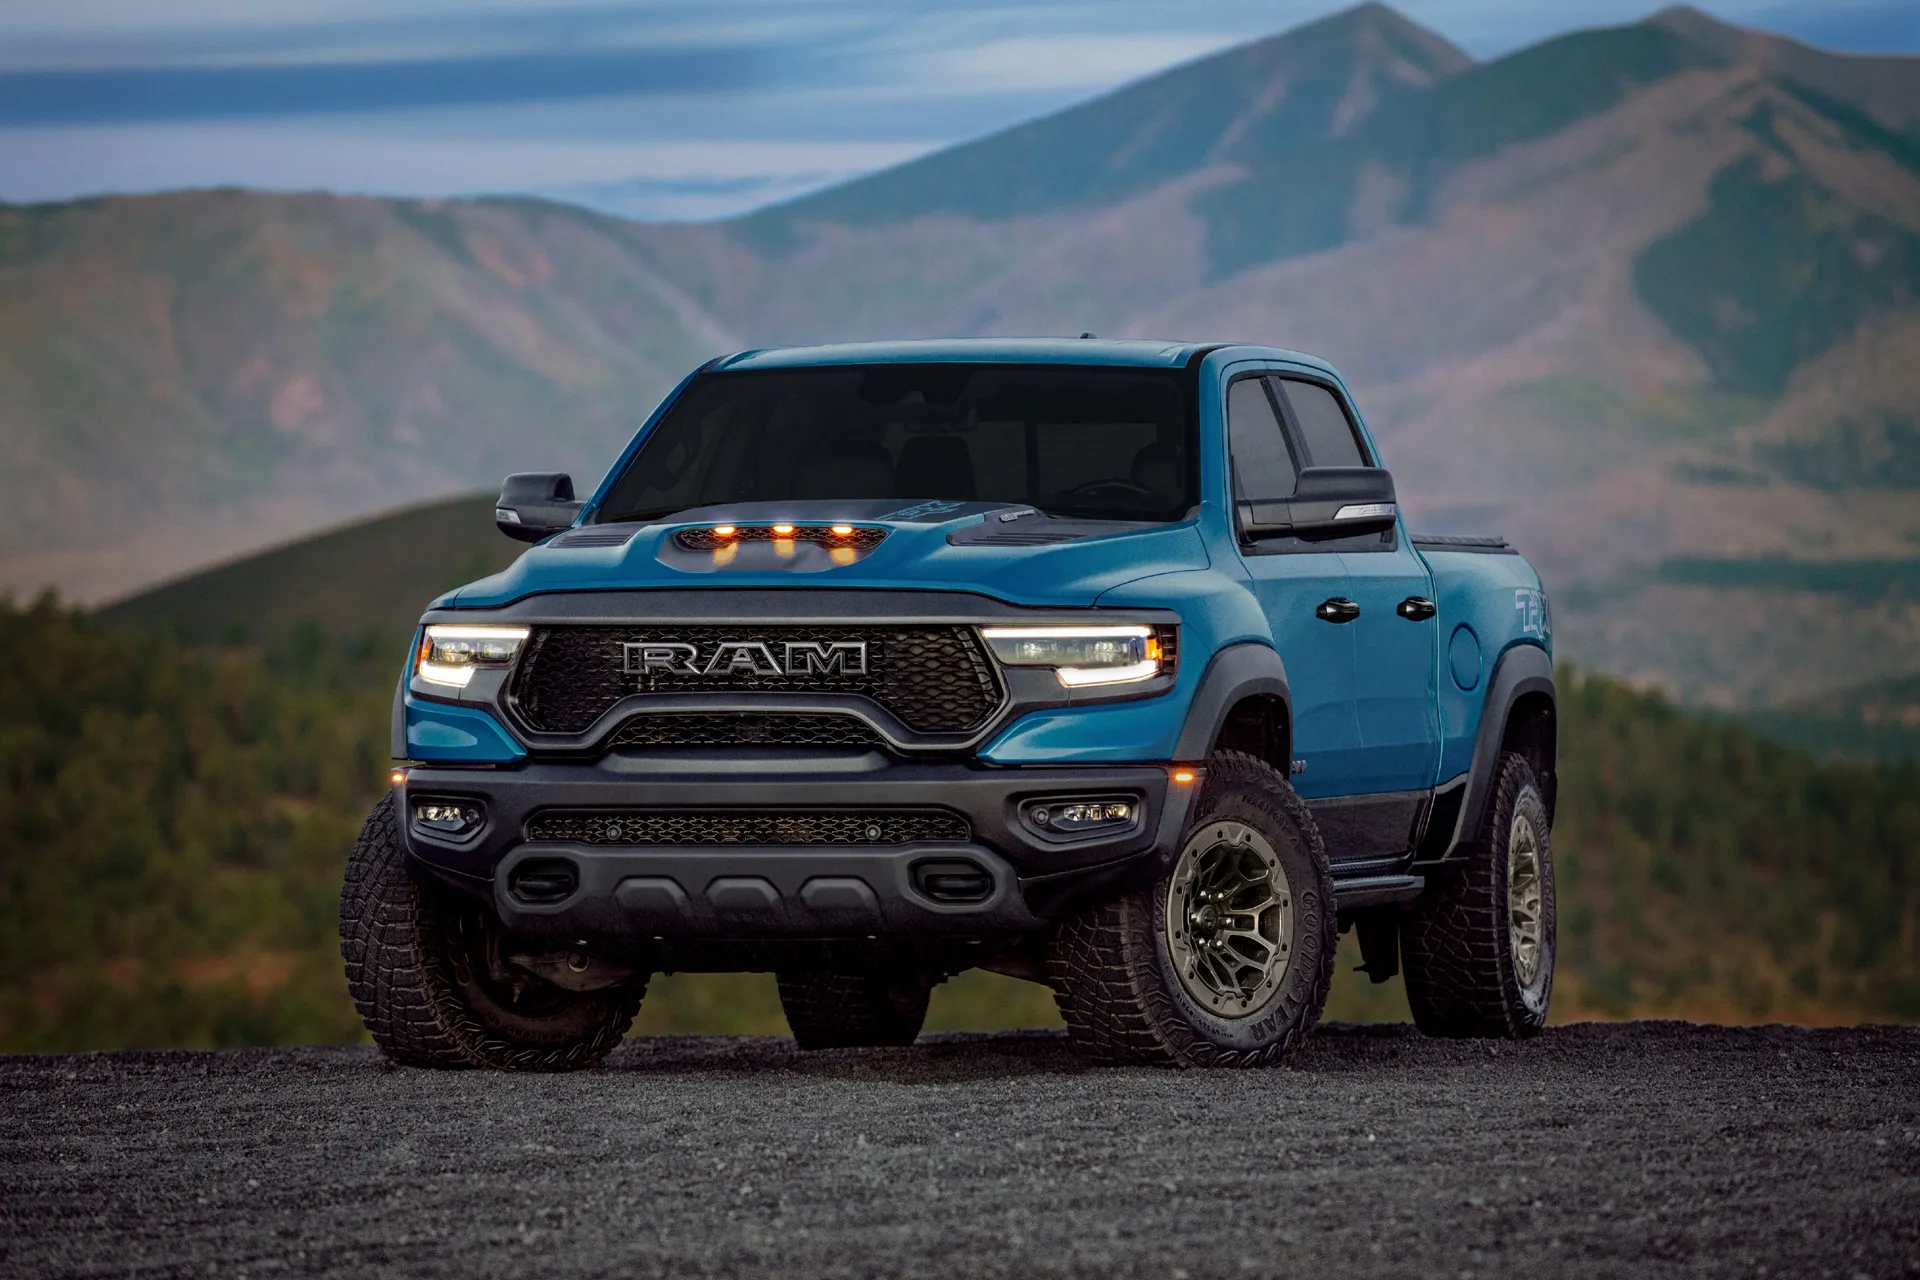
7. Ram 1500 TRX
The Ram 1500 TRX is known for its high-performance engineering and powerful supercharged V8 engine. It was developed to combine pickup utility with exceptional acceleration and off-road ability.
This performance-focused design can make it more expensive to insure than a standard light-duty pickup. Insurers may examine engine specifications, replacement value, repair costs, and claims associated with comparable performance vehicles.
Powerful acceleration can influence risk assessments because vehicle performance is only beneficial when drivers use it responsibly. Rapid acceleration, high speeds, and aggressive driving increase the potential consequences of a traffic incident.
An insurer may review driving history, previous claims, and other available underwriting information when deciding whether to offer coverage and at what price.
The TRX also contains specialised mechanical and electronic equipment. Performance suspension, large tyres, advanced cooling systems, and specialised drivetrain components can increase maintenance and repair expenses.
Collision damage involving these systems may require specialist attention. A shortage of replacement components or qualified repair facilities can also extend the time needed to return the truck to service.
Vehicle theft and replacement expenses may be additional considerations. High-value performance pickups can attract attention from thieves, particularly in areas where demand for expensive vehicle parts is strong.
Comprehensive coverage can help protect against covered theft losses, but the premium may depend on the vehicle’s location, security equipment, and local claim experience. Owners should ask insurers about available security-related discounts.
Anyone buying a used or new TRX should compare insurance costs before signing a purchase agreement. It is also important to maintain the vehicle according to manufacturer recommendations and avoid undocumented modifications.
Owners should review policy limits, deductibles, and exclusions rather than selecting coverage based only on the lowest advertised premium. Responsible driving and appropriate security measures can help manage ownership expenses.
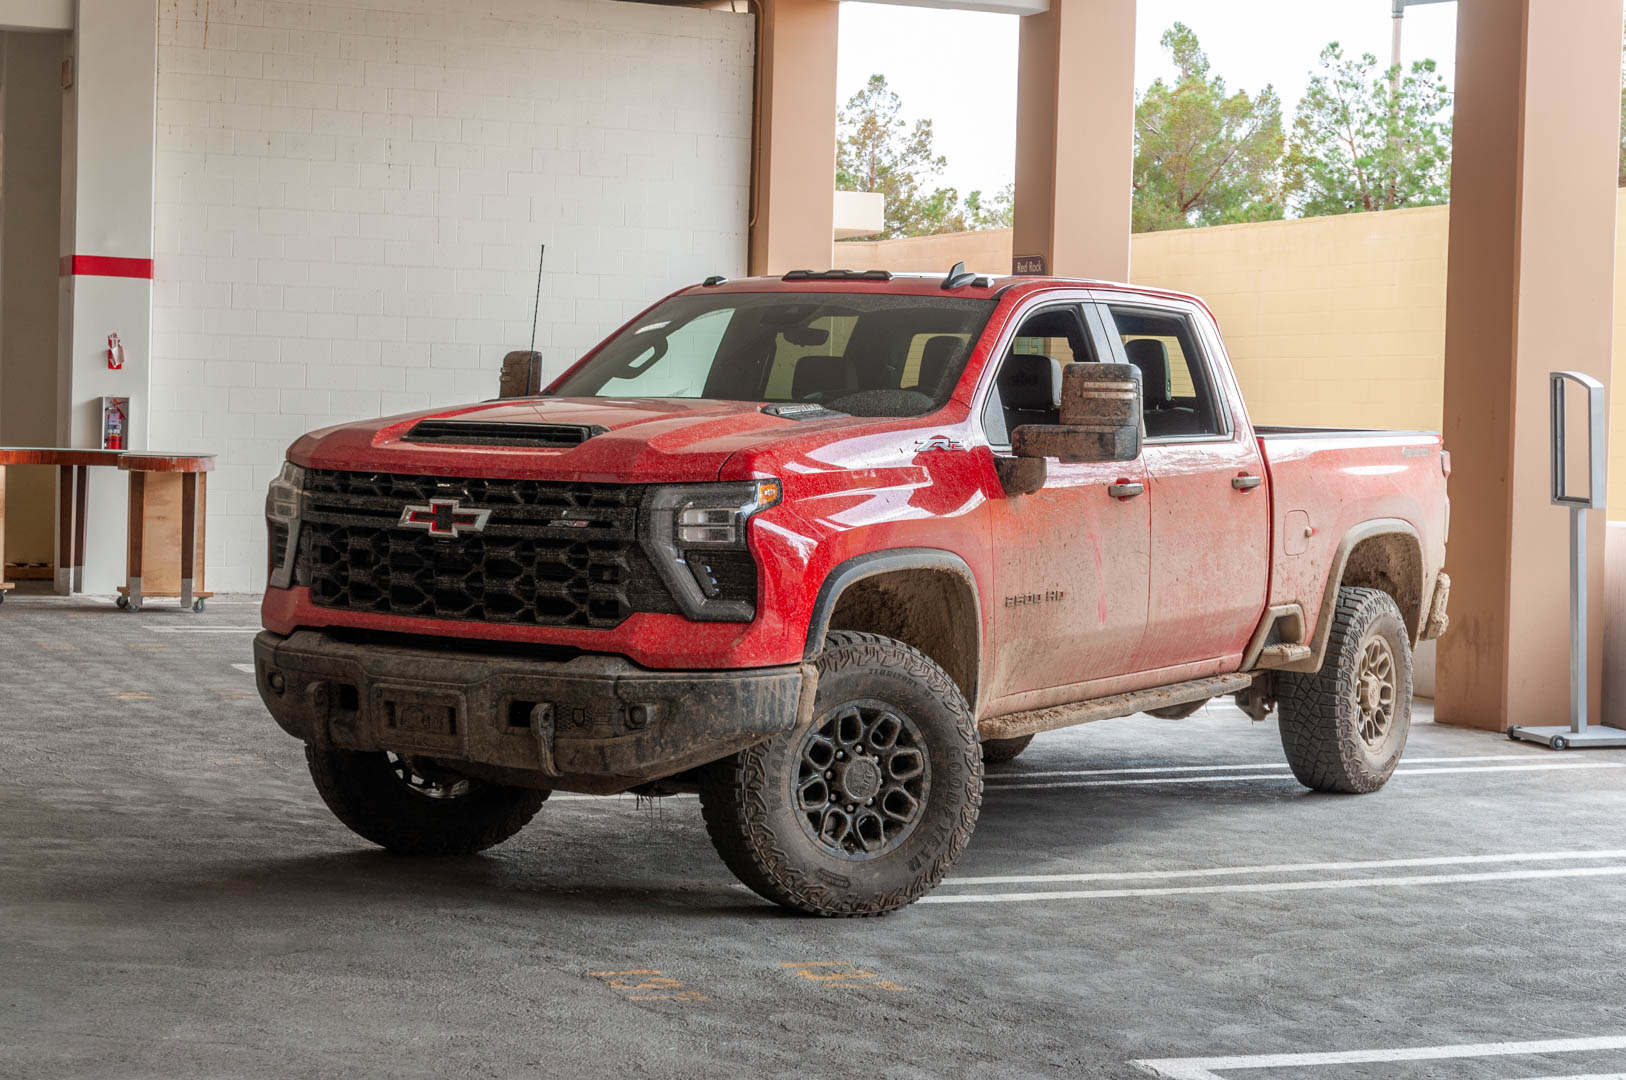
8. Chevrolet Silverado ZR2
The Chevrolet Silverado ZR2 is a specialised pickup designed for drivers who want enhanced off-road performance without giving up the everyday usefulness of a full-size truck.
Its suspension upgrades, protective components, and specialised tyres distinguish it from standard Silverado models. These features can increase purchase prices and replacement expenses, which may affect insurance premiums.
Off-road equipment can be expensive to repair when damaged. Suspension components, specialised dampers, underbody protection, and larger tyres can add to the cost of restoring a vehicle after an incident.
Even relatively minor collisions may require the replacement of several specialised parts. Insurers generally evaluate the likely cost of repairing a vehicle rather than relying solely on its original purchase price.
The vehicle’s intended operating environment is another factor. Owners who regularly travel on unpaved roads or challenging trails may face risks that are less common for trucks used primarily on highways.
Underbody impacts, damaged tyres, broken suspension components, and environmental hazards can create unexpected expenses. Insurance policies differ in how they handle off-road incidents, so buyers should review the terms before assuming every type of damage is covered.
Aftermarket modifications can further complicate insurance arrangements. Some owners install additional lighting, upgraded wheels, roof equipment, recovery accessories, or other specialised components.
These additions can increase replacement costs and may not automatically be included in a standard policy. Failure to disclose modifications could also create complications during a claim, depending on the policy conditions.
Silverado ZR2 buyers should obtain a quotation that reflects the precise model year, trim, and installed equipment. They should ask whether off-road use is covered and whether accessories require separate protection.
Keeping receipts for upgrades and following maintenance schedules can help document the vehicle’s condition and value. Careful driving and responsible trail use remain important parts of reducing avoidable insurance claims.
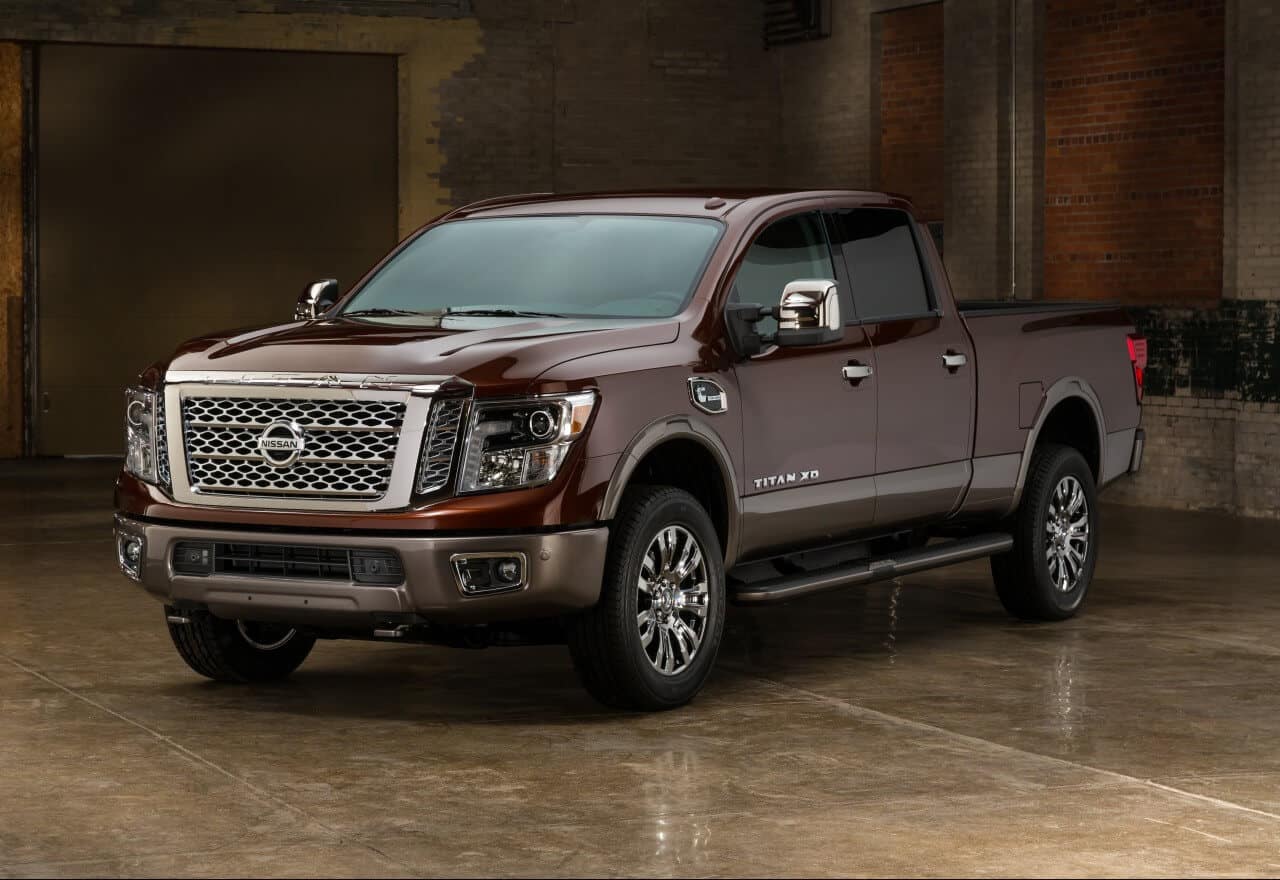
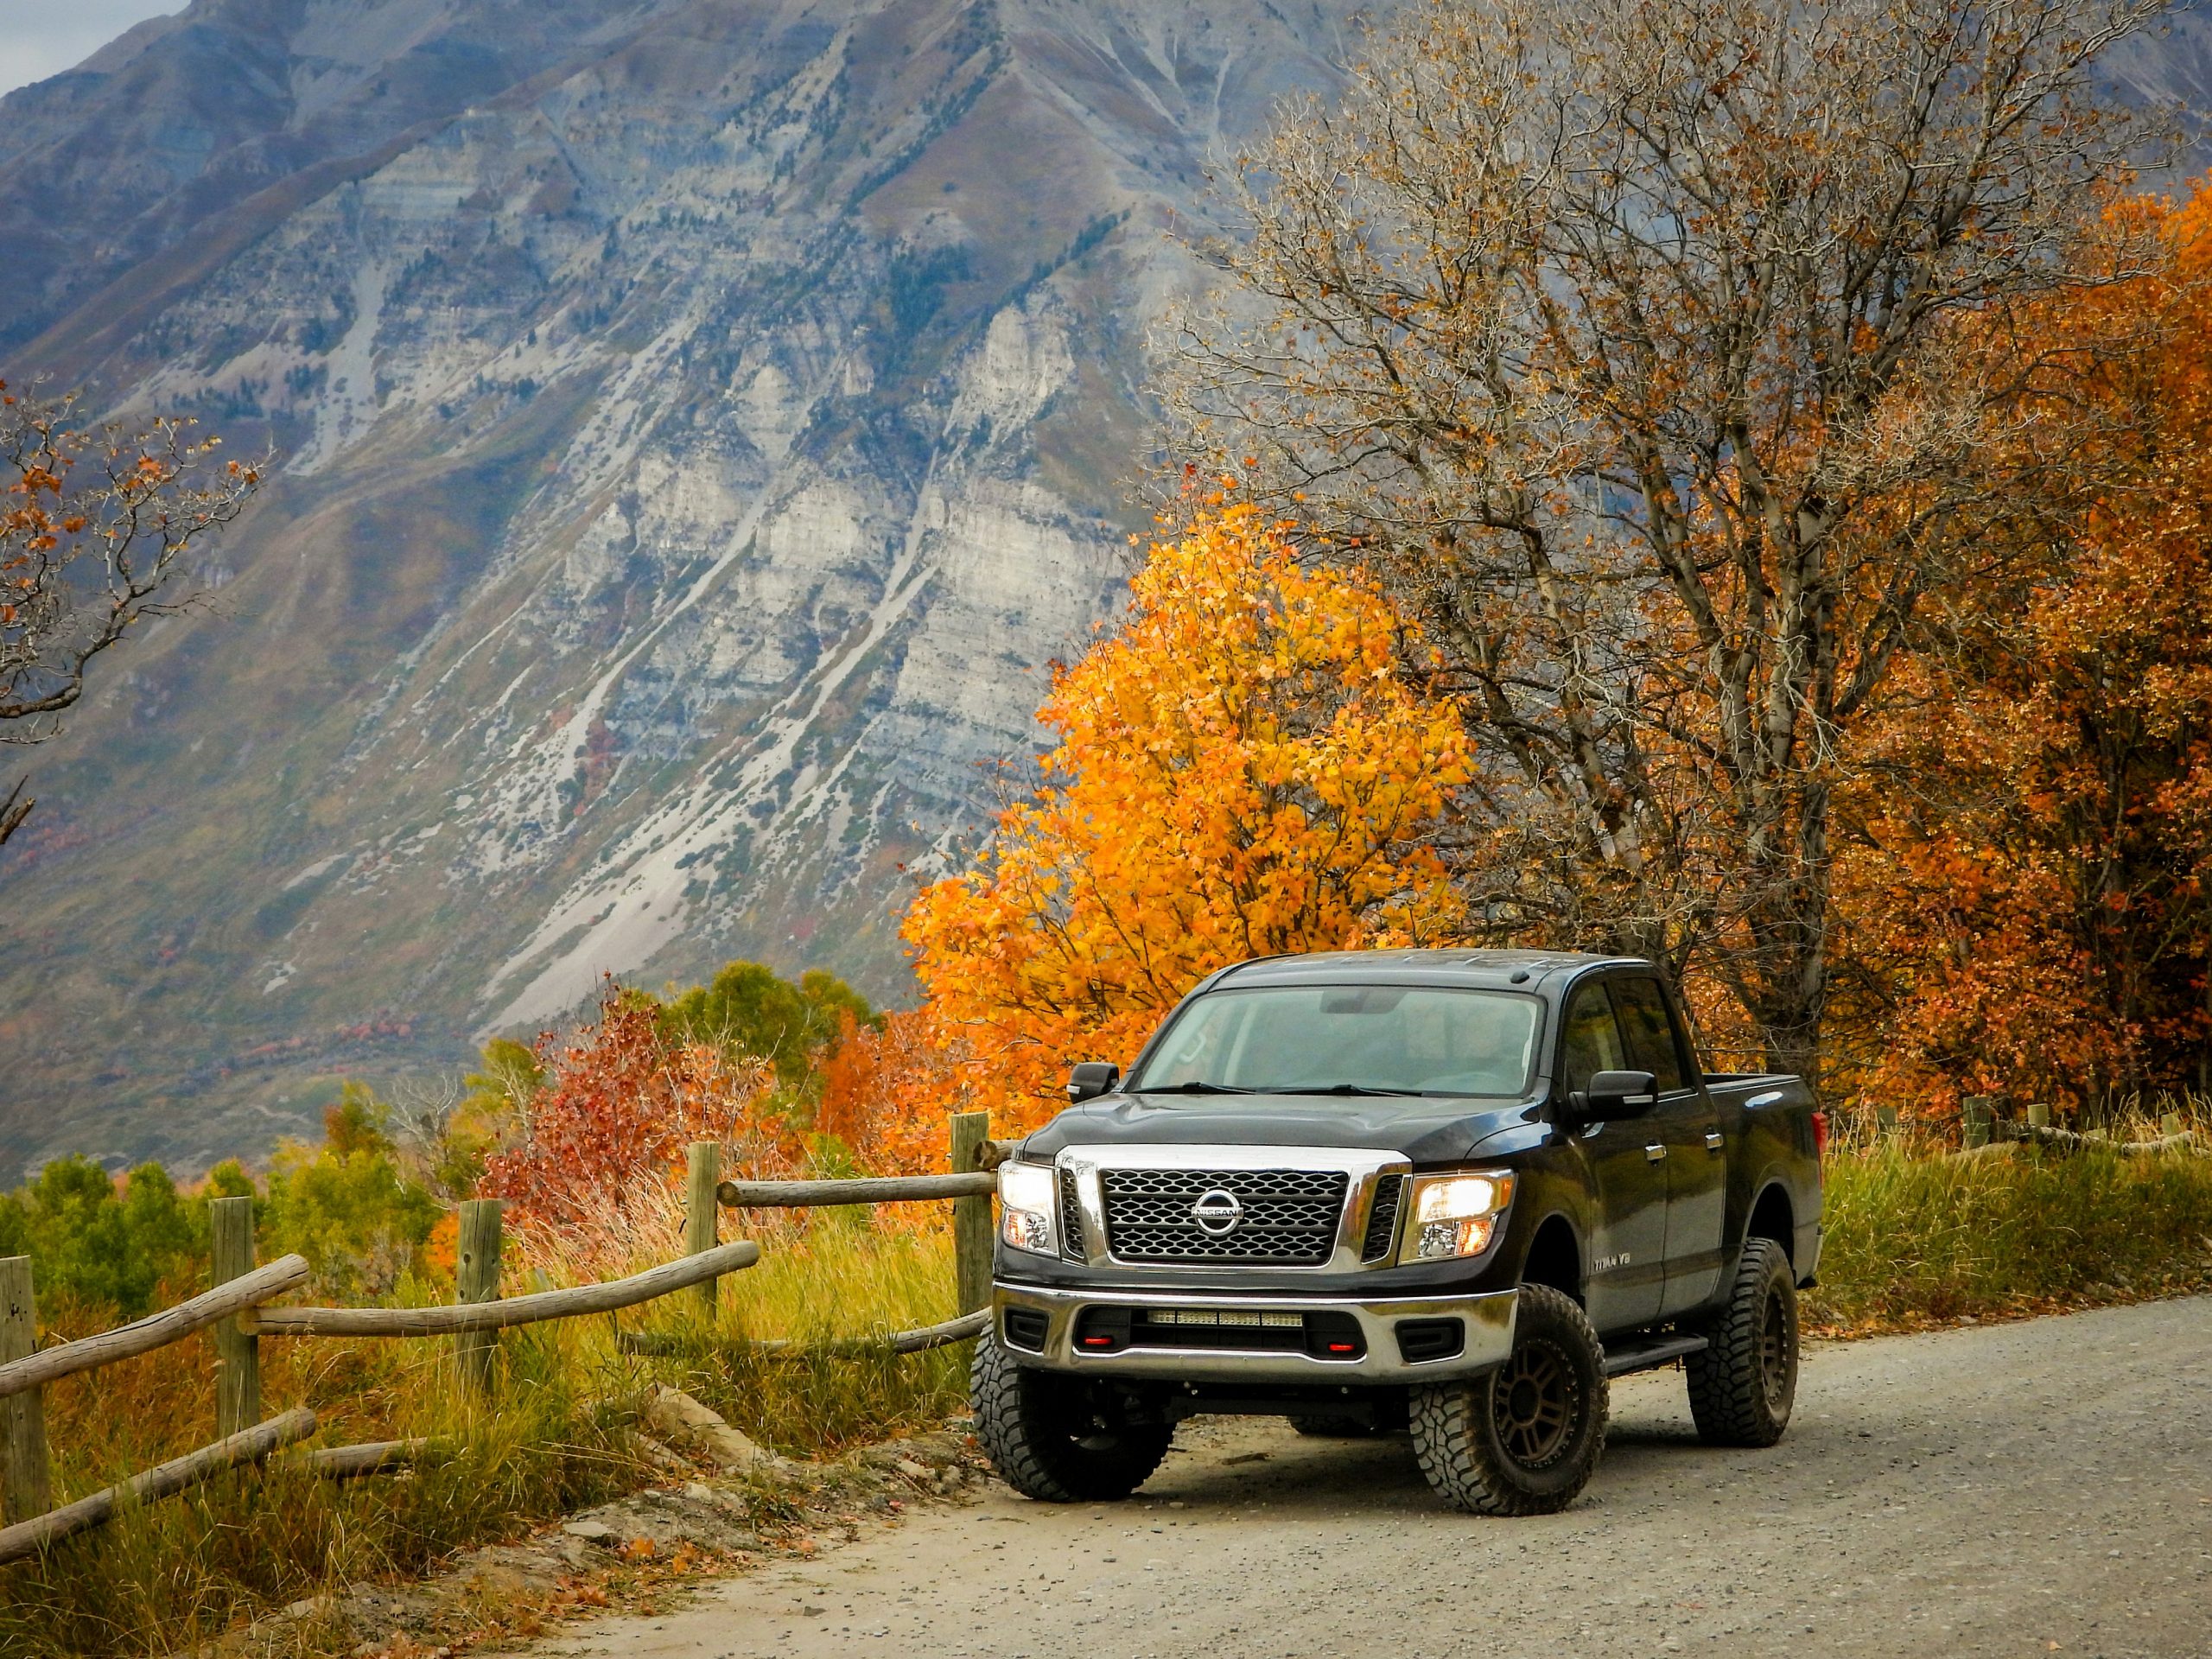
9. Nissan Titan XD
The Nissan Titan XD occupies a position between conventional light-duty pickups and larger heavy-duty models. Its construction and available equipment make it suitable for owners who need additional capability for towing and hauling.
Insurance considerations may include its vehicle value, engine configuration, replacement parts, and intended use. The availability of specialised components can also influence repair estimates.
Parts availability is an important subject for buyers considering used vehicles. Some models and configurations may have fewer replacement options than more widely sold alternatives.
When parts take longer to obtain, repair periods can increase. Depending on the vehicle’s age and condition, the insurer may also need to consider whether repairing it remains economically reasonable compared with its market value.
Vehicle age and mileage can have a significant influence on insurance decisions. An older Titan XD with extensive mileage may have a different claim profile from a newer, well-maintained example. Worn suspension components, ageing electrical systems, and mechanical problems can affect reliability.
While routine mechanical failure is generally treated differently from accidental damage under standard automobile policies, vehicle condition can still matter during underwriting and claim investigations.
The truck’s usage pattern also deserves attention. Some owners use it for occasional towing and personal transportation, while others operate it regularly for business purposes. Commercial driving may involve longer journeys, heavier loads, and multiple operators.
Insurers need accurate information about these activities to determine the correct policy type and appropriate liability limits.
Buyers should arrange a professional inspection before purchasing a used Titan XD. They should also request insurance quotations based on the vehicle identification details and intended usage.
Checking replacement part availability, maintenance history, and accident records can provide a clearer picture of future expenses. A well-maintained pickup with suitable insurance can remain a useful vehicle for personal or professional transportation.