Falling behind on car loan payments can create financial pressure, especially when a lender decides to repossess the vehicle. Many borrowers assume that losing their car ends their financial responsibility, but the situation can involve several additional charges.
Repossession costs may include towing, storage, administrative fees, legal expenses, and other recovery-related charges. These expenses can increase the outstanding loan balance and make repayment more difficult.
Understanding the costs associated with vehicle repossession helps borrowers prepare financially, review lender charges, and make informed decisions. Knowing what lenders may add to an overdue car loan can also prevent unexpected financial difficulties.
1. Vehicle Towing and Transportation Fees
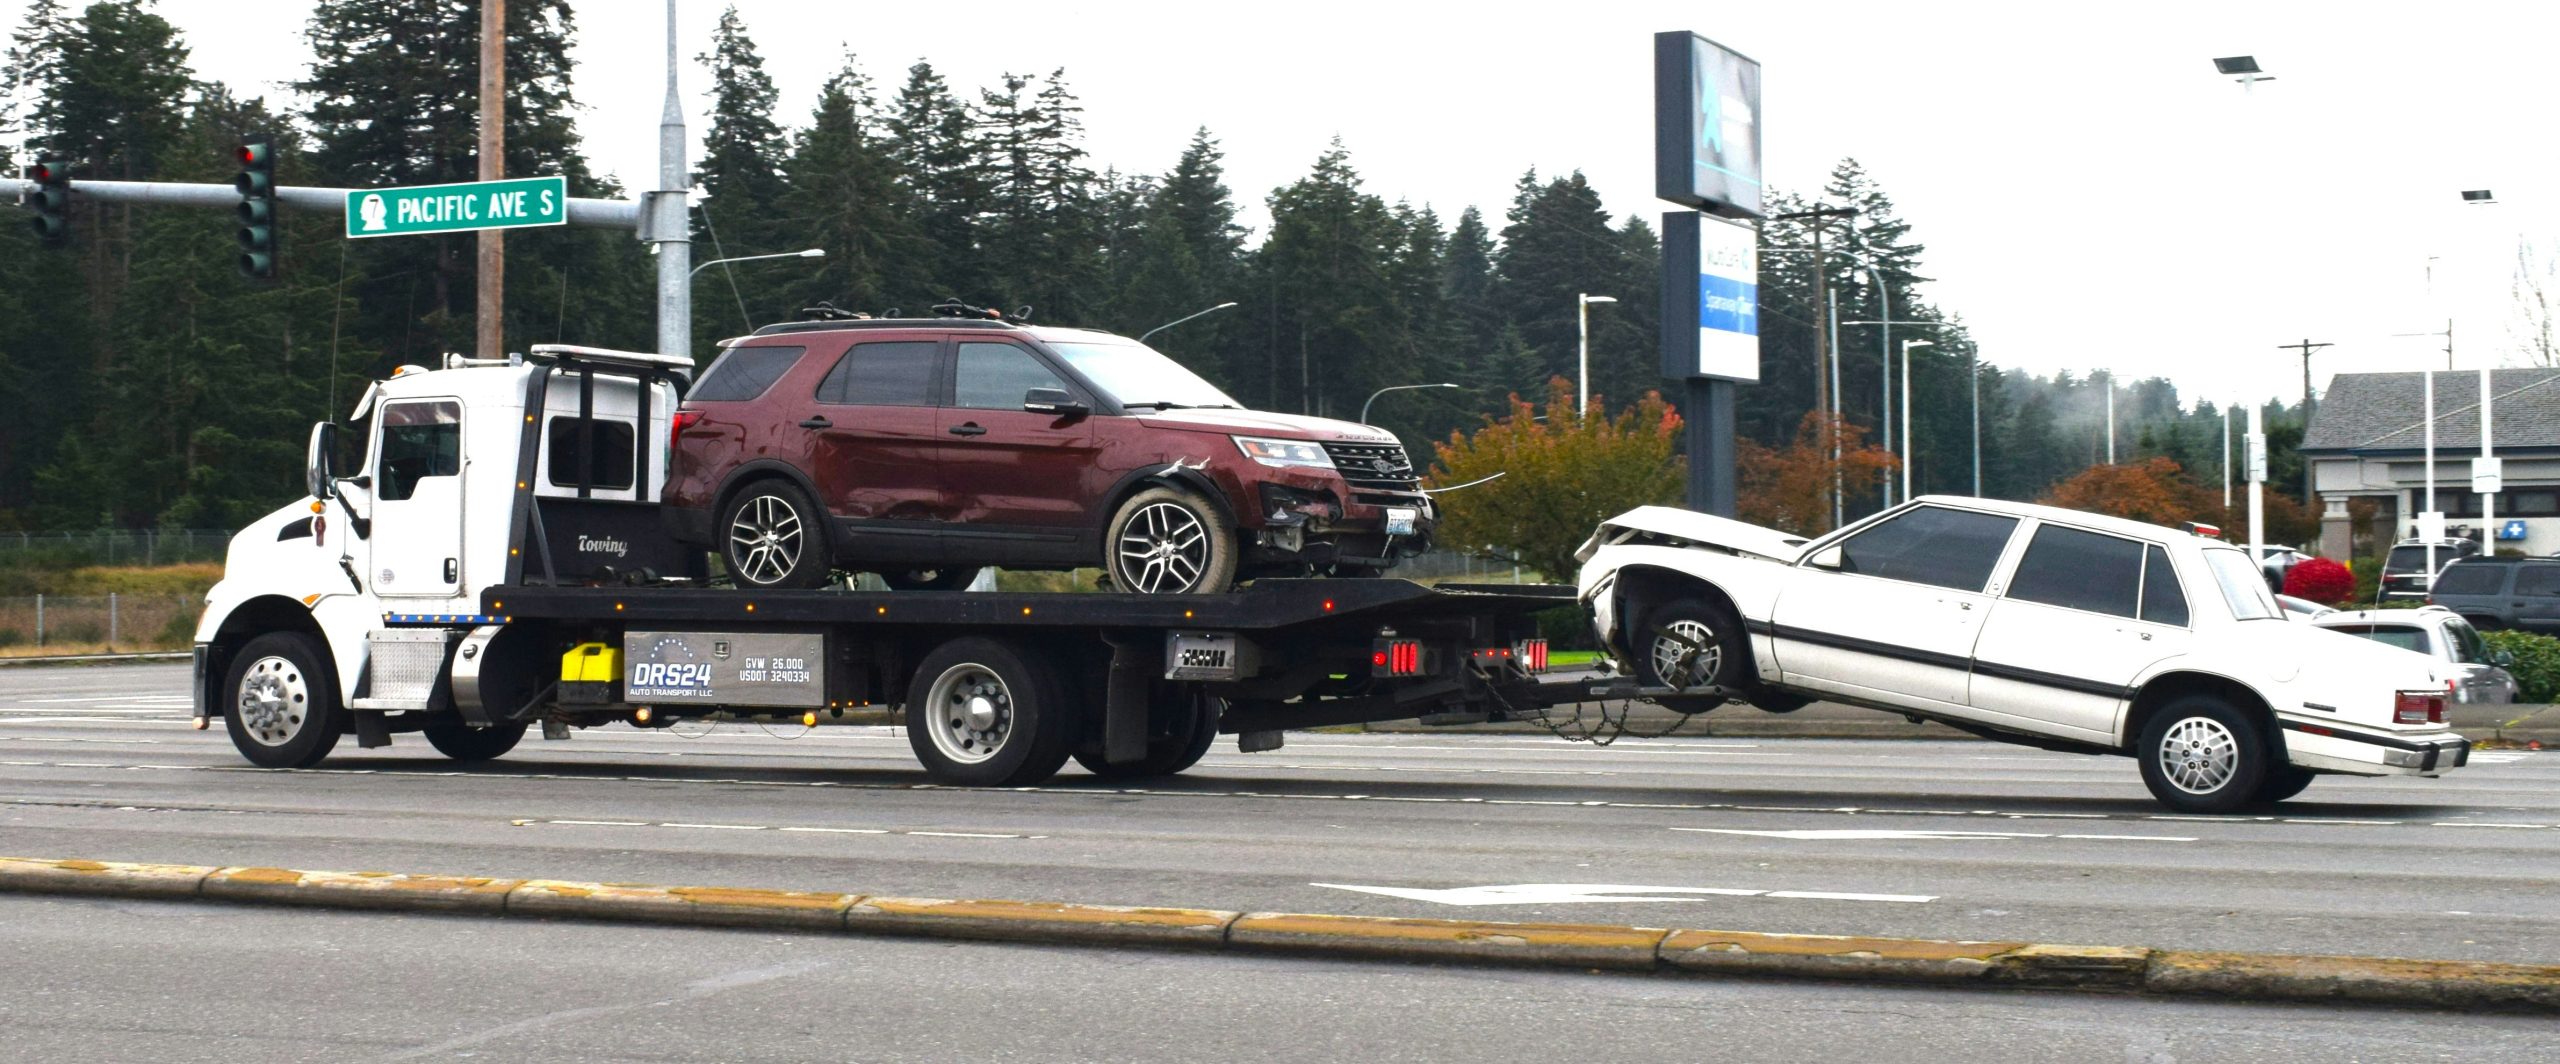
Vehicle towing is among the most common expenses added to an overdue car loan after repossession. When a lender hires a recovery company to collect a vehicle, the towing service usually charges for transporting it from its current location to an approved storage facility. The amount depends on the distance, vehicle condition, recovery method, and service provider.
The towing company may charge different rates depending on whether the vehicle is parked in a driveway, public parking area, residential complex, or roadside location. Vehicles located in restricted or difficult-to-access areas can require additional equipment or labor, increasing the final expense.
Some repossession companies use flat-rate pricing, while others calculate charges according to mileage and the time required to complete the recovery. Borrowers may find these fees included in the lender’s repossession statement or listed separately in the recovery company’s invoice.
Additional transportation charges may apply when a vehicle needs to be moved from the initial recovery location to a different storage facility. This can happen when the original lot becomes unavailable, or the lender transfers vehicles to a centralized auction location.
Specialized towing equipment may also increase the cost. For example, a damaged vehicle, an automobile with locked wheels, or a car parked in a narrow space may require a flatbed truck or additional recovery equipment.
Lenders generally seek reimbursement for reasonable and permitted towing expenses. However, borrowers should not automatically assume every amount listed on an invoice is valid. The charges should relate to the actual recovery process and comply with applicable laws and loan agreement terms.
Requesting an itemized towing invoice can help borrowers understand how the amount was calculated. They can review the transportation distance, service date, equipment charges, and any additional labor expenses to identify possible errors.
Understanding towing fees is important because these expenses can increase the amount owed even before the lender sells the repossessed vehicle. Reviewing the charges early can help borrowers identify unnecessary expenses and question amounts that appear excessive.
2. Vehicle Storage and Impound Fees
After repossession, lenders generally arrange for the vehicle to be kept at a designated storage facility or impound lot. These facilities charge for maintaining the vehicle until the lender decides whether to return it, sell it, or transfer it to an auction company.
Storage fees are commonly calculated daily. This means the longer a repossessed vehicle remains at the facility, the higher the accumulated charges may become. A delay in contacting the lender or completing the required paperwork can increase the total amount.
Different facilities have different pricing structures. Some charge a fixed daily amount, while others apply separate rates depending on vehicle size, storage conditions, and security arrangements.
Indoor storage may cost more than outdoor parking because it provides additional protection against weather and unauthorized access. Larger vehicles, including SUVs and pickup trucks, may also attract higher storage rates.
Impound facilities may charge additional fees for moving vehicles within their premises. These expenses can arise when a vehicle needs to be relocated for inspection, photography, maintenance, or preparation for an upcoming auction.
Borrowers should pay attention to the dates included in storage invoices. Incorrect arrival dates or billing periods can result in charges for days when the vehicle was not actually held at the facility.
Some jurisdictions have specific rules governing storage charges and the period for which a lender can recover them. The applicable requirements depend on local consumer protection laws and the terms of the financing agreement.
Requesting a complete storage statement helps borrowers understand how daily fees accumulated. It also provides an opportunity to question duplicate charges, incorrect dates, or expenses that do not comply with applicable regulations.
3. Repossession Agent and Recovery Service Fees
Lenders frequently work with professional repossession companies to recover vehicles when borrowers fail to meet their payment obligations. These companies employ trained agents who locate vehicles, arrange recovery, and transport them to designated facilities. Their services generally involve separate charges.
A repossession service fee may cover the agent’s time, vehicle recovery arrangements, equipment usage, and administrative work. The amount can vary according to the recovery company’s pricing structure and the complexity of the assignment.
Some recovery operations are straightforward because the vehicle is parked in an accessible location. Others require additional time because the automobile is difficult to locate or cannot be moved without specialized assistance.
Recovery companies may also charge for after-hours services. If a repossession takes place during weekends, holidays, or outside regular business hours, the service provider may apply an additional fee where permitted.
The lender may include the recovery service charge in the borrower’s outstanding balance. This means the amount can remain payable even after the vehicle has been taken from the borrower’s possession.
Borrowers should understand that repossession fees are generally subject to the loan agreement and applicable laws. A lender cannot necessarily add every amount requested by a third-party recovery company without considering whether the expense is legally recoverable.
An itemized statement can help distinguish professional recovery charges from towing, storage, and administrative expenses. This separation makes it easier to identify duplicate billing.
It is also important to check whether the recovery company followed the legal requirements during the repossession. Unlawful recovery practices may create grounds for a dispute, depending on the jurisdiction and circumstances.
4. Administrative and Processing Fees
Administrative fees are expenses associated with managing the repossession process. Lenders may charge these amounts for handling paperwork, updating loan records, coordinating recovery services, preparing notices, and managing communication with third-party companies.
These charges are often less noticeable than towing or storage expenses because they may appear under general descriptions on a loan statement. Terms such as processing fee, account management charge, or repossession administration cost may be used.
The amount varies between financial institutions. Some lenders use a fixed administrative fee, while others calculate charges according to their internal policies and the services performed.
Processing costs may include preparing repossession documents, recording the vehicle’s recovery, updating the borrower’s account, and arranging the transfer of ownership or possession for an eventual sale.
Certain lenders may also charge for preparing and sending formal notices to borrowers. These communications can explain the repossession, provide information about the outstanding balance, and describe the steps required to recover personal belongings or redeem the vehicle where applicable.
Administrative fees should not be confused with unrelated account charges. Borrowers should check whether a processing amount has already been included in another repossession expense to avoid paying twice for the same service.
A detailed loan statement can help clarify the purpose of these charges. If the lender provides only a general description, borrowers can request an explanation and supporting documentation.
Reviewing administrative fees is particularly important when the total repossession expense appears significantly higher than expected. Clear records allow borrowers to determine whether the charges are supported by the agreement and applicable regulations.
5. Legal and Attorney Fees
Legal expenses may become part of an overdue car loan when repossession involves legal procedures, disputes, or additional enforcement work. Depending on the financing agreement and local laws, lenders may seek reimbursement for certain legal costs.
An attorney may assist the lender with reviewing loan documents, preparing legal notices, addressing disputes, or handling court-related matters. These services can generate professional fees that may be added to the amount owed when legally permitted.
Legal expenses can increase when a borrower challenges the repossession or raises concerns about the lender’s recovery practices. Resolving disagreements may require legal correspondence, document reviews, or formal proceedings.
Court filing fees may also arise when the lender needs judicial assistance. For example, certain jurisdictions require court involvement in specific recovery situations or disputes concerning possession of a vehicle.
The amount charged depends on the type of legal service, the complexity of the matter, and the attorney’s fee arrangement. Some cases involve limited paperwork, while others require more extensive legal work.
Borrowers should carefully review whether the loan agreement allows the lender to recover attorney fees. The existence of a repossession does not automatically make every legal expense chargeable to the borrower.
It is reasonable to request an itemized breakdown showing the services performed, dates, and amounts charged. This information helps borrowers determine whether the legal expenses relate directly to the repossession.
If a legal fee appears unreasonable or unsupported, borrowers may seek advice from a qualified consumer law attorney. Understanding their rights can help them challenge improper charges and avoid accepting an inaccurate loan balance.
6. Vehicle Inspection and Condition Assessment Fees
Once a vehicle has been recovered, the lender may arrange an inspection to assess its condition. This process helps determine the automobile’s current market value and whether it requires repairs before being offered for sale.
Inspection fees may cover the cost of examining the exterior, interior, engine compartment, tires, and other major components. The inspection may also include recording existing damage and preparing a condition report.
A professional assessment can help the lender understand whether the vehicle has scratches, dents, broken components, mechanical problems, or signs of neglect. These findings may influence the estimated resale value.
Some lenders use independent vehicle inspection companies, while others rely on auction partners or contracted service providers. The charges depend on the inspection arrangement and the services included.
Photographic documentation may form part of the inspection process. Pictures provide a record of the vehicle’s condition at the time of repossession and may help establish its value before an auction.
In certain cases, lenders may arrange a more detailed mechanical inspection. This can involve checking the engine, transmission, battery, braking system, and other important components.
Borrowers should understand that inspection expenses are not automatically recoverable in every situation. The lender must have a valid basis for adding these charges under the agreement and relevant consumer protection laws.
Requesting the inspection report can help borrowers verify the condition assessment and understand whether the related expenses are legitimate. It can also provide useful information if they dispute the vehicle’s valuation or the final amount owed after its sale.
7. Vehicle Cleaning and Preparation Charges
Before a repossessed vehicle is listed for sale, the lender or auction company may arrange basic cleaning and preparation services. These activities help present the automobile in a suitable condition for potential buyers.
Cleaning expenses may include washing the exterior, vacuuming the interior, removing loose debris, and wiping down surfaces. The extent of the work depends on the vehicle’s condition and the auction company’s preparation standards.
Some vehicles require additional attention because they contain dirt, stains, food waste, or other material that affects their presentation. In these situations, the service provider may charge more for specialized cleaning.
Interior detailing can involve cleaning seats, carpets, dashboards, door panels, and other surfaces. However, extensive detailing is not necessarily required for every repossessed automobile.
Lenders may also arrange minor preparation work before an auction. This can include replacing small components, securing loose parts, or addressing basic issues that could affect the vehicle’s presentation.
Preparation charges should be distinguished from major repair expenses. Routine cleaning is different from replacing mechanical components or repairing significant collision damage.
Borrowers should review whether these services were actually performed and whether the costs were reasonable. A general cleaning fee without supporting details may deserve further clarification.
The lender’s ability to recover cleaning and preparation expenses depends on the applicable agreement and legal requirements. Borrowers can request invoices to confirm the work completed and the amount charged by the service provider.
8. Auction and Vehicle Sale Fees
When a lender repossesses a vehicle, selling it through an auction is a common method of recovering the outstanding loan balance. However, arranging the sale can involve several expenses that may be included in the borrower’s account.
Auction fees may cover listing the vehicle, registering it for sale, processing buyer transactions, and providing space for the auction event. The charges vary according to the auction company’s pricing policies.
Some auction companies charge a fixed fee for every vehicle sold. Others apply charges based on the sale price or the services selected by the lender.
Transportation to the auction facility can also create additional expenses. A repossessed vehicle may need to be moved from an impound lot to a separate auction location before it can be offered to buyers.
Auction preparation may include photographing the automobile, creating a vehicle description, recording its condition, and assigning it to a scheduled sale. These activities can generate separate service charges.
Certain auction providers may charge storage or handling fees while the vehicle waits for a suitable sale date. Such expenses can accumulate when the auction is postponed or the automobile does not sell immediately.
The sale proceeds are generally applied toward the outstanding loan balance and other legally recoverable amounts. If the proceeds are insufficient, the borrower may remain responsible for a deficiency balance, depending on local laws and the loan agreement.
Borrowers should request a copy of the final sale statement. It should identify the sale price, applicable fees, deductions, and the amount credited to the loan account.
9. Locksmith and Key Replacement Charges
A repossession company may encounter situations where the vehicle cannot be accessed using an available key. This can happen when the borrower is unavailable, the original key is missing, or the vehicle is locked and requires professional assistance.
In these circumstances, the lender may arrange locksmith services to gain access to the automobile. The locksmith’s charges may be included in the repossession expenses when permitted by the agreement and applicable laws.
Traditional vehicles may require basic key replacement or lock-related services. Modern automobiles can involve more complicated procedures because they often use electronic keys, transponder chips, and advanced security systems.
Smart keys and keyless entry systems may be particularly expensive to replace. These systems sometimes require specialized programming equipment and vehicle-specific electronic components.
Locksmith fees can also depend on the time and location of the service. Emergency assistance outside normal business hours may cost more than a scheduled appointment.
In certain cases, the recovery company may need to arrange a replacement key to move the vehicle safely. The expense may involve cutting a physical key, programming an electronic fob, or coordinating with an authorized dealership.
Borrowers should ask for an itemized locksmith invoice showing the service performed, replacement parts, labor, and programming charges. This helps establish whether the amount is reasonable.
It is also worth checking whether the lender has included the same locksmith service under multiple expense categories. Duplicate charges should be questioned before accepting the final repossession balance.
10. Deficiency Balance and Additional Loan Charges
A deficiency balance is the amount remaining on a car loan after the repossessed vehicle has been sold and the applicable sale proceeds have been credited to the account. It can become the most financially significant consequence of vehicle repossession.
For example, suppose a borrower owes $18,000 on a vehicle when the lender repossesses it. The lender later sells the automobile for $12,000. If $2,000 in permitted repossession and sale expenses applies, the remaining deficiency would be $8,000.
This example assumes the full sale price is credited to the loan and that all listed expenses are legally recoverable. Actual calculations depend on the loan agreement, payment history, sale procedures, and applicable laws.
The deficiency amount may also include unpaid interest and certain contractual charges that accumulated before the sale. The lender must calculate these amounts according to the financing agreement and relevant regulations.
Late payment charges can contribute to the outstanding balance when borrowers miss scheduled installments. These fees may accumulate before repossession and increase the amount required to settle the account.
Some loan agreements allow lenders to charge interest on unpaid balances after repossession. Whether this is permitted and how it is calculated depends on the contract and local legal requirements.
Borrowers should request a complete deficiency statement showing the original balance, payments received, repossession expenses, auction proceeds, interest, and remaining amount. This document provides a clearer picture of the lender’s calculation.
If the vehicle sells for less than its reasonable market value, borrowers may have grounds to question the sale process in certain circumstances. Applicable laws may require lenders to conduct a commercially reasonable sale and provide proper notice.
A deficiency balance does not always mean the lender’s calculation is correct. Reviewing the figures, checking the sale documentation, and obtaining legal or financial advice can help borrowers understand their remaining obligations.