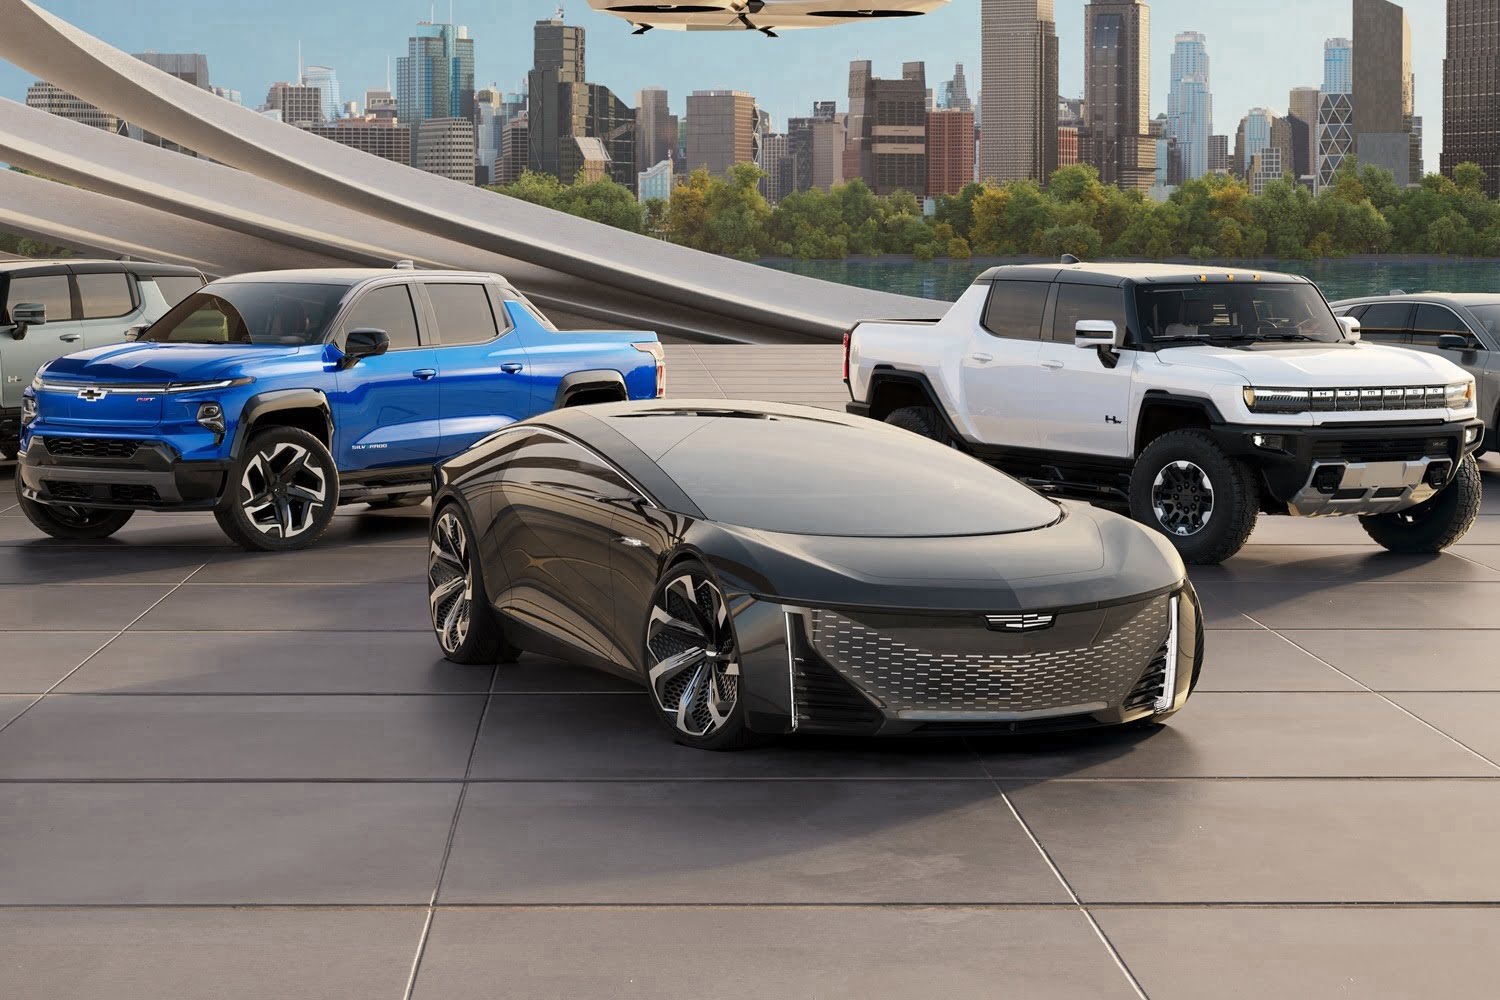
General Motors delivered stronger third-quarter earnings in 2026, supported by demand for its full-size pickup trucks, but the automaker is warning that rising material and logistics costs could put pressure on future profits.
On October 20, GM reported adjusted earnings before interest and taxes of $4.1 billion, up 22% from the same period a year earlier. The company also authorized a new $20 billion multiyear share-repurchase program, even as it prepared for lower truck deliveries during production changes ahead of redesigned Chevrolet Silverado and GMC Sierra models.
GM’s results reveal a mixed business outlook, with its truck division continuing to deliver strong profits while rising expenses and upcoming model changes could create greater challenges in the years ahead.
For the U.S. automotive market, the report also raises questions about how long pickup demand can offset inflationary pressures and changes in vehicle sales mix.
Pickup Trucks Drive a 22% Increase in Adjusted Earnings.
GM reported third-quarter revenue of $50.0 billion, up approximately 2.9% from $48.6 billion in the same quarter of 2025. Adjusted EBIT reached $4.1 billion, compared with $3.4 billion a year earlier, while adjusted earnings per share rose to $3.70 from $2.80. The results exceeded analysts’ expectations for adjusted earnings per share, according to Reuters.
The strength came partly from a more profitable mix of vehicles. GM sold a higher proportion of large pickup trucks, which typically generate more revenue per vehicle than smaller models. The company also reported lower warranty expenses, helping offset some of the pressure from higher commodity and onshoring costs.
The results show how product mix and manufacturing expenses can influence earnings even when total revenue rises by a smaller percentage.
GM North America reported adjusted EBIT of approximately $3.6 billion, up from $2.5 billion a year earlier. That performance underlines the importance of the U.S. market and full-size trucks to the company’s financial results.
Its international operations were considerably weaker, with adjusted EBIT of $28 million, compared with $226 million in the prior-year quarter.
The earnings increase does not mean every part of GM’s business is improving at the same pace. Electric-vehicle volumes declined compared with the year-earlier period, while the company continued adjusting EV production to match demand.
GM’s results therefore reflect a mix of stronger traditional vehicle earnings and changes in its electric-vehicle business, rather than broad growth across every segment.
That distinction matters because GM’s profitability remains heavily influenced by full-size pickups and SUVs. These vehicles help generate substantial earnings, but their production schedules, consumer demand, and manufacturing costs can have an outsized effect on quarterly results.
The upcoming redesigns of the Silverado and Sierra make the timing of production changes especially important.
Higher Material Costs and Truck Production Create 2027 Risks
Despite the strong quarter, GM warned that rising costs are making the outlook more difficult. Chief Financial Officer Paul Jacobson said steel, aluminum, and logistics expenses had increased sharply over the previous two months.
The company estimated that commodity inflation, including higher logistics and computer-chip expenses, would total about $2 billion in 2026, at the upper end of its earlier forecast. GM also expected gross tariff costs to reach the lower end of its projected $2.5 billion to $3.5 billion range.
The pressure is significant because a vehicle’s profitability depends on more than its sticker price. Manufacturers must account for the cost of raw materials, components, transportation, labor, and factory operations.
If steel or aluminum becomes more expensive, GM may face higher costs across vehicle production. Logistics increases can add further expense when parts and finished vehicles need to move between suppliers, assembly plants, and dealerships.
Automakers have several ways to respond, but none is automatic. They can negotiate with suppliers, adjust production schedules, reduce other costs, or change vehicle pricing. Passing costs on to consumers can be difficult if buyers are already sensitive to financing rates and monthly payments.
Absorbing the increases, meanwhile, can reduce profit margins if vehicle prices and sales volumes do not compensate.
GM also expects a weaker fourth quarter for full-size truck deliveries as it prepares to launch redesigned versions of the Chevrolet Silverado and GMC Sierra. Production changes and factory preparation can temporarily reduce the number of vehicles available for sale, even when the long-term purpose is to introduce updated products.
Reuters reported that GM expected to sell approximately 35,000 fewer full-size pickups in the fourth quarter than a year earlier.
The company has tightened its full-year 2026 adjusted earnings-per-share guidance to a range of $12.75 to $13.75. Its updated adjusted EBIT forecast is $14.5 billion to $15.5 billion, compared with the previous range of $14 billion to $16 billion.
The narrower EBIT range does not represent a simple across-the-board reduction, but it signals a more defined outlook amid rising costs and changing production volumes.
Looking further ahead, GM said its 2027 results would depend on continued consumer demand and some moderation in commodity and logistics pressures.
If those costs remain elevated, Jacobson warned, they could weigh on earnings by as much as $2 billion next year. That figure is a potential impact under persistent cost pressure, not a confirmed loss or a guaranteed reduction in profit.
The redesigned pickups will therefore be important to GM’s next financial chapter. New models can help maintain customer interest and support sales, but launching them requires manufacturing changes that can disrupt deliveries in the short term.
The company must balance those transition costs against the longer-term goal of keeping its biggest profit-generating vehicles competitive.
GM Approves a $20 Billion Share-Buyback Program.
Alongside its earnings report, GM announced that its board had approved a new $20 billion multiyear share-repurchase authorization. The company had completed a previous $6 billion buyback program announced in January 2026. The new authorization has no fixed expiration date and can be suspended or discontinued at the company’s discretion.
A share buyback allows a company to repurchase its own stock, reducing the number of shares outstanding if the repurchased shares are not reissued.
That can increase earnings per share by spreading earnings across fewer shares, although it does not automatically improve the company’s underlying operating performance. The authorization also does not mean GM will spend the full $20 billion immediately.
GM’s outstanding share count had fallen to 849 million at the end of September 2026, down from 904 million at the end of 2025 and 995 million at the end of 2024. The company said the new authorization reflects its approach to returning capital to shareholders while continuing to invest in future products and technology.
Investors nevertheless focused on the cautious outlook as well as the buyback. Reuters reported that GM shares fell about 5% in morning trading after the results, as the company’s updated earnings guidance and warning about rising expenses weighed on sentiment.
The reaction illustrates that strong quarterly earnings do not necessarily reassure investors when future costs and delivery volumes are uncertain.
GM’s results leave the company with two competing priorities. Its pickup and SUV business continues to generate substantial earnings, providing funds for shareholder returns and investment.
At the same time, rising steel, aluminum, and logistics expenses, along with production adjustments for redesigned trucks, could make future quarters more difficult.
For U.S. buyers, the earnings report does not signal an immediate price change for Silverado or Sierra models.
However, manufacturing costs, inventory levels, and the timing of redesigned vehicles can influence the discounts and availability customers encounter at dealerships. The impact will depend on how production develops and how GM responds to cost pressures.
The central question for 2027 is whether GM can sustain strong truck profitability while absorbing higher expenses and completing its model launches.
The third-quarter figures demonstrate the strength of its current business, but the company’s own outlook makes clear that continued performance will depend on costs moderating, demand holding up, and the transition to redesigned pickups proceeding as planned.