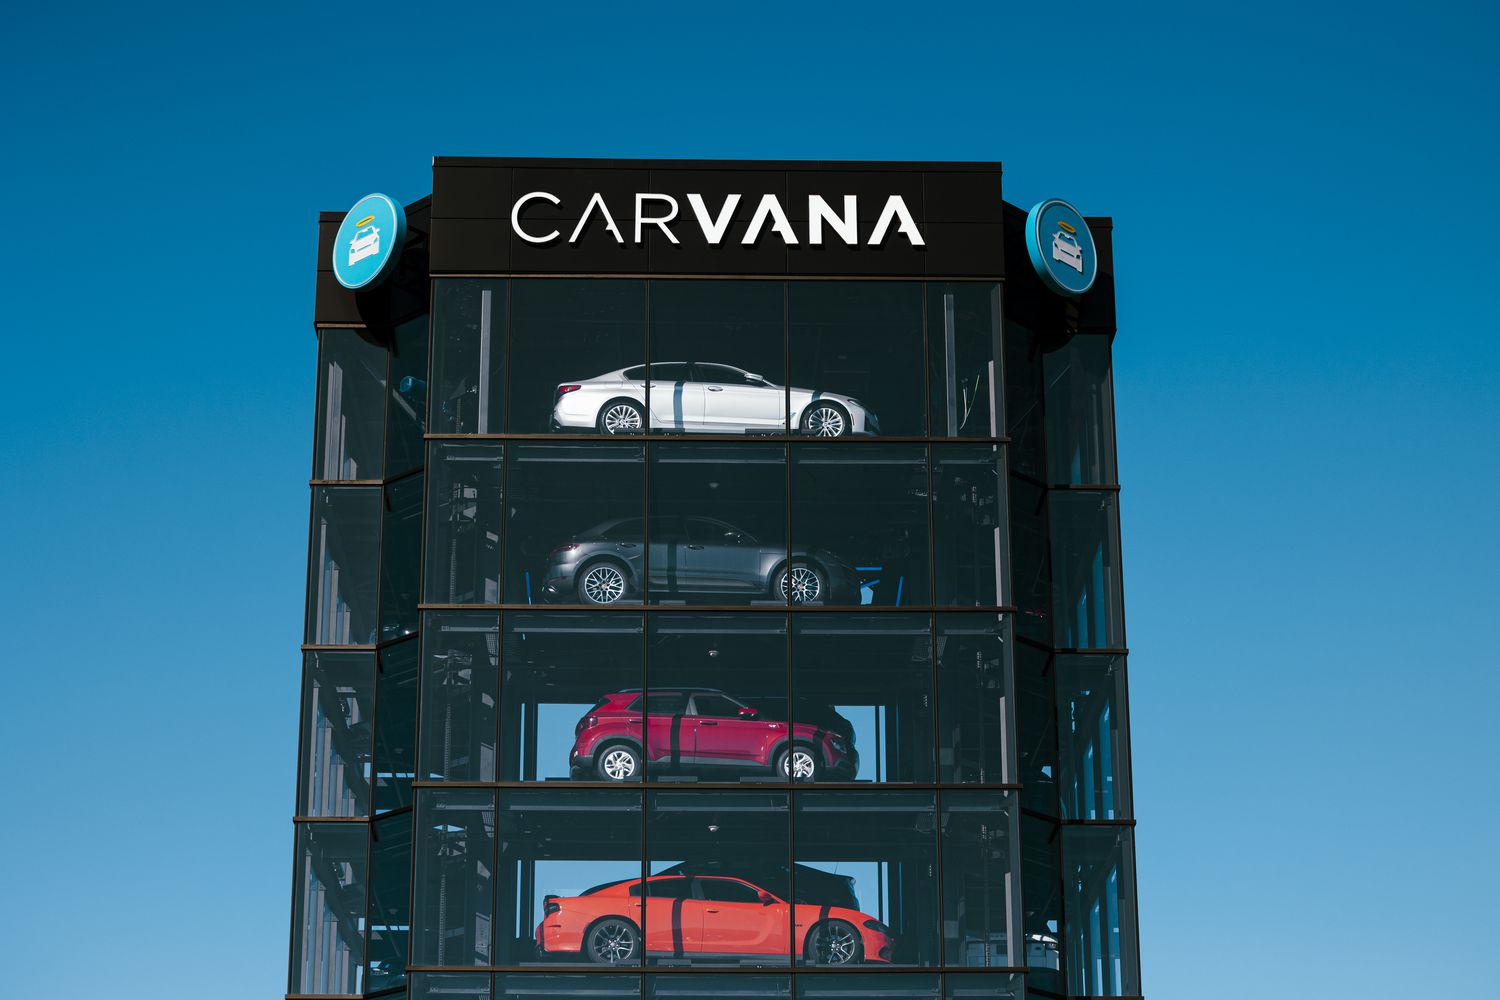
Carvana delivered its strongest quarterly performance to date in the third quarter of 2026, reporting $8.04 billion in revenue as retail vehicle sales climbed 39% year over year to 217,385 units. The online used-car retailer also posted a record-adjusted EBITDA of $800 million and a net income of $483 million.
The results stand out because the broader U.S. automotive market was approximately flat over the same period, suggesting that Carvana’s expansion came largely from winning customers from competitors rather than from a rising market.
Its performance highlights the growing role of online platforms in used-car retailing while also raising questions about whether the company can maintain rapid growth without sacrificing the profitability that has become central to its recovery.
Record Revenue and Vehicle Sales Mark Another Growth Quarter
Carvana announced its third-quarter results on October 28, 2026, reporting revenue of $8.040 billion, an increase of 42% from $5.647 billion a year earlier. Retail vehicle sales reached 217,385 units, up 39% from 155,941 in the same quarter of 2025.
Both figures set new quarterly records. The company said it had crossed 200,000 retail units in a single quarter for the first time, and its retail volume was approximately double the level it recorded two years earlier.
The growth is notable against the wider market. Carvana’s shareholder letter said the broader automotive industry was approximately flat year over year in the third quarter. The company attributed its expansion to market-share gains, pointing to its vehicle selection, customer experience, and value proposition.
Its current retail sales pace equates to an annualized run rate of about 870,000 units. Carvana estimated that this represents roughly 2% of the used-vehicle market and around 1.5% of the total automotive market, leaving room for further expansion if it can continue attracting buyers.
Retail vehicle sales generated approximately $6.14 billion of the quarter’s revenue, up 53.8% year over year. Wholesale sales and revenue contributed about $1.30 billion, while other sales and revenue added approximately $594 million.
These additional activities matter to the business model. Carvana buys vehicles from consumers and dealers, sells some vehicles through wholesale channels, originates financing, and earns revenue from complementary products.
The company therefore makes money through more than the final retail transaction displayed on its website.
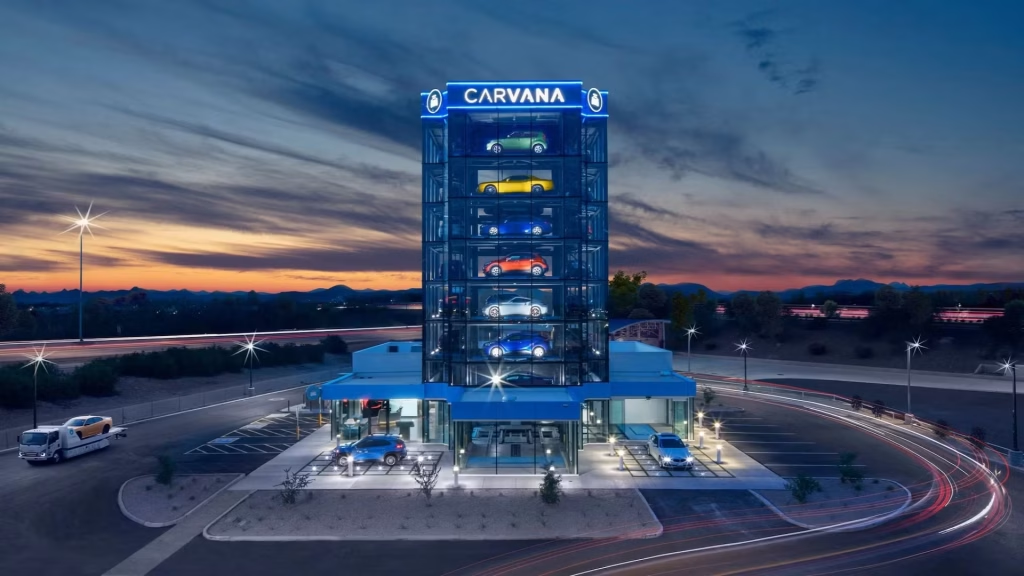
Carvana’s online process allows customers to browse inventory, arrange financing, complete paperwork, and schedule delivery digitally. It also operates inspection and reconditioning centers and logistics infrastructure to prepare and transport vehicles.
The combination of online retailing and physical operations is essential because used vehicles still need to be inspected, reconditioned when necessary, stored, and delivered. While the digital platform streamlines the buying process, the business relies on an extensive operational network to support every transaction.
Profitability Improves, but Per-Vehicle Economics Need Watching
Carvana reported net income of $483 million for the quarter, an increase of $220 million from the same period a year earlier. Net income margin improved to 6.0%, compared with 4.7% in the third quarter of 2025.
Adjusted EBITDA reached a record $800 million, up $163 million year over year, although its margin declined to 10.0% from 11.3%. GAAP operating income was $714 million, with an operating margin of 8.9%, compared with 9.8% a year earlier.
The difference between rising profit dollars and a lower adjusted EBITDA margin is important. Carvana is selling substantially more vehicles, so it can generate a larger amount of earnings even if each dollar of revenue produces a smaller adjusted EBITDA contribution.
The margin decline shows that growth is not automatically improving every measure of efficiency. Investors will want to see whether the company can keep expanding while protecting the profitability of each transaction.
Total gross profit increased 32% to $1.521 billion, slower than the 42% increase in revenue. Gross profit per retail unit was $6,997, down 5% from $7,362 a year earlier. Carvana’s non-GAAP total gross profit per unit was $7,093, a decrease of $410.
The company reported reducing customer interest rates relative to benchmark rates, sacrificing some finance-related revenue in an effort to offer buyers more attractive financing terms. This highlights a clear trade-off. Lower rates can make vehicles more appealing to customers, but they may also reduce the revenue generated from each sale.
Retail vehicle gross profit per unit increased modestly to $3,556 from $3,456. However, wholesale gross profit per retail unit fell to $708 from $866, while other gross profit per retail unit declined to $2,733 from $3,040.
These figures show that the company’s different revenue streams are not growing at the same rate. A strong headline sales result can conceal pressure in individual parts of the business, making gross profit per unit an important metric to follow alongside total revenue.
Carvana Expects Further Growth as Online Used-Car Retailing Expands
Carvana expects retail unit sales to increase sequentially in the fourth quarter, provided the operating environment remains stable. It also expects full-year 2026 adjusted EBITDA to land toward the higher end of its previously communicated range of $2.7 billion to $3.0 billion.
This outlook indicates management believes the momentum from the first nine months can continue, although the company’s forecast is conditional and not a guarantee of results.
The company’s growth strategy relies on improving the customer experience while expanding its ability to source, inspect, and deliver vehicles.
In its shareholder letter, management said customers had access to twice as many selections, delivery times that were two days faster, and lower interest rates on loans relative to benchmarks over the past two years.
Carvana also reported a nine-point improvement in its Net Promoter Score during that period. These are company-reported measures, but they show the areas where management believes it is gaining an advantage over traditional retailers.
Scale is central to the model. A larger inventory can attract more shoppers, while more transactions can help spread fixed technology, logistics, and reconditioning costs across a higher number of sales.
Yet expansion also requires working capital, vehicle acquisition capacity, transportation, staffing, and inspection facilities. If Carvana grows faster than its operations can support, delivery delays, reconditioning bottlenecks, or inconsistent vehicle quality could weaken the customer experience it is trying to sell.
Competition is another factor. Traditional dealership groups have expanded online shopping, home delivery, and digital financing, reducing the distinction between internet-based and physical retailers.
Carvana must continue to offer a compelling selection, transparent pricing, and convenient delivery while competing with dealers that have established local relationships and service networks. Used-car supply and wholesale prices can also change quickly, affecting how much the company pays to acquire vehicles and the margin available when it resells them.
Carvana’s third-quarter results show that online used-car retailing can reach substantial scale while producing meaningful profits. The company sold more than 217,000 retail vehicles in one quarter and generated over $8 billion in revenue, while the wider market remained roughly flat.
But the lower adjusted EBITDA margin and decline in gross profit per unit underline the need to balance growth with transaction economics. The next test is whether Carvana can keep gaining market share, increase fourth-quarter sales, and deliver its earnings outlook without allowing per-vehicle profitability to deteriorate further.
Its record quarter strengthens its position in U.S. used-car retailing, but sustained performance will depend on execution as well as demand.